Contactless & NFC Payments: Safety and Convenience in 2025

Contactless and NFC payments have rapidly moved from being a futuristic concept to an everyday essential, reshaping how people make purchases across stores, restaurants, and transportation. In 2025, this technology has become even more refined, offering faster transactions, stronger security, and seamless integration into daily life. As more consumers embrace digital wallets and tap-to-pay methods, understanding the benefits and safety features behind them has become increasingly important.

Why Contactless Payments Have Become the New Standard

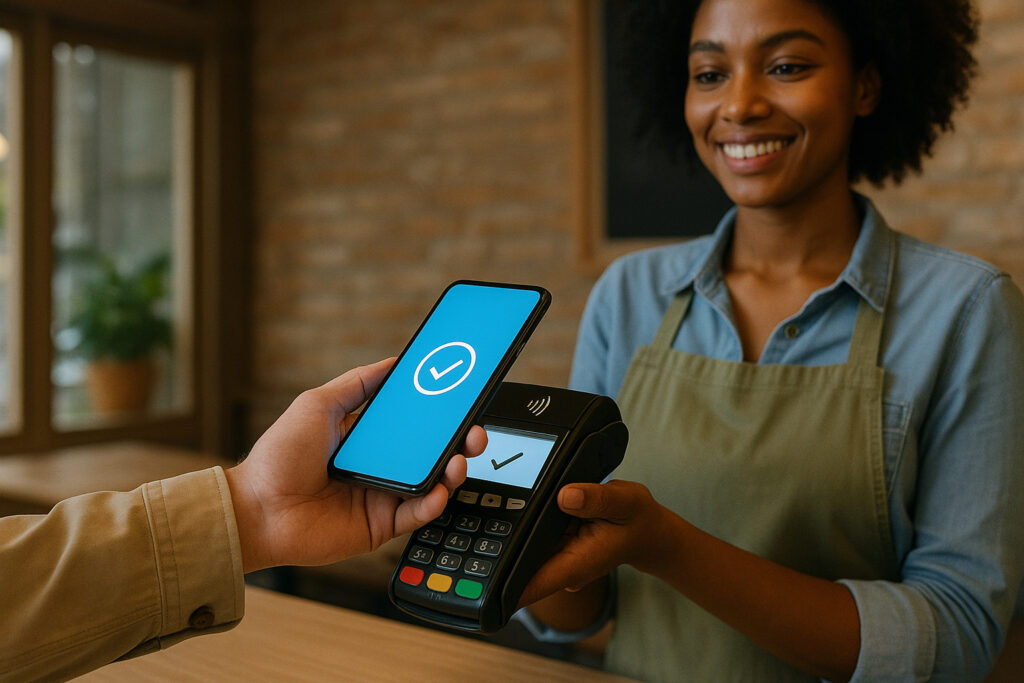
The convenience of tapping a card or phone has significantly improved checkout experiences. Instead of handling cash or waiting for chip-card processing, NFC-enabled devices allow transactions to complete in seconds. With more retailers adopting compatible terminals, consumers enjoy quicker, smoother interactions. This level of convenience has driven steady growth in tap-to-pay usage, making it a preferred method for everyday spending.

Enhanced Security Through Advanced Encryption

Despite their simplicity, contactless payments prioritize strong security. NFC transactions use tokenization—replacing sensitive card information with randomized digital tokens. This means even if data is intercepted, it cannot be traced back to an actual account. Additionally, biometric authentication on smartphones adds another layer of protection. These features work together to reduce fraud risk and keep payment details private.

Growing Adoption of Digital Wallets

Digital wallets have become more powerful, serving as secure hubs for payment cards, transit passes, and loyalty programs. Whether using a smartwatch or smartphone, consumers can manage several financial tools in one place. This streamlined experience encourages greater adoption, especially among shoppers who prioritize convenience. With increased merchant acceptance, digital wallets now fit naturally into everyday routines.

Contactless Payments in Public Transportation and Retail

2025 has seen widespread adoption of tap-to-pay systems in transit, allowing riders to use cards or mobile devices at entry gates without purchasing separate passes. Retailers benefit as well—faster lines, reduced cash handling, and improved customer satisfaction. This expansion continues to make contactless payments a practical choice across industries.

The Future: More Integration, Less Friction

Looking ahead, contactless and NFC solutions are becoming more integrated with smart devices, cars, and wearables. As ecosystems grow, consumers will enjoy an even more frictionless experience. The combination of convenience, speed, and safety ensures that NFC will remain a dominant payment method for years to come.

Conclusion

In 2025, contactless and NFC payments deliver a powerful mix of convenience and security. With faster checkouts, advanced encryption, and widespread availability, these technologies make everyday purchases simple and safe. As innovation continues, tap-to-pay methods will only become more intuitive and accessible.
Credit Scores and Insurance Premiums: The Surprising Connection

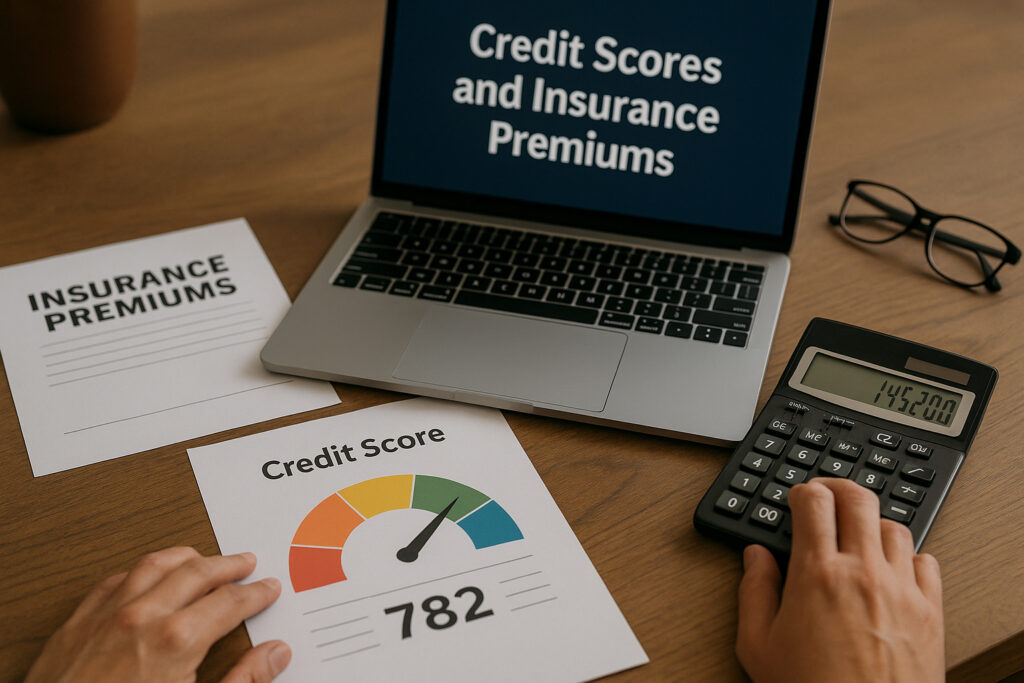
Many people think credit scores only matter when applying for loans or credit cards—but they also play a significant role in determining insurance premiums. Whether it’s auto, home, or renters insurance, companies often use credit-based scoring models to predict how likely someone is to file a claim. This surprising connection can influence how much you pay each month, even if you’ve never had an accident or made a claim before. Understanding how credit impacts insurance costs helps you stay informed and take steps to manage your financial profile more effectively.

Why Insurers Use Credit Information

Insurance companies use data to estimate risk. Over the years, industry studies have shown a correlation between strong credit habits and lower claim likelihood. Because of this, insurers use credit-based insurance scores—not your full credit score—to predict customer behavior. These scores help determine how risky you may be to insure, which affects the rate you’re offered. While it may seem unrelated, insurers see credit history as a reflection of responsibility and long-term financial stability.

How Credit Influences Your Premiums

A higher credit score often leads to lower premiums. People with excellent credit tend to qualify for cheaper auto and home insurance rates. On the other hand, a lower score can increase monthly premiums even if your driving record or claim history is clean. For insurers, it’s all about statistical patterns—not personal judgment. Small improvements in your credit score can make a noticeable difference in the cost of your policy over time.

Which Types of Insurance Are Affected

Auto and homeowners insurance are the most common types where credit-based scoring is used. Renters insurance may also be affected, depending on the state and the insurer. Health insurance and life insurance typically do not use credit scores for pricing, but they may still review credit behavior during the application process. Knowing which policies rely on credit information helps you plan and budget more accurately.

Ways to Improve Your Insurance Rates

Because insurance premiums are influenced by credit, improving your score can lead to meaningful savings. Paying bills on time, lowering credit card balances, and reducing debt all contribute to a healthier financial profile. Checking your report regularly also helps you spot errors that could raise your premiums. As your credit score strengthens, you can request a rate review or compare quotes from multiple insurers to find better pricing.

Conclusion

Credit scores play a bigger role in insurance premiums than most people realize. By understanding this connection and taking steps to maintain strong credit habits, you can reduce costs and secure better long-term coverage. Improving your credit doesn’t just help with loans—it also unlocks lower insurance rates and greater financial stability.

Health Behavior Credits: Earn Lower Premiums Through Daily Wellness Scores

Health insurance is undergoing a major shift toward personalization, and one of the most exciting developments is the rise of Health Behavior Credits—a system where daily wellness actions can directly reduce monthly premiums. Instead of treating everyone the same, insurers now reward individuals who consistently make healthier choices, creating a win-win model that improves well-being while lowering financial costs.

Daily Habits Turn into Real Savings

Wellness credits are based on measurable, everyday behaviors taken, hours slept, activity consistency, balanced routines, or even stress-reduction practices. Small habits such as taking regular walks, choosing healthier meals, or maintaining steady sleep patterns accumulate into a daily wellness score. Over time, these scores can translate into noticeable premium discounts.

Smart Devices Make Tracking Automatic

Wearables, fitness apps, smart scales, and activity trackers make this system effortless. Instead of filling out forms or self-reporting habits, data is collected automatically through devices people already use. This helps create accurate wellness profiles and eliminates guesswork or bias. The healthier someone’s patterns, the more they benefit.

Motivation Built into the Insurance Experience

Health Behavior Credits turn wellness into a rewarding routine. By showing people how their actions influence costs, insurers create motivation loops that encourage healthier choices. Customers begin to view insurance not just as protection, but as a supportive partner in their daily health goals.

Fairer Pricing for Individuals

Traditional insurance often groups people by broad demographics. Wellness-based pricing shifts the focus to what you do, not who you are. This makes premiums more personalized and fairer. Two people of the same age can now pay very different rates based on their actual health habits, not assumptions.

Conclusion

Health Behavior Credits are redefining insurance by making wellness measurable, meaningful, and financially rewarding. By turning everyday actions into discounts, insurers support healthier lives while giving customers direct control over their premiums. As this model expands, it promises a future where personal health habits drive both well-being and financial benefits.

Choosing Between No Annual Fee and Premium Credit Cards

Choosing the right credit card can feel overwhelming, especially when deciding between a no annual fee card and a premium card with a yearly cost. Both options offer valuable features, but the best choice depends on your spending habits, financial goals, and how much value you expect from rewards and benefits. Understanding the differences helps you make a confident decision that fits your lifestyle and long-term money strategy.

Understanding the Value of No Annual Fee Cards

No annual fee credit cards appeal to people who want a simple, cost-effective solution without extra financial commitments. These cards are ideal for everyday purchases, occasional travel, or building credit with minimal risk. While rewards may be smaller compared to premium cards, these cards often include cashback, basic fraud protection, and introductory offers. For those who prefer to avoid yearly fees—or who use credit cards sparingly—no-fee cards provide solid value without ongoing expenses.

Why Premium Cards Charge an Annual Fee

Premium credit cards come with higher costs, but in return, they offer elevated rewards and exclusive benefits. These may include airport lounge access, travel credits, elite status perks, better insurance coverage, and stronger reward multipliers on travel, dining, and shopping. Frequent travelers or high-spending cardholders often find that these perks offset the annual fee. If you consistently use the benefits, the net value can be significantly higher than with basic cards.

Matching Your Card Choice to Your Lifestyle

The right card depends on how you spend and what you value most. If you prioritize savings, simplicity, and low-maintenance financial tools, a no annual fee card is likely a better match. In contrast, if you travel regularly, dine out frequently, or want premium experiences and high-value rewards, a premium card may deliver far more benefits. Tracking your typical monthly expenses can help reveal which card type generates the greatest return.

Considering Long-Term Financial Impact

Credit cards should fit your long-term financial strategy—not just short-term perks. Avoid premium cards if you’re unable to consistently use their benefits or if you plan to carry a balance, since interest charges can outweigh any rewards. No annual fee cards are ideal for maintaining credit history without ongoing costs, making them a strong long-term option. Evaluate how each card contributes to your financial stability, credit score, and reward potential.

Conclusion

Choosing between no annual fee and premium credit cards comes down to lifestyle, spending habits, and the value you expect from rewards and perks. Premium cards shine for frequent travelers and high spenders, while no-fee cards provide smart, low-cost financial flexibility. By understanding your goals and usage patterns, you can select the card that supports your financial well-being and delivers the best overall value.

The Future of Credit Scores in a Cashless Economy

As digital payments become the standard for everyday transactions, traditional measures of creditworthiness are starting to evolve. A cashless economy creates new patterns of financial behavior, offering more data points than ever before. This shift is prompting lenders and financial institutions to rethink how they evaluate risk and reliability. With technology reshaping spending, saving, and borrowing, the future of credit scoring is likely to look very different—and potentially more inclusive—than what we know today.

How Digital Payments Are Changing Financial Behavior

The rise of digital wallets, contactless payments, and peer-to-peer apps provides a clearer picture of how people manage day-to-day finances. These systems track spending in real time, making financial habits easier to monitor. As cash usage declines, digital footprints reveal consistent patterns—such as timely bill payments, responsible budgeting, and overall financial discipline—which may one day serve as indicators of creditworthiness.

New Data Sources May Expand Access

One of the biggest promises of a cashless economy is the potential for alternative data to support credit evaluations. Lenders may incorporate factors like rent payments, subscription history, utilities, or digital transaction records. For people with limited credit history, these signals could bridge the gap and provide opportunities previously out of reach. This shift could promote fairness by recognizing responsible behavior beyond traditional loans and credit cards.

Technology Will Play a Central Role

Artificial intelligence and advanced analytics are expected to influence future scoring models. These tools can analyze massive amounts of data quickly, identifying trends that would be difficult for humans to interpret. Smart algorithms may predict risk with greater accuracy while adapting to changes in financial behavior. This enhanced precision benefits both consumers and lenders, creating a more stable and transparent credit ecosystem.

Balancing Innovation With Privacy

While expanded data can improve credit access, it also raises concerns around privacy and security. Consumers may worry about how much personal financial information is being tracked and who controls it. As scoring models evolve, regulations and strong data protections will play a critical role in maintaining trust. The challenge will be finding the right balance between innovation and responsible use of digital financial data.

Conclusion

A cashless economy opens the door to a more dynamic, data-driven approach to credit scoring. As digital payments become universal, the future of credit may better reflect consumers’ everyday financial habits—creating a system that is more inclusive, accurate, and aligned with modern life.

Atmospheric Health Coverage: Insurance That Activates Based on Air-Quality Sensors

As air pollution becomes a growing concern in modern cities, a new form of protection is emerging atmospheric health coverage. Unlike traditional insurance, which responds only after a health issue occurs, this coverage activates instantly when air-quality sensors detect unsafe environmental conditions. By combining environmental technology with preventative health care, it creates a safety net designed for a world where poor air quality increasingly affects daily life.

Real-Time Protection Powered by Air-Quality Sensors

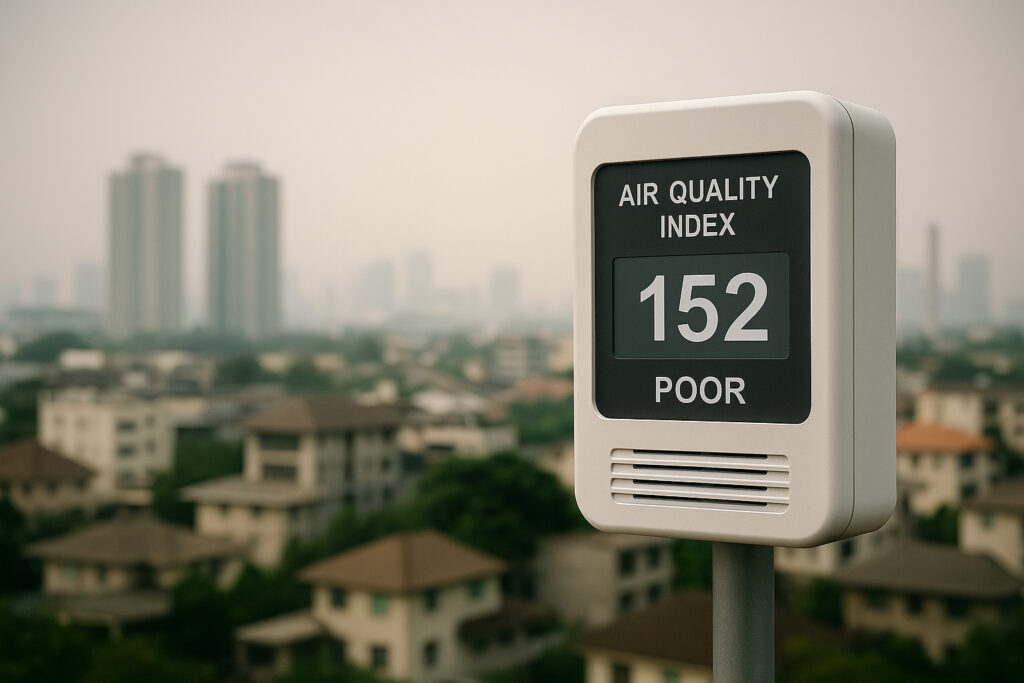
Atmospheric health coverage relies on networks of air-quality sensors—both public and personal—to track pollutants like PM2.5, ozone, and toxic chemicals. When readings cross a harmful threshold, insurance automatically triggers benefits. This may include coverage for medical consultations, medication, respiratory equipment, or even temporary relocation during high-risk periods. The result is a proactive system instead of a reactive one.

Reducing Health Risks Before They Become Emergencies

Poor air quality can exacerbate asthma, allergies, and cardiovascular conditions. Instead of waiting for symptoms to escalate, atmospheric insurance focuses on early support. Policyholders receive alerts and preventive care options as soon as local reading worsens. This approach reduces hospital visits, lowers long-term costs, and helps people with sensitive health conditions manage risks more effectively.

Built for Smart Homes and Connected Devices

Smart homes equipped with indoor air sensors, purifiers, and environmental smart monitors integrate seamlessly with this coverage. If indoor air quality drops due to smoke, mold, or chemical leaks, the system notifies the insurer automatically. This can prompt immediate assistance—such as scheduling home inspections, funding filtration upgrades, or covering related medical needs.

Encouraging Healthier, More Informed Living

Atmospheric health coverage helps people build better habits through real-time data. Policyholders become more aware of environmental triggers and can make informed choices about outdoor activity, travel, or home air management. Over time, this awareness leads to healthier behavior and reduced long-term health risks associated with pollution.

Conclusion

Atmospheric health coverage represents a major shift in how insurance supports well-being. By using real-time sensor data to activate protection, it moves beyond crisis response and into prevention. As environmental challenges continue to rise, this proactive model offers a smarter, safer way to live—empowering people to stay healthy even when the air around them isn’t.

Rent-Boost Cards: Turning Monthly Rent into Automated Credit Score Growth

For many people, rent is their largest monthly expense—yet it traditionally hasn’t counted toward building a credit history. Rent-boost cards are changing that. These modern financial tools turn routine rent payments into credit-building opportunities, helping renters strengthen their scores without taking on debt. By converting existing obligations into meaningful credit activity, rent-boost cards make score growth more accessible than ever.

Transforming Rent into Reported Credit

Rent-boost cards work by processing your monthly rent payment and reporting it to major credit bureaus as an on-time transaction. Since payment history is the most important factor in credit scoring, consistently paying rent through these systems adds a steady stream of positive data. This transforms a bill you already pay into a valuable tool for long-term financial growth.

Helping Consumers Without Additional Debt

Unlike traditional credit cards, rent-boost cards don’t require you to borrow money or carry a balance. They simply route rent through a secure payment system and mark it as an on-time payment on your credit file. This makes them ideal for renters who want to improve or establish credit without taking on unnecessary loans or revolving debt.

Smoothing Score Fluctuations Through Predictable Reporting

Because rent is paid at the same time every month, it creates consistent, predictable positive entries in your credit history. This reduces score volatility and provides ongoing reinforcement for your credit profile. Over time, this steadiness helps you qualify for better financial products, lower interest rates, and more favorable terms.

Building Credit for the Long Term

Many renters miss out on years of credit history simply because payments weren’t recorded. Rent-boost cards close that gap. They ensure that your largest regular payment becomes part of your financial story, helping you build a stronger foundation for mortgages, auto loans, and future goals. It’s one of the simplest, lowest-risk ways to turn everyday spending into score growth.

Conclusion

Rent-boost cards offer a powerful opportunity for renters to build credit without altering their spending habits. By converting monthly rent into reported payment activity, they help create a steady path toward a healthier credit score. With consistent use and on-time payments, rent-boost cards transform a routine expense into long-term financial progress.

How to Build Credit Without Using Credit Cards

Building credit is an essential part of financial independence, but many people prefer not to rely on credit cards to do it. Whether you’re avoiding debt or simply want alternative methods, the good news is that there are several effective ways to establish and grow a strong credit profile without ever swiping a card. By using tools, services, and smart everyday financial habits, anyone can create a reliable credit foundation that supports future goals like renting an apartment, buying a car, or securing low-interest loans.

Using Utility and Rent Payments to Strengthen Your Credit

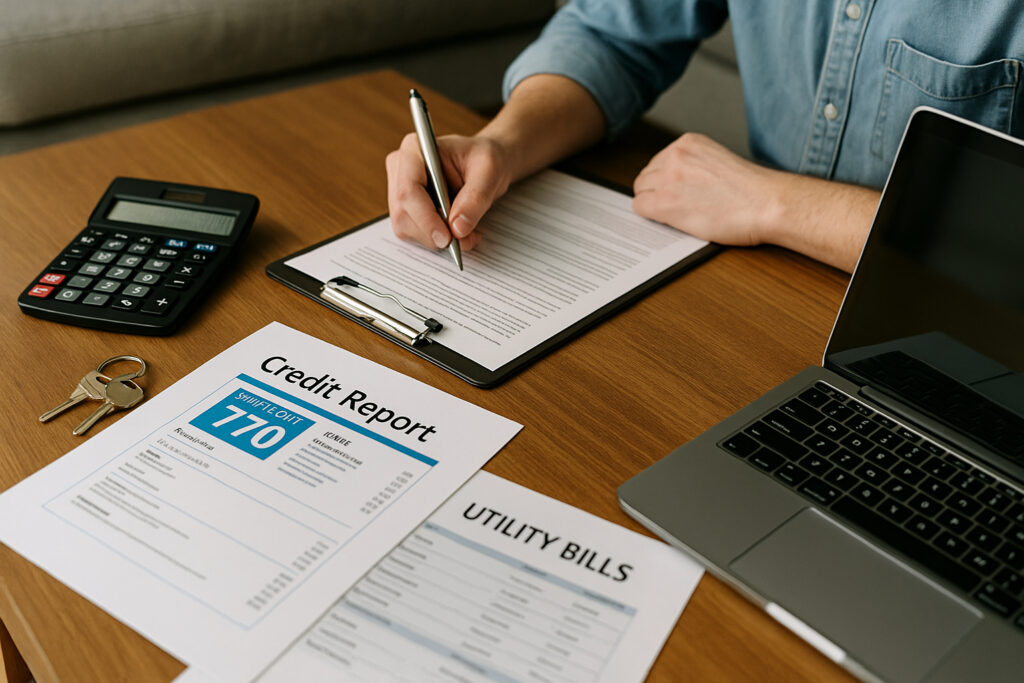
One of the simplest ways to start building credit is by reporting payments you already make each month. Services now allow rent, electricity, water, internet, and even streaming payments to be added to your credit file. These routine bills demonstrate consistency and financial responsibility, which credit agencies value. When these payments appear on your credit report, they help paint a clearer picture of your reliability—even without traditional credit accounts.

Applying for a Credit-Builder Loan

A credit-builder loan is designed specifically for people who want to establish credit from scratch. Instead of receiving the money upfront, the loan amount is held in a secured account while you make small monthly payments. Once the loan is paid off, you receive the funds, and your successful payment history gets reported to credit bureaus. This method offers a safe way to build credit without the temptation to overspend.

Becoming an Authorized User on a Trusted Account

If a family member or close friend has a strong credit history, you can ask to be added as an authorized user on their account. You don’t need to use the card—or even have access to it—to benefit. As long as they maintain good payment habits, their positive history can reflect on your credit report. This strategy is especially helpful for young adults or those rebuilding their financial standing, though it requires trust and open communication.

Managing Installment Payments Responsibly

Loans such as student loans, auto loans, and personal loans can all support your credit profile when handled responsibly. Making on-time payments consistently sends a strong signal to lenders that you are financially dependable. Even if you’re paying off a small loan, maintaining a perfect track record can significantly improve your credit health over time.

Using Reporting Services and Financial Apps

Modern financial tools now offer ways to track your credit, automate payments, and ensure bills are always paid on time. Some apps can submit eligible payments directly to the credit bureaus, while others help monitor your score and offer guidance on improving it. These digital resources help you stay organized and avoid missed or late payments, which can negatively impact your progress.

Conclusion

Building credit without credit cards is completely achievable with the right strategies. By reporting everyday payments, exploring credit-builder loans, or leveraging responsible installment accounts, you can gradually create a solid financial reputation. With patience, consistency, and smart habits, your credit can grow stronger—without ever relying on a traditional credit card.

Micro-Medical Riders: Coverage for Single Conditions Like Migraines or Allergies

Health insurance has traditionally focused on broad medical coverage, but many people struggle with specific recurring conditions that aren’t fully addressed by standard plans. Micro-medical riders are changing that. These add-on insurance options provide targeted coverage for single health issues such as migraines, allergies, sinusitis, or chronic skin conditions. By focusing on one condition at a time, they deliver affordable, efficient protection without requiring a full overhaul of an insurance plan.

Focused Protection for Recurring Conditions

Many individuals deal with a single recurring health problem that demands regular treatment. For conditions like migraines or seasonal allergies, the cost of routine care—doctor visits, tests, or medications—can add up quickly. Micro-medical riders step in by offering dedicated coverage for that one condition, reducing out-of-pocket expenses and creating a predictable and manageable approach to care.

Lower Costs Without Full Policy Upgrades

Instead of buying a more expensive comprehensive insurance plan, micro-medical riders allow people to enhance their existing coverage with focused benefits. This makes them ideal for families or individuals who have stable overall health but need help managing one persistent issue. It’s a cost-effective strategy for getting meaningful coverage without paying for services they don’t need.

Encouraging Early Treatment and Consistency

When people know their condition is covered affordably, they are more likely to seek early care rather than wait for symptoms to worsen. This proactive approach helps prevent escalated costs and complications. Whether it’s regular medication for allergies or periodic assessments for migraines, micro-medical riders support consistent treatment, which improves long-term health outcomes.

Designed for Today’s Personalized Healthcare

Micro-medical riders reflect a shift toward more personalized insurance solutions. People want coverage that aligns with their actual needs, not generic plans built for everyone. By allowing policyholders to choose riders for the conditions most relevant to them, insurers create flexible and responsive options that blend convenience with affordability.

Conclusion

Micro-medical riders offer a smart, targeted way to manage recurring health concerns without overspending on broad coverage. By focusing on single conditions—like migraines or allergies—these add-ons help individuals stay healthy, reduce unpredictable costs, and personalize their insurance experience. As healthcare becomes more individualized, micro-medical riders are emerging as an essential tool for efficient and practical protection.

Why Usage-Based Policies Are the Future of Auto Insurance

Auto insurance is undergoing a major shift, and usage-based policies are quickly becoming the future of the industry. Instead of relying on broad assumptions about drivers, vehicles, or demographics, insurers now use real driving data to personalize pricing. This modern approach rewards safer habits, gives drivers more control over their premiums, and builds a smarter, more transparent insurance experience. With technology playing a central role in mobility, usage-based coverage is transforming how people think about car insurance.

Paying Based on How You Drive

Traditional auto insurance calculates rates using factors like age, location, and historical claims. Usage-based insurance (UBI) changes the game by evaluating how a person actually drives. Small telematics devices or smartphone apps track behaviors such as speed, braking, cornering, and mileage. Safer driving leads to better pricing, making the system fairer and more personalized. Drivers who commute less or practice cautious habits benefit the most from these flexible models.

Saving Costs for Low-Mileage Drivers

Many drivers no longer travel long distances every day. Hybrid work schedules, remote jobs, and lifestyle changes have reduced annual mileage for millions of people. Usage-based policies are ideal for these situations because they adjust premiums based on actual travel. People who drive less pay less, making coverage more affordable for students, retirees, remote workers, and occasional drivers.

Increasing Transparency Through Real Data

Usage-based insurance brings greater transparency to the pricing process. Instead of wondering why premiums increased, drivers receive clear feedback based on their driving habits. Some apps even offer real-time scorecards, tips, and route insights to help drivers improve their behavior. This level of visibility builds trust and helps users feel more in control of their insurance experience.

Encouraging Safer Roads

Because UBI programs reward responsible driving, they create a natural motivation for drivers to adopt safer habits. Reduced speeding, smoother braking, and consistent focus behind the wheel can lower accident risks. As more people shift to usage-based policies, improved driving behaviors can lead to safer roads overall—benefiting both drivers and communities.

Supporting the Future of Mobility

As vehicles become more connected, the demand for smarter, data-driven insurance grows. Usage-based models align perfectly with electric vehicles, car-sharing platforms, and autonomous features. They provide insurers with deeper insights and help drivers stay informed in a rapidly evolving mobility ecosystem. This adaptability is one of the key reasons why UBI is becoming central to the insurance industry’s future.

Conclusion

Usage-based auto insurance offers fairness, flexibility, and transparency that traditional models can’t match. By rewarding safer habits, reducing costs for low-mileage drivers, and using real data to guide pricing, these policies represent the next generation of auto coverage. As technology advances, usage-based insurance will continue to reshape how drivers protect themselves on the road.