Choosing Supplemental Insurance That Matches Everyday Needs

Supplemental insurance can close gaps your primary plan leaves open, but it’s not one-size-fits-all. Start by listing the services and out-of-pocket costs you encounter most often, such as prescription drugs, dental visits, or vision care. Knowing those everyday patterns helps you compare plans on the benefits that matter, rather than on flashy extras you’ll never use. This short checklist approach keeps choices practical and budgets steady.

Identify the real gaps in your base coverage

Begin with a careful review of your main policy to see what’s excluded or limited. Look for common shortfalls like deductibles, coinsurance, skilled nursing limits, and prescription tiers that could trigger surprises. Pay attention to whether certain providers or treatments require prior authorization or sit on a different coverage tier. This foundation clarifies which supplemental benefits would actually reduce your routine costs.

Once you know the gaps, you can ignore irrelevant add-ons and focus on value. That perspective prevents overlap and saves premiums over time.

Match benefits to likely expenses, not hypotheticals

Estimate your annual use of services—how often you fill prescriptions, see specialists, or need rehabilitation. If prescriptions dominate your out-of-pocket spending, a plan with strong drug coverage and predictable copays will matter more than enhanced dental. For someone with frequent therapy or home health needs, look for supplemental riders that lower coinsurance for those services. Choose benefits that reduce recurring costs rather than those that only help in rare, high-cost situations.

Prioritizing predictable savings makes coverage easier to evaluate and compare. It also helps keep premium increases in perspective.

Consider cost, flexibility, and provider access together

Premium is only one piece of the puzzle; balance it against potential savings and network limitations. A low-premium plan that forces you to change doctors or pay higher copays may not be worth it. Check whether supplemental plans coordinate smoothly with your existing providers and whether they require referrals. Flexibility and continuity of care often deliver better value than small premium differences.

Read the fine print on renewability, exclusions, and guaranteed issue periods so you won’t be locked into unexpected gaps later. These terms affect long-term affordability and access.

Conclusion

Focus on the benefits you actually use and compare how each plan lowers those specific costs. Balance premium with provider access and predictable savings to avoid unpleasant surprises. A targeted approach keeps coverage useful and affordable over time.
Building a Clear Backup Plan for Retirement Health Costs

Retirement brings more predictable routines but less tolerance for surprise medical bills. A clear backup plan helps you cover what primary insurance does not — from copays to services often excluded from base plans. Putting simple steps in place now reduces stress later and keeps choices flexible as needs change. This short guide outlines practical moves to protect your health and your savings without overcomplicating decisions.

Why a backup plan matters

Primary retirement health coverage reduces many costs but usually leaves holes: deductibles, specialist fees, and non-covered services can still add up quickly. A backup plan acts like a tether — keeping unexpected out-of-pocket expenses from derailing a monthly budget or emergency fund. It also lets you pick comfort choices such as private rooms, preferred providers, or quicker access to particular services. Treating backup coverage as part of your household budget, not a luxury, makes trade-offs easier to evaluate.

Start by mapping how often you use healthcare each year and which bills caused the biggest surprises. That snapshot will show whether you need a modest safety cushion or broader supplemental coverage. Revisit that map annually or after any health change.

Common gaps in retirement health coverage

Several predictable gaps crop up for retirees: limited dental and vision benefits, higher prescription copays, and long-term care costs that insurers often exclude. Routine services that feel small — like hearing aids or mobility aids — can become significant expenses over time. Travel for specialty care and short-term rehabilitation stays are other budget risks many overlook. Identifying these weak spots early helps you decide which add-ons are worth the premium.

  • Dental, vision, and hearing support
  • Prescription drug coverage gaps
  • Long-term care and in-home services

Once you list likely gaps, prioritize them by cost and frequency. Focus first on the items that could blow a year’s budget if they occur.

Practical steps to build your backup

Begin with a liquid emergency fund sized to cover several months of medical-related expenses. If you prefer insurance to savings, compare supplemental policies that specifically target your highest-risk gaps. Consider short-term or limited-benefit plans for episodic needs and look closely at exclusions, waiting periods, and annual maximums. Use plan comparison tools or a planner to line up costs side-by-side rather than relying on premiums alone.

Coordinate benefits so you aren’t paying twice for overlapping coverage. Small adjustments — raising a deductible to lower premiums or choosing a partial benefit rider — can free up money for other priorities.

Choosing sensible additions without overpaying

A sensible addition addresses a clear need, not a hypothetical fear. Ask three practical questions: How often will I use this? What is the realistic cost if I don’t have it? Is there a cheaper alternative, like a health savings buffer or targeted riders? Avoid broad policies with many rarely used benefits when a focused supplement will do.

Shop during open enrollment windows but don’t wait for a crisis to decide. Small, timely adjustments make a backup plan affordable and effective.

Conclusion

Build your backup plan around real risks and realistic costs, not marketing promises. Keep a mix of liquid savings and targeted supplements so you can adapt as circumstances change. Regular check-ins ensure the plan stays useful and cost-effective.

Practical Choices to Improve Your Retirement Health Coverage

Choosing supplemental health coverage in retirement feels like a balancing act between comfort and cost. Start by looking at what your main plan already pays for and which services leave you exposed. That clarity makes it easier to decide whether a supplemental policy is a necessity or an added luxury. Read on for concrete steps to make choices that fit both your health outlook and your budget.

Know the gaps your primary plan leaves

Your base insurance may cover hospital stays and major procedures but not the routine or emerging costs that add up over time. Prescription drugs, dental work, vision care, and extended home health services are common shortfalls. List the services you and your spouse use most often and compare that list to plan summaries. This focused inventory points you to the types of supplemental coverages that would actually lower your out-of-pocket risk.

Don’t assume every rider or add-on is helpful; some overlap with existing benefits. A narrow, well-chosen supplement often beats a broad policy with needless extras. Keep the needs-first mindset as you shop.

Prioritize the benefits that matter most

Once you know the gaps, rank them by likely cost and frequency. High-frequency, moderate-cost needs like prescriptions or dental exams often justify coverage more readily than rare, high-cost events. Think about your health trajectory: chronic conditions increase the value of predictable coverage, while generally healthy people might prefer savings over comprehensive riders. That ranking helps you avoid paying for benefits you’ll seldom use.

  • Prescription drug coverage — high priority for chronic medications.
  • Dental and vision — often excluded but used frequently.
  • Long-term care or home health riders — consider if family support is limited.

Use that prioritized list to filter plans quickly instead of comparing every feature. Filtering saves time and reduces impulse choices.

Compare costs beyond the premium

Monthly premiums are easy to spot, but the real cost picture includes deductibles, copays, and coverage limits. Check annual maximums, waiting periods, and exclusions that could leave you vulnerable. Run through a few realistic scenarios — a routine year, a year with higher medication needs, and a year with a hospitalization — to see how each plan performs. That scenario testing exposes surprises a premium-only comparison will miss.

Also review provider networks and prior authorization rules to avoid service denials. A lower premium is pointless if the plan denies the care you actually need.

Shop timing, rules, and practical checks

Open enrollment and special enrollment periods determine when you can buy or change supplemental plans, and penalties or medical underwriting may apply outside those windows. Gather plan documents, ask specific questions about exclusions, and get confirmations in writing. If possible, compare at least three carriers and read policy summaries side by side to spot critical differences.

Finally, check customer service reputation and claims turnaround; responsiveness matters when you need care. A policy that pays claims reliably will reduce stress and unexpected bills.

Conclusion

Start with a clear list of what your main plan doesn’t cover and rank gaps by likely cost and frequency. Compare total costs and real-world scenarios, not just premiums, and confirm timing and underwriting rules before you buy. Thoughtful, needs-focused choices will give you coverage that protects your wallet and your health without paying for what you won’t use.

Which Supplemental Benefits Save You the Most Money?

Deciding which supplemental insurance benefits are worth the cost can feel overwhelming.
Start by looking honestly at what you use most and what would be expensive without coverage.
Small monthly premiums add up, but so can one unexpected hospital bill or long prescription run.
This piece walks through practical ways to spot the benefits that likely deliver the biggest savings.

Start with your likely expenses

Look at the care you receive today and what is reasonably likely in the next few years. If you take several prescription medications, drug coverage usually saves more than routine visit benefits. For people who rarely see specialists, vision or dental riders may be lower priority. Estimating one or two high-cost scenarios helps you weigh premium cost against potential out-of-pocket exposure.

Build a realistic list of services you expect to use and their typical prices without insurance. That comparison makes it easier to see where a benefit pays for itself quickly. Keep the list and review it each enrollment period.

Compare benefits, not just premiums

Two plans with similar monthly costs can differ greatly in what they actually pay. Examine limits, copays, annual caps, and whether the plan has waiting periods for services like dental or hearing aids. Also check whether the plan requires a specific provider network or preauthorization for expensive treatments.

  • Prescription drug tiers and true out-of-pocket costs
  • Annual maximums on dental and vision benefits
  • Coverage for outpatient therapies or home health care

Look for benefits that close a real financial gap rather than adding coverage you already have. A clear side-by-side comparison prevents surprises later.

Watch for coordination and exclusions

Understand how a supplemental plan coordinates with your primary coverage. Some plans fill deductibles and copays; others pay only after the primary insurer. Exclusions and caps can make an appealing-sounding benefit nearly useless in a major claim.

Ask for concrete examples from the insurer showing how a typical claim would be paid. Those examples reveal whether the benefit actually reduces your likely expenses or just overlaps existing coverage.

When to buy, drop, or adjust a plan

Timing matters: enroll when your health needs change or during open enrollment windows to avoid gaps. If a benefit went unused for several years, consider dropping it and reallocating funds to more likely risks. Conversely, if a diagnosis increases your expected costs, adding targeted coverage can be economical even with a higher premium.

Small annual adjustments can keep your insurance aligned with reality and budget. Schedule a yearly review to confirm priorities and prices still match your needs.

Conclusion

Choose benefits that reduce predictable, high-cost exposures rather than those that sound appealing.
Compare real claim examples and coordination rules, not only monthly premiums.
A short yearly review will keep your supplemental coverage delivering value.

When Supplemental Coverage Becomes Worth the Cost

Deciding whether to add a supplemental policy is less about fear and more about arithmetic and habits. Look past headlines and focus on the specific services your primary plan limits or leaves out. Think about the care you already use, how often you travel, and which bills would hurt your monthly budget. A few deliberate comparisons usually reveal whether extra coverage will pay off or just add another premium.

Know the gaps in your base plan

Primary health plans often cover core services but leave predictable gaps that matter to individuals. Common shortfalls include dental work, routine vision care, hearing aids, outpatient prescription costs, and long-term care support. Understanding these gaps in dollar terms — estimated annual out-of-pocket costs — makes it easier to judge the value of a supplemental policy. Don’t guess: request a benefits summary and recent claims history when possible.

  • List routine expenses you currently pay out of pocket.
  • Estimate one-off or uncommon costs you could realistically face.
  • Check whether the base plan limits brand-name drugs or specific therapies.

Once you’ve mapped likely expenses, compare them to the supplemental premiums and any waiting periods. If premiums add up to more than the protection they provide, consider carving out only the benefits you really need.

Match benefits to your health and habits

Age alone shouldn’t dictate coverage choices; your medical history and daily life should. If you visit specialists often or use several prescriptions, prioritize plans that lower copays and prescription gaps. Frequent travelers might value emergency overseas benefits more than expanded local dental coverage. Likewise, if family history points to long-term care needs, look for plans that include or attach riders for assisted living or home health support.

Tailoring benefits avoids paying for coverage you’ll rarely use and reduces the chance of surprise bills when you do need care. Small adjustments can change a supplemental plan from unnecessary to genuinely useful.

Compare price, networks and claims performance

Price matters, but so does how a plan pays claims and which providers are in-network. A cheaper premium means little if reimbursements are slow or a preferred doctor is out of network. Read policy language on caps, exclusions, and preexisting condition rules. Ask insurers about average claim turnaround times and whether they offer direct billing with major providers.

Balance monthly cost with realistic benefits and service quality rather than chasing the lowest premium. A modestly higher premium that reliably covers a big expense can be the better financial choice.

Conclusion

Supplemental insurance is worth considering when it fills predictable, meaningful gaps in your primary coverage. Compare expected out-of-pocket costs with premiums and prioritize benefits that match your health needs and lifestyle. Make choices based on clear numbers and practical trade-offs rather than sales pitches.

Five Things to Check Before Buying Supplemental Insurance

Supplemental insurance can fill the gaps left by a primary plan, but not every add-on is worth the premium. Start by identifying routine costs and exposures you already pay out of pocket. A clear, focused checklist makes it easier to compare what different policies actually cover. This piece walks through five practical checks to help you avoid surprises and choose coverage that fits everyday life.

Start with the gaps your main plan leaves

Before shopping for extras, list the services your primary coverage either limits or excludes. Look at copays, deductibles, and whether common needs—like urgent care, mental health visits, or durable medical equipment—have high out-of-pocket costs. Understanding these gaps prevents buying redundant coverage that only overlaps existing benefits. That clarity narrows your choices and keeps premiums targeted to real needs.

Once you document those gaps, prioritize them by frequency and cost. Frequent low-cost needs and rare high-cost events should be weighed differently. This helps you decide whether to insure for predictable expenses or rare catastrophes.

Match benefits to likely services

Not all supplemental policies are created equal: some focus on dental and vision, others on hospital indemnity or prescription drug gaps. Choose benefits that reflect your health patterns, current prescriptions, and anticipated checkups. Think seasonally too—if hearing or mobility supports are likely, look for specific riders rather than generic coverage. A narrowly targeted plan can offer more useful protection for less money.

  • Dental or vision for regular, predictable care.
  • Hospital or critical-illness riders for high-cost events.
  • Prescription gap plans if you regularly hit coverage limits.

Compare plans by the same benefit type rather than across types. That makes apples-to-apples comparisons simpler and highlights real differences in payouts and caps.

Compare costs, limits, and exclusions

Premiums are only part of the price; inspect limits, waiting periods, and exclusions closely. A low monthly cost can come with long waiting periods or benefit caps that render the plan ineffective when you need it most. Also watch for exclusions tied to preexisting conditions or specific treatments. Small print matters: look for lifetime or annual maximums and how benefits are calculated.

Ask for sample claim scenarios from providers to see how the math works. That practical example often reveals where value is and where gaps remain.

Policy details and practical steps

Before you commit, confirm provider networks, claims filing timelines, and customer service options. Check whether you can bundle plans for a discount and whether there are guaranteed renewability clauses. Keep a one-page summary of key facts—premium, deductible, maximums, and contact info—for easy reference during open enrollment or renewals.

Policies change, so review annually and after any health or financial change. Staying proactive helps you avoid paying for unused benefits or being underinsured at a critical time.

Conclusion

Focus on the real gaps in your primary coverage and match benefits to likely needs. Compare costs against limits, waiting periods, and exclusions before buying. A simple checklist and yearly review will keep your supplemental coverage useful and affordable.

A Simple Plan to Identify Gaps in Health Coverage

Insurance stacks can feel dense and uncertain; small gaps lead to big bills.
Before renewal or during life changes, a quick check can prevent surprises.
This short plan shows practical steps you can run through in an hour or two.
No jargon, no pressure—just clear actions to reveal where coverage falls short.

Inventory what you already have

Gather every ID card, policy document and recent explanation of benefits (EOB). Read the summary pages: look for coverage limits, waiting periods, and excluded services. Note any riders, such as foreign travel or home health benefits, and the effective and renewal dates. A clear snapshot of what you already pay for makes gaps easier to spot.

Put this information in one place—a folder, spreadsheet or photo album on your phone. Having it ready saves time when you call a provider or compare plans during open enrollment.

Compare common gaps to likely needs

Think about the care you use most and what could happen next year: routine prescriptions, specialist visits, or a planned procedure. Check whether your plan covers dental, vision, hearing aids, durable medical equipment, and long-term care services—these are frequent blind spots. Also confirm prescription tiers and whether preferred pharmacies or mail-order options apply. Don’t forget coverage limits for durable equipment and home health visits.

  • Dental and vision services
  • Prescription drug tiers and prior authorization rules
  • Skilled nursing, home health, and long-term care options
  • Out-of-network emergency and specialist access

Match the list to your likely needs and mark anything that could leave you exposed financially. Identifying just two or three real gaps gives you leverage when shopping for add-ons or riders.

Run a short cost test

Estimate a realistic year: count your normal visits, meds, and one or two higher-cost events such as a hospital stay. Calculate what you would pay with current deductibles, copays, and maximum out-of-pocket limits. Compare that to the price of a supplemental policy or a different plan to see whether extra coverage reduces risk or just adds cost.

Be practical: focus on likely scenarios rather than worst-case fantasies, and use the numbers to prioritize which gaps to close. If a small rider removes most of your exposure, it may be worth the premium.

Conclusion

Do this quick review annually and after any major life change.
A short, focused check will reveal the most important coverage gaps.
Addressing one or two gaps often provides the most protection for the least cost.

Adjusting Supplemental Insurance When Needs and Budgets Change

Facing a change in income or health needs doesn’t mean you have to accept surprise medical bills. Small, deliberate adjustments to your supplemental insurance can protect savings without leaving you exposed. This piece explains practical steps to review your existing policies, cut unnecessary costs, and keep the coverage that truly matters. You can approach the process one decision at a time and still come out ahead.

Start with an honest coverage audit

Begin by listing every policy you carry and the benefits each provides. Look beyond the premium: note deductibles, coinsurance, caps on benefits, and whether items like prescription drugs or dental care are included. Compare those details to the health services you actually use in a typical year. An audit makes it easier to spot duplicate coverage or benefits you pay for but rarely use.

  • Record annual premiums and out-of-pocket maximums.
  • Mark services you used in the past 12 months.
  • Highlight gaps like vision, dental, or chronic-condition support.

With clear numbers in hand, decide which policies reduce financial risk and which are discretionary. That clarity prevents knee-jerk cancellations that can create bigger bills later.

Prioritize benefits that matter now

Not all benefits are equally valuable. If you take several regular prescriptions, a drug rider or gap coverage may be essential even if it raises monthly cost. If you rarely see specialists, consider scaling back on high-premium riders for specialist visits. Factor in likely near-term events — planned surgeries or travel — when weighing options.

Budget decisions should reflect real needs, not worst-case hypotheticals. Keep core protections for hospitalization and chronic treatment, and trim extras that offer limited real-world value.

Shop smart: timing and comparison tactics

Open enrollment windows and life events are the best times to make changes without medical underwriting hassles. Gather quotes from multiple carriers and focus on total annual cost, not just the monthly premium. Read benefit summaries to confirm network restrictions, prior-authorization rules, and excluded conditions.

  • Request sample bills or benefit scenarios from insurers.
  • Ask about riders you can add temporarily for one-off events.

Small differences in wording can change how claims are paid, so use a checklist when comparing plans. A well-timed switch or a short-term rider can save money and preserve protection.

Conclusion

Adjusting supplemental insurance is a practical mix of math and judgment.
Focus on the benefits you use and the risks you can’t afford.
Make changes during enrollment or after life events to avoid surprises.

Practical Choices for Smarter Supplemental Health Coverage

Choosing supplemental health coverage can feel like sorting through a maze of options, premiums, and fine print. Start by clarifying what your base plan already pays for and where it leaves you exposed. Think about the services you use regularly and the expenses that would hurt your budget if they weren’t covered. A clear list of those risks makes the rest of the process far more purposeful.

Begin with realistic expectations about what insurance will do and what it will not. Keep the focus on practical protection rather than trying to eliminate every possible cost.

Start with a clear inventory

Begin by listing the benefits your primary insurance covers and marking the gaps: deductibles, co-payments, long hospital stays, or outpatient services. Include likely near-term needs such as prescription medication, routine dental work, or planned procedures. Knowing the dollar amounts attached to those gaps helps you compare plans like-for-like. This step prevents buying redundant coverage that adds cost without meaningful extra protection.

Documenting recent medical bills and expected expenses makes choices concrete rather than abstract. Keep those notes handy when reviewing quotes or talking to an agent.

Match coverage to likely needs

Not every extra benefit is worth the same to every person; align options with your personal health picture. For example, if prescriptions are your main expense, a plan that offers lower drug co-pays may be more valuable than broader hospitalization benefits. If mobility or dental work looms ahead, prioritize those riders instead. Aim to cover the highest-probability, highest-cost items first.

  • Prescription cost-sharing for chronic meds
  • Hospital indemnity for occasional long stays
  • Dental and vision for planned maintenance

Focus on a small set of priorities to keep premiums reasonable and benefits targeted. That balance is the heart of smart supplemental planning.

Weigh cost against real benefits

Compare annual premiums against the out-of-pocket exposure each plan reduces. A lower premium can be tempting but might leave you facing large bills for a single event. Look at maximum out-of-pocket limits and what triggers full benefits, not just the headline premium. Also consider how a plan coordinates with other insurance rather than overlaps unnecessarily.

Run simple scenarios: what happens if you need a week-long hospital stay or several months of specialty medication. Those quick calculations reveal which plans truly protect your finances.

Watch for exclusions and timing

Read exclusions carefully and note waiting periods, pre-existing condition clauses, and enrollment windows. Some benefits only start after a waiting period or exclude certain services forever, which can make a policy less useful when you need it. Timing matters: missing an enrollment window can mean limited options or higher costs later. Ask clear questions and get answers in writing when a policy detail is important to you.

Keep renewal dates and annual review reminders on your calendar so coverage still fits your needs next year. A small review each season can save surprises down the road.

Conclusion

Practical supplemental coverage begins with a clear list of gaps and likely expenses. Match benefits to those needs, compare real costs against potential savings, and check exclusions and timing carefully. With focused choices and an annual review, you can secure useful protection without paying for what you don’t need.

What Every Shopper Overlooks in Supplemental Insurance Policies

Supplemental insurance can feel like a tangle of fine print and benefit names that sound similar but behave differently.
Many buyers pick a plan because premiums look low or a familiar word appears in the title.
Those simple choices can leave gaps when a claim arrives or a preferred provider isn’t covered.
This piece points out the small items that change how a policy performs when you need it most.

Before you make any switch or add-on, take a moment to look past surface features and understand the mechanics behind them.

Why the fine print matters

Two policies with the same monthly cost can pay out very differently depending on limits, waiting periods, and exclusions. Read the clauses about preexisting conditions, lifetime caps, and what counts as a covered event; they often determine real value more than the headline benefit. Pay attention to how benefits are triggered — some plans require a hospital stay, others pay for outpatient procedures, and that affects whether you’ll see reimbursement. Also note whether inflation or annual adjustments are built in, since fixed-dollar benefits lose buying power over time.

  • Look for definitions of key terms like “disability” or “qualified provider.”
  • Check how long the insurer has to respond to claims and appeals.

Those items won’t be highlighted in marketing, but they control the speed and amount of any payout. A quick scan now saves frustration later.

Commonly overlooked policy items

People often skip details about network rules, coordination with other insurance, and rider exclusions. Network restrictions can force you to use providers who accept the plan, or leave you paying much more out of pocket for out-of-network care. Coordination clauses explain whether the supplemental plan pays before or after your primary coverage, which affects your immediate bills. Riders and add-ons may seem inexpensive until you realize they duplicate benefits you already have elsewhere.

  • Out-of-network penalties and referral requirements.
  • How the policy interacts with employer or government benefits.
  • Whether certain treatments require prior authorization.

Spotting these items ensures the policy fills genuine gaps instead of offering redundant or unusable coverage. It also helps you compare apples to apples.

Checklist to review before you commit

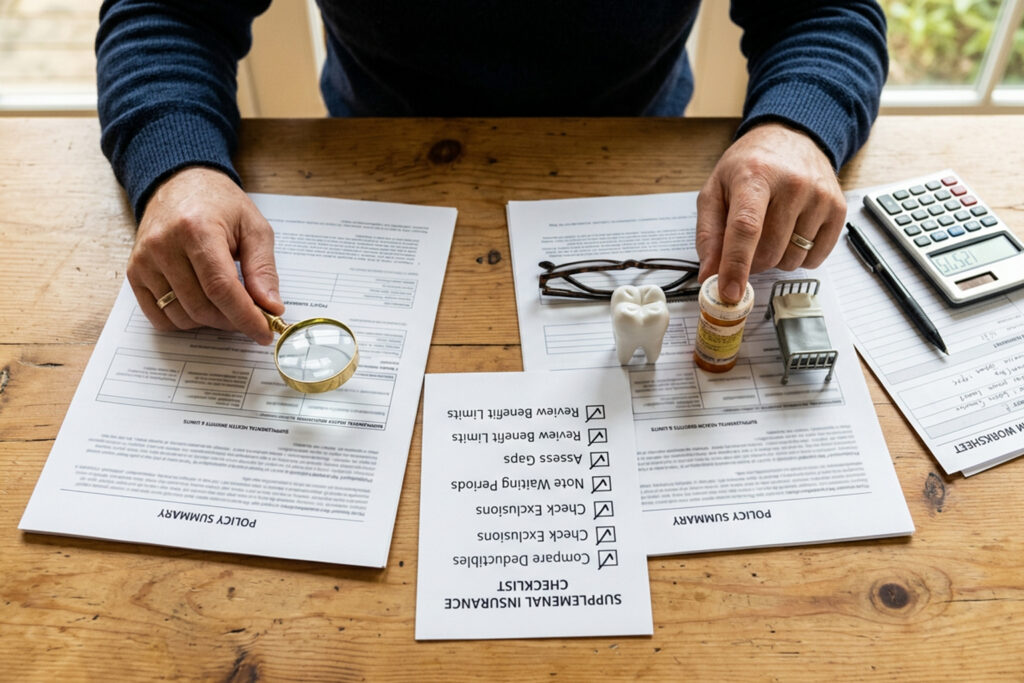
Put a short checklist together: definitions, limits, waiting periods, network rules, coordination, and appeals procedures. Ask for sample claim scenarios from the insurer so you can see how benefits would apply in practice. Confirm any verbal assurances in writing and note the effective date for coverage changes. Finally, compare the total expected annual cost — premiums plus likely out-of-pocket expenses — not just the monthly price.

  • Request a copy of the policy and read highlighted clauses.
  • Call customer service with specific hypothetical claims to test responses.
  • Check review periods and cancellation terms.
  • Make sure any agent promises are included in the contract.

These steps help you choose a plan that behaves as you expect when you claim. They also reduce surprises and make comparisons clearer.

Conclusion

Small policy details often determine whether supplemental coverage actually helps when you need it.
Spend time on definitions, limits, and how the plan works with other coverage before you buy.
A focused review now will protect your finances and give you clearer peace of mind later.