Facing a change in income or health needs doesn’t mean you have to accept surprise medical bills. Small, deliberate adjustments to your supplemental insurance can protect savings without leaving you exposed. This piece explains practical steps to review your existing policies, cut unnecessary costs, and keep the coverage that truly matters. You can approach the process one decision at a time and still come out ahead.
Start with an honest coverage audit
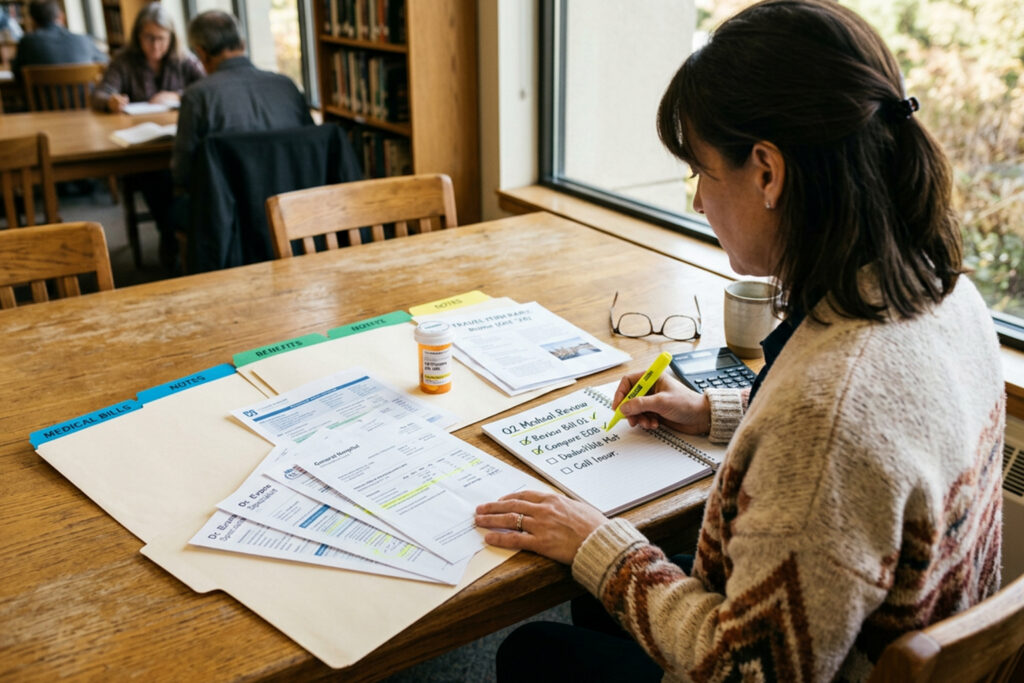
Begin by listing every policy you carry and the benefits each provides. Look beyond the premium: note deductibles, coinsurance, caps on benefits, and whether items like prescription drugs or dental care are included. Compare those details to the health services you actually use in a typical year. An audit makes it easier to spot duplicate coverage or benefits you pay for but rarely use.
- Record annual premiums and out-of-pocket maximums.
- Mark services you used in the past 12 months.
- Highlight gaps like vision, dental, or chronic-condition support.
With clear numbers in hand, decide which policies reduce financial risk and which are discretionary. That clarity prevents knee-jerk cancellations that can create bigger bills later.
Prioritize benefits that matter now
Not all benefits are equally valuable. If you take several regular prescriptions, a drug rider or gap coverage may be essential even if it raises monthly cost. If you rarely see specialists, consider scaling back on high-premium riders for specialist visits. Factor in likely near-term events — planned surgeries or travel — when weighing options.
Budget decisions should reflect real needs, not worst-case hypotheticals. Keep core protections for hospitalization and chronic treatment, and trim extras that offer limited real-world value.
Shop smart: timing and comparison tactics
Open enrollment windows and life events are the best times to make changes without medical underwriting hassles. Gather quotes from multiple carriers and focus on total annual cost, not just the monthly premium. Read benefit summaries to confirm network restrictions, prior-authorization rules, and excluded conditions.
- Request sample bills or benefit scenarios from insurers.
- Ask about riders you can add temporarily for one-off events.
Small differences in wording can change how claims are paid, so use a checklist when comparing plans. A well-timed switch or a short-term rider can save money and preserve protection.
Conclusion
Adjusting supplemental insurance is a practical mix of math and judgment.
Focus on the benefits you use and the risks you can’t afford.
Make changes during enrollment or after life events to avoid surprises.