Credit cards shouldn’t be a last-minute surprise on payday.
A few consistent rules can make them predictable tools instead of unpredictable bills.
This article lays out a compact routine to match cards to paydays, bills and rewards so you spend less time worrying and more time saving.
Follow the steps for a couple of billing cycles and you’ll notice fewer late fees and clearer cash flow.
Set a Simple Card Hierarchy
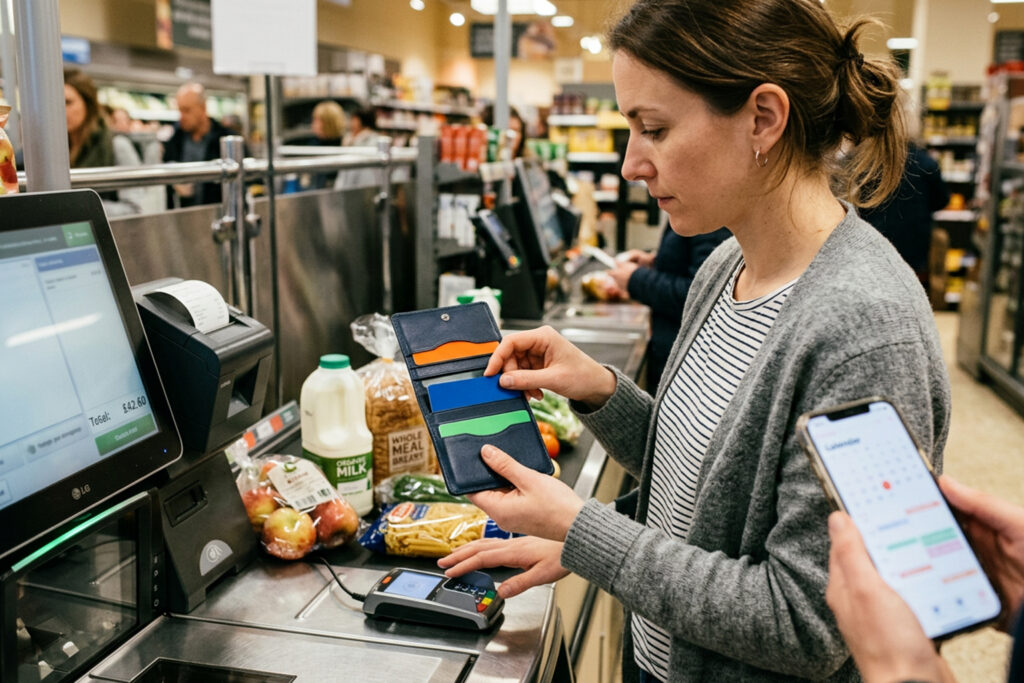
Choose two or three cards and give each a clear purpose: one for monthly bills, one for everyday purchases, and one as an emergency or specialty card. Assigning roles reduces accidental charges on the wrong card and makes it easier to track which balances to pay first. Keep the card used for recurring subscriptions separate so you can monitor and cancel unwanted charges quickly. Treat the emergency card as off-limits unless an unexpected expense genuinely requires it.
- Primary card: rent, utilities, subscriptions.
- Everyday card: groceries, gas, dining categories that match rewards.
- Backup card: travel protections or true emergencies.
With roles defined, automation becomes simpler: set autopay for bills on the primary card and manual payments for the others when useful. The hierarchy also makes it easier to decide which balance to focus on if cash is tight.
Time Purchases Around Billing Cycles
Understanding each card’s statement close date and payment due date gives you two levers: when charges appear on a statement and when you actually need to pay. Charge non-urgent purchases just after the statement close to maximize float, and plan larger buys around paydays so you can clear the balance before interest kicks in. If a card has a promotional 0% period, map larger purchases to that timeline but track the end date carefully. Small timing shifts can free up one or two weeks of cash flow without incurring cost.
Use a calendar or app to display close and due dates side-by-side with your paydays. Those few minutes of planning prevent many common cash-flow scrambles.
Protect Your Cash Flow and Avoid Interest
Pay at least the statement balance each month whenever possible to avoid finance charges and keep utilization low. If you can’t, prioritize high-interest balances and move what you can to a card with a lower rate or a short promotional APR if you qualify. Keep an eye on fees—annual fees can be worth it if the rewards and protections offset them, but they should justify the cost. Regularly check for unauthorized charges and set alerts so small problems don’t become large ones.
Small habits—autopay where safe, alerts for due dates, and a short monthly review—go a long way toward protecting your cash flow. These safeguards keep credit working for you, not against you.
Conclusion
Simple rules and a little calendar planning turn credit cards into predictable financial tools.
Assign roles, time purchases, and protect cash flow with autopay and alerts.
Stick to the routine and your monthly budget will feel steadier and less stressful.