Retirement brings more predictable routines but less tolerance for surprise medical bills. A clear backup plan helps you cover what primary insurance does not — from copays to services often excluded from base plans. Putting simple steps in place now reduces stress later and keeps choices flexible as needs change. This short guide outlines practical moves to protect your health and your savings without overcomplicating decisions.
Why a backup plan matters
Primary retirement health coverage reduces many costs but usually leaves holes: deductibles, specialist fees, and non-covered services can still add up quickly. A backup plan acts like a tether — keeping unexpected out-of-pocket expenses from derailing a monthly budget or emergency fund. It also lets you pick comfort choices such as private rooms, preferred providers, or quicker access to particular services. Treating backup coverage as part of your household budget, not a luxury, makes trade-offs easier to evaluate.
Start by mapping how often you use healthcare each year and which bills caused the biggest surprises. That snapshot will show whether you need a modest safety cushion or broader supplemental coverage. Revisit that map annually or after any health change.
Common gaps in retirement health coverage
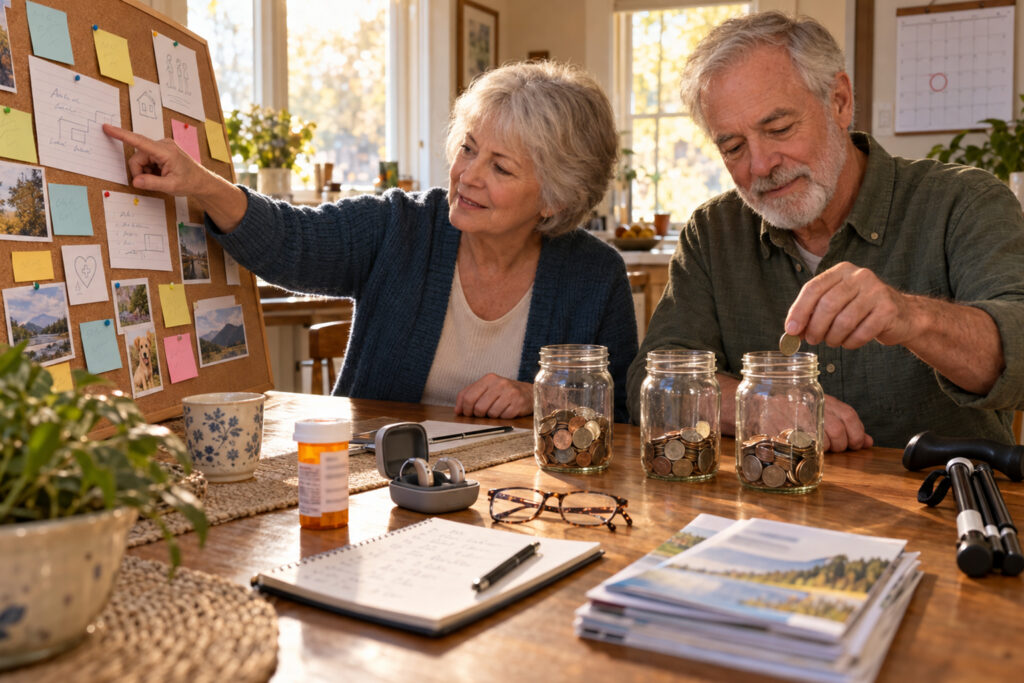
Several predictable gaps crop up for retirees: limited dental and vision benefits, higher prescription copays, and long-term care costs that insurers often exclude. Routine services that feel small — like hearing aids or mobility aids — can become significant expenses over time. Travel for specialty care and short-term rehabilitation stays are other budget risks many overlook. Identifying these weak spots early helps you decide which add-ons are worth the premium.
- Dental, vision, and hearing support
- Prescription drug coverage gaps
- Long-term care and in-home services
Once you list likely gaps, prioritize them by cost and frequency. Focus first on the items that could blow a year’s budget if they occur.
Practical steps to build your backup
Begin with a liquid emergency fund sized to cover several months of medical-related expenses. If you prefer insurance to savings, compare supplemental policies that specifically target your highest-risk gaps. Consider short-term or limited-benefit plans for episodic needs and look closely at exclusions, waiting periods, and annual maximums. Use plan comparison tools or a planner to line up costs side-by-side rather than relying on premiums alone.
Coordinate benefits so you aren’t paying twice for overlapping coverage. Small adjustments — raising a deductible to lower premiums or choosing a partial benefit rider — can free up money for other priorities.
Choosing sensible additions without overpaying
A sensible addition addresses a clear need, not a hypothetical fear. Ask three practical questions: How often will I use this? What is the realistic cost if I don’t have it? Is there a cheaper alternative, like a health savings buffer or targeted riders? Avoid broad policies with many rarely used benefits when a focused supplement will do.
Shop during open enrollment windows but don’t wait for a crisis to decide. Small, timely adjustments make a backup plan affordable and effective.
Conclusion
Build your backup plan around real risks and realistic costs, not marketing promises. Keep a mix of liquid savings and targeted supplements so you can adapt as circumstances change. Regular check-ins ensure the plan stays useful and cost-effective.