Choosing supplemental health coverage in retirement feels like a balancing act between comfort and cost. Start by looking at what your main plan already pays for and which services leave you exposed. That clarity makes it easier to decide whether a supplemental policy is a necessity or an added luxury. Read on for concrete steps to make choices that fit both your health outlook and your budget.
Know the gaps your primary plan leaves
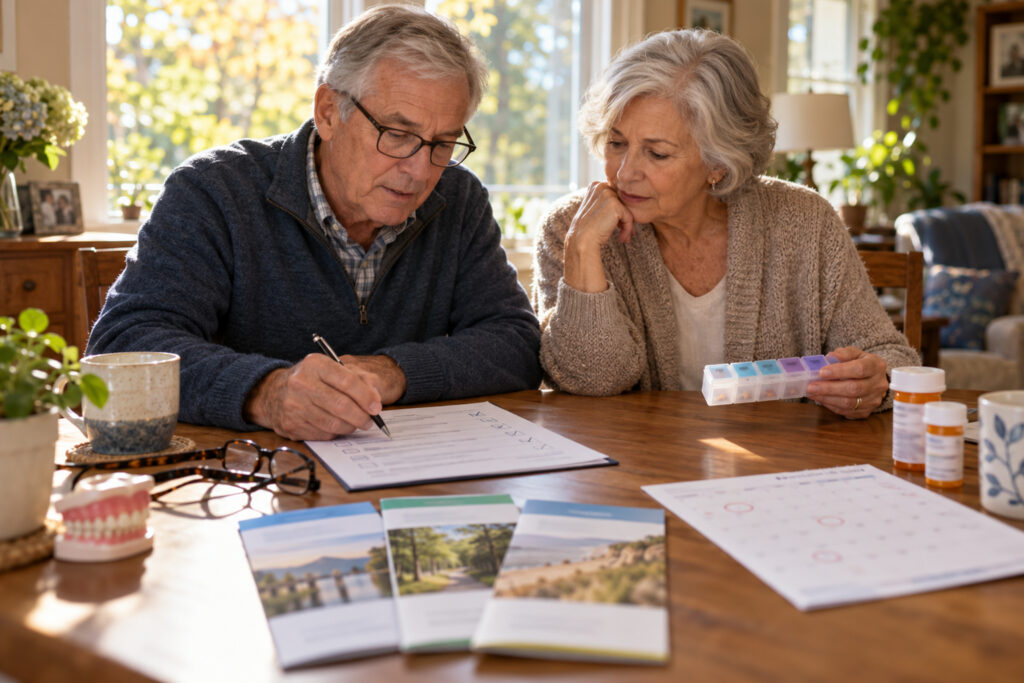
Your base insurance may cover hospital stays and major procedures but not the routine or emerging costs that add up over time. Prescription drugs, dental work, vision care, and extended home health services are common shortfalls. List the services you and your spouse use most often and compare that list to plan summaries. This focused inventory points you to the types of supplemental coverages that would actually lower your out-of-pocket risk.
Don’t assume every rider or add-on is helpful; some overlap with existing benefits. A narrow, well-chosen supplement often beats a broad policy with needless extras. Keep the needs-first mindset as you shop.
Prioritize the benefits that matter most
Once you know the gaps, rank them by likely cost and frequency. High-frequency, moderate-cost needs like prescriptions or dental exams often justify coverage more readily than rare, high-cost events. Think about your health trajectory: chronic conditions increase the value of predictable coverage, while generally healthy people might prefer savings over comprehensive riders. That ranking helps you avoid paying for benefits you’ll seldom use.
- Prescription drug coverage — high priority for chronic medications.
- Dental and vision — often excluded but used frequently.
- Long-term care or home health riders — consider if family support is limited.
Use that prioritized list to filter plans quickly instead of comparing every feature. Filtering saves time and reduces impulse choices.
Compare costs beyond the premium
Monthly premiums are easy to spot, but the real cost picture includes deductibles, copays, and coverage limits. Check annual maximums, waiting periods, and exclusions that could leave you vulnerable. Run through a few realistic scenarios — a routine year, a year with higher medication needs, and a year with a hospitalization — to see how each plan performs. That scenario testing exposes surprises a premium-only comparison will miss.
Also review provider networks and prior authorization rules to avoid service denials. A lower premium is pointless if the plan denies the care you actually need.
Shop timing, rules, and practical checks
Open enrollment and special enrollment periods determine when you can buy or change supplemental plans, and penalties or medical underwriting may apply outside those windows. Gather plan documents, ask specific questions about exclusions, and get confirmations in writing. If possible, compare at least three carriers and read policy summaries side by side to spot critical differences.
Finally, check customer service reputation and claims turnaround; responsiveness matters when you need care. A policy that pays claims reliably will reduce stress and unexpected bills.
Conclusion
Start with a clear list of what your main plan doesn’t cover and rank gaps by likely cost and frequency. Compare total costs and real-world scenarios, not just premiums, and confirm timing and underwriting rules before you buy. Thoughtful, needs-focused choices will give you coverage that protects your wallet and your health without paying for what you won’t use.