Deciding which supplemental insurance benefits are worth the cost can feel overwhelming.
Start by looking honestly at what you use most and what would be expensive without coverage.
Small monthly premiums add up, but so can one unexpected hospital bill or long prescription run.
This piece walks through practical ways to spot the benefits that likely deliver the biggest savings.
Start with your likely expenses
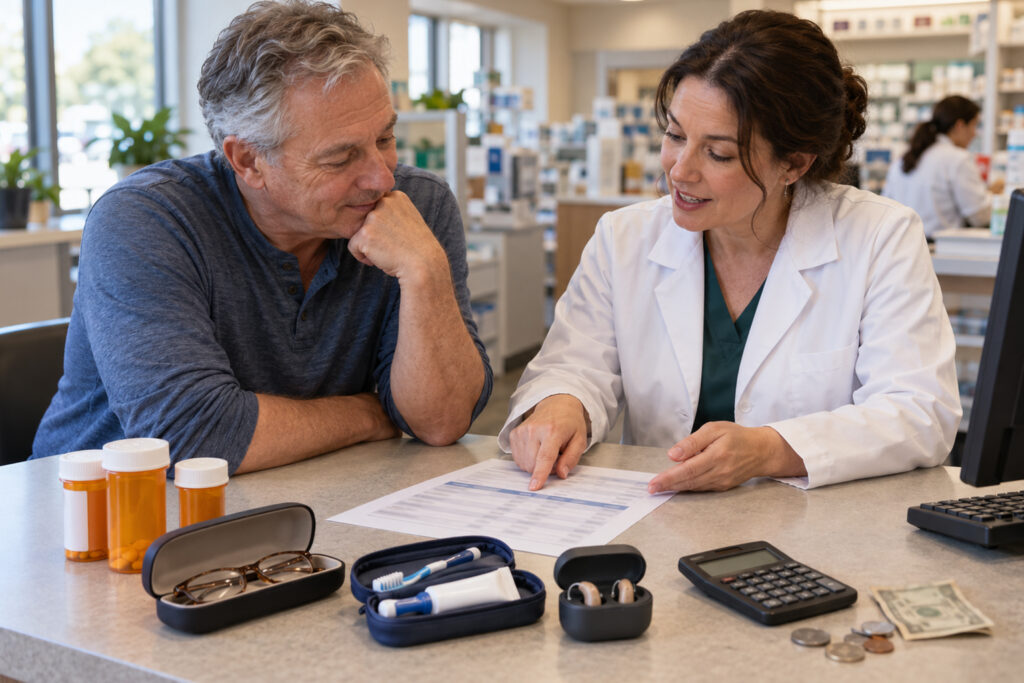
Look at the care you receive today and what is reasonably likely in the next few years. If you take several prescription medications, drug coverage usually saves more than routine visit benefits. For people who rarely see specialists, vision or dental riders may be lower priority. Estimating one or two high-cost scenarios helps you weigh premium cost against potential out-of-pocket exposure.
Build a realistic list of services you expect to use and their typical prices without insurance. That comparison makes it easier to see where a benefit pays for itself quickly. Keep the list and review it each enrollment period.
Compare benefits, not just premiums
Two plans with similar monthly costs can differ greatly in what they actually pay. Examine limits, copays, annual caps, and whether the plan has waiting periods for services like dental or hearing aids. Also check whether the plan requires a specific provider network or preauthorization for expensive treatments.
- Prescription drug tiers and true out-of-pocket costs
- Annual maximums on dental and vision benefits
- Coverage for outpatient therapies or home health care
Look for benefits that close a real financial gap rather than adding coverage you already have. A clear side-by-side comparison prevents surprises later.
Watch for coordination and exclusions
Understand how a supplemental plan coordinates with your primary coverage. Some plans fill deductibles and copays; others pay only after the primary insurer. Exclusions and caps can make an appealing-sounding benefit nearly useless in a major claim.
Ask for concrete examples from the insurer showing how a typical claim would be paid. Those examples reveal whether the benefit actually reduces your likely expenses or just overlaps existing coverage.
When to buy, drop, or adjust a plan
Timing matters: enroll when your health needs change or during open enrollment windows to avoid gaps. If a benefit went unused for several years, consider dropping it and reallocating funds to more likely risks. Conversely, if a diagnosis increases your expected costs, adding targeted coverage can be economical even with a higher premium.
Small annual adjustments can keep your insurance aligned with reality and budget. Schedule a yearly review to confirm priorities and prices still match your needs.
Conclusion
Choose benefits that reduce predictable, high-cost exposures rather than those that sound appealing.
Compare real claim examples and coordination rules, not only monthly premiums.
A short yearly review will keep your supplemental coverage delivering value.