Deciding whether to add a supplemental policy is less about fear and more about arithmetic and habits. Look past headlines and focus on the specific services your primary plan limits or leaves out. Think about the care you already use, how often you travel, and which bills would hurt your monthly budget. A few deliberate comparisons usually reveal whether extra coverage will pay off or just add another premium.
Know the gaps in your base plan
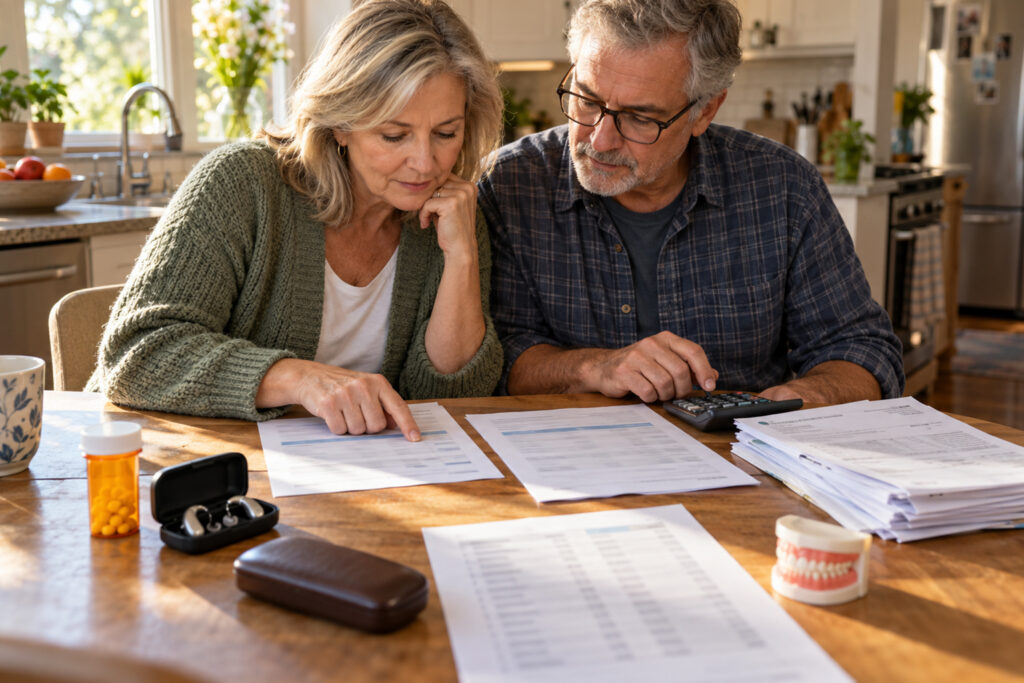
Primary health plans often cover core services but leave predictable gaps that matter to individuals. Common shortfalls include dental work, routine vision care, hearing aids, outpatient prescription costs, and long-term care support. Understanding these gaps in dollar terms — estimated annual out-of-pocket costs — makes it easier to judge the value of a supplemental policy. Don’t guess: request a benefits summary and recent claims history when possible.
- List routine expenses you currently pay out of pocket.
- Estimate one-off or uncommon costs you could realistically face.
- Check whether the base plan limits brand-name drugs or specific therapies.
Once you’ve mapped likely expenses, compare them to the supplemental premiums and any waiting periods. If premiums add up to more than the protection they provide, consider carving out only the benefits you really need.
Match benefits to your health and habits
Age alone shouldn’t dictate coverage choices; your medical history and daily life should. If you visit specialists often or use several prescriptions, prioritize plans that lower copays and prescription gaps. Frequent travelers might value emergency overseas benefits more than expanded local dental coverage. Likewise, if family history points to long-term care needs, look for plans that include or attach riders for assisted living or home health support.
Tailoring benefits avoids paying for coverage you’ll rarely use and reduces the chance of surprise bills when you do need care. Small adjustments can change a supplemental plan from unnecessary to genuinely useful.
Compare price, networks and claims performance
Price matters, but so does how a plan pays claims and which providers are in-network. A cheaper premium means little if reimbursements are slow or a preferred doctor is out of network. Read policy language on caps, exclusions, and preexisting condition rules. Ask insurers about average claim turnaround times and whether they offer direct billing with major providers.
Balance monthly cost with realistic benefits and service quality rather than chasing the lowest premium. A modestly higher premium that reliably covers a big expense can be the better financial choice.
Conclusion
Supplemental insurance is worth considering when it fills predictable, meaningful gaps in your primary coverage. Compare expected out-of-pocket costs with premiums and prioritize benefits that match your health needs and lifestyle. Make choices based on clear numbers and practical trade-offs rather than sales pitches.