Credit cards can feel like tools for convenience or sources of stress, depending on how you use them. A handful of clear, repeatable rules keeps rewards coming without surprise bills. This piece lays out practical habits you can start this month to reduce friction and preserve your cashflow. No jargon, just straightforward steps that fit into a busy life.
Set a clear card hierarchy
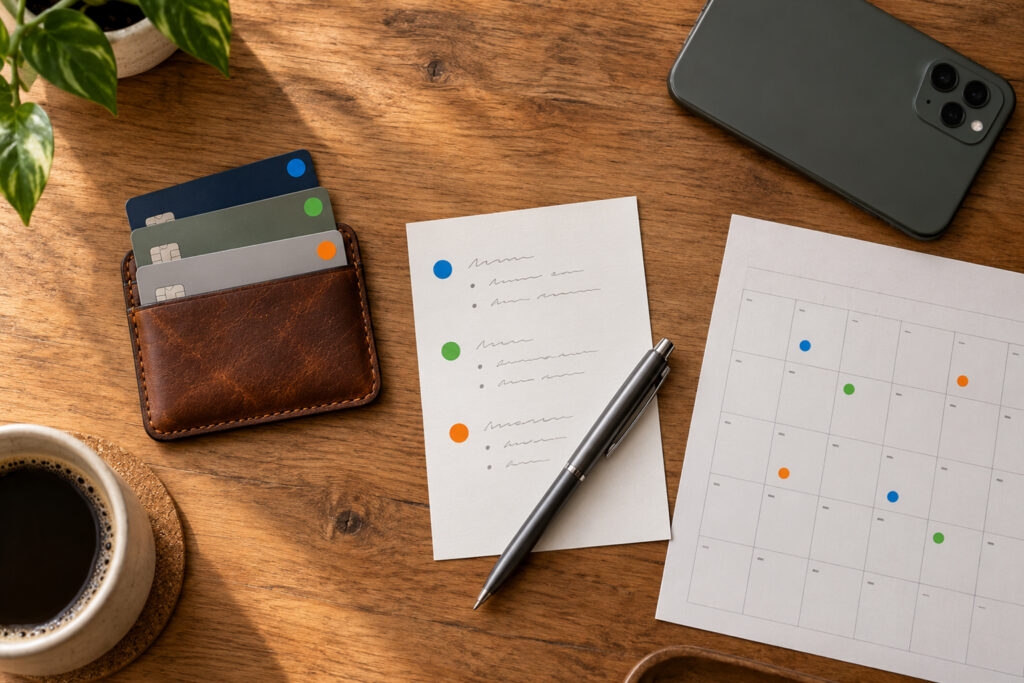
Decide which card is primary, which is for niche spending, and which you keep for emergencies. Your primary card should cover most daily purchases and be the one you pay automatically. Keep one or two secondary cards for specific categories like groceries or travel where they earn more. Closing or sidelining extra cards avoids decision fatigue at checkout and helps you track statements more easily.
Label cards in your phone wallet app and on a one-page cheat sheet if you need to. That small habit reduces last-minute swaps and forgotten balances.
Match cards to recurring spending
Look at regular payments—subscriptions, utilities, grocery runs—and pick the best card for each. Assigning cards to predictable charges makes rewards predictable and simplifies which balances you carry. Use calendar reminders for annual fees and reprioritize cards when reward rates change. A brief quarterly check prevents tiny mismatches from becoming costly habits.
- Everyday purchases: use your highest flat-rate or rotating category card.
- Big recurring bills: put them on a card with strong protection and clear payoff plans.
- Travel or dining: reserve a bonus card for months when you spend more in those categories.
Keeping assignments simple means you can set it and mostly forget it, while still claiming most available rewards.
Lock in a payment and review rhythm
Automate minimums and schedule one weekly or biweekly check to catch unexpected charges. Paying on the statement due date avoids interest and helps you forecast cashflow. Once a month, review high balances and transfers that could trigger fees or higher interest. If something slips, act quickly to dispute errors or adjust your payment plan.
Small, regular scans are far more effective than occasional deep dives. That steady attention keeps surprises off your balance and preserves credit health.
Conclusion
Adopt a simple hierarchy, match cards to predictable spending, and set a steady payment rhythm. These modest habits cut stress and help you keep rewards without extra work. Start with one change this week and build from there.