The Best Time to Pay Your Credit Card Bill

Paying your credit card bill on time is essential for maintaining a strong financial reputation — but when you pay it can be just as important as how much you pay. Understanding billing cycles, statement dates, and due dates can help you save money, improve your credit score, and keep your debt under control.

Understanding the Credit Card Cycle

Every credit card operates on a billing cycle, typically lasting 25–30 days. At the end of the cycle, your lender issues a statement date showing all your transactions and the total balance due. You then have a grace period — usually around 20 days — to pay without interest.

Your payment due date falls at the end of this grace period. Paying your bill before this date helps you avoid late fees and interest. But strategic timing — paying before your statement closes — can actually boost your credit score.

Paying Before the Statement Date

Your credit utilization ratio — the amount of credit you’re using versus your total limit — heavily influences your credit score. If your statement shows a high balance, it can temporarily lower your score even if you pay in full later.

To maintain a low utilization rate (ideally below 30%), try paying down your balance before your statement date, not just before the due date. This ensures the reported balance to credit bureaus reflects responsible spending and repayment behavior.

For example, if your billing cycle ends on the 25th and your due date is the 15th of the next month, making a payment around the 20th helps reduce the amount reported to credit agencies.

Paying Multiple Times a Month

If you frequently use your card for daily expenses, consider making biweekly payments. Splitting payments across the month keeps your balance low, reduces interest, and helps you stay within budget. This approach is especially helpful for freelancers or gig workers with irregular income.

Automate and Monitor Payments

Setting up auto-pay ensures you never miss a due date. You can schedule automatic payments for at least the minimum amount due and make additional manual payments as needed. Combine this with reminders a few days before your statement date to optimize both credit health and cash flow.

Conclusion

The best time to pay your credit card bill is before your statement date — and consistently before your due date. This strategy keeps your credit utilization low, protects your credit score, and saves you from unnecessary interest. With mindful timing and a little planning, your credit card can work for you, not against you.
Types of Credit Cards and Which One Is Right for You

Credit cards have become more than just a convenient payment method — they’re powerful financial tools that can help you build credit, earn rewards, and manage cash flow. However, not all cards are created equal. Understanding the different types of credit cards can help you choose the one that fits your lifestyle and financial goals.

Rewards Credit Cards

Rewards cards allow you to earn points, miles, or cashback on your everyday purchases.

  • Cashback cards give a percentage of your spending back as cash or statement credit. They’re ideal for people who pay off balances in full each month.

  • Travel rewards cards earn points or miles redeemable for flights, hotels, or upgrades. Perfect for frequent travelers.

  • Points-based cards offer flexible redemption options for merchandise, gift cards, or experiences.

These cards often come with higher annual fees but can deliver significant value if used strategically.

Low-Interest and Balance Transfer Cards

If you’re carrying debt or planning a big purchase, a low-interest or balance transfer card might be the best fit.

  • Low-interest cards offer reduced APRs for ongoing purchases.

  • Balance transfer cards allow you to move existing credit card debt to a new card with a 0% introductory APR period, helping you save on interest while you pay down your balance.

These cards are best for individuals focused on debt management or improving their credit utilization.

Secured Credit Cards

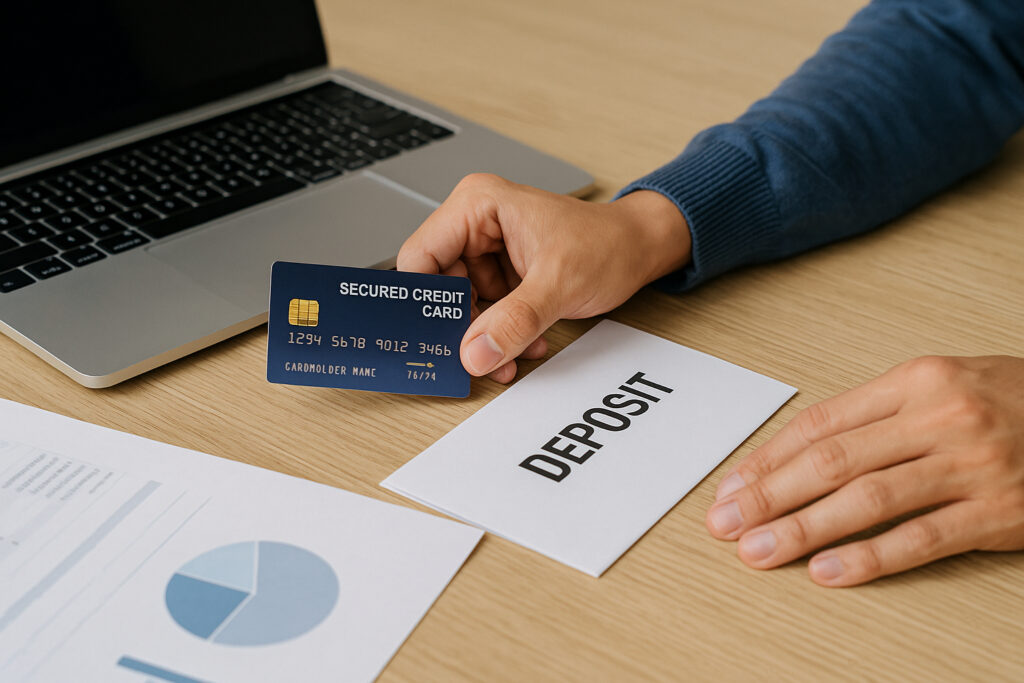
Secured cards are designed for people with limited or poor credit history. They require a refundable security deposit, which typically becomes your credit limit. Responsible use — such as on-time payments and low balances — helps build or rebuild your credit score over time.

These are ideal for students, young adults, or anyone recovering from credit challenges.

Student Credit Cards

Aimed at college students and first-time users, student cards often come with low credit limits and minimal rewards. Their primary purpose is to help beginners establish a credit history responsibly. Many offer benefits like cashback on groceries, books, or streaming services.

Premium and Travel Cards

Premium cards cater to high spenders and frequent travelers, offering perks like airport lounge access, concierge services, and elite hotel status. While they come with steep annual fees, the rewards and travel benefits often outweigh the cost for frequent travelers or business professionals.

Business Credit Cards

Designed for entrepreneurs and small business owners, business cards separate personal and business expenses while earning rewards on travel, office supplies, or advertising. They also help build a business credit profile, which can be useful for future financing.

How to Choose the Right Card

When selecting a credit card, consider:

  • Your financial goals: Are you looking to build credit, earn rewards, or manage debt?

  • Your spending habits: Frequent travelers benefit from rewards cards, while everyday spenders may prefer cashback.

  • Fees and interest rates: Review annual fees, APRs, and penalty charges before applying.

  • Credit score: Premium cards require strong credit, while secured or student cards work better for beginners.

Conclusion

The right credit card isn’t about having the most perks — it’s about choosing one that aligns with your financial habits and helps you achieve your goals. Whether you’re building credit, earning rewards, or managing debt, understanding your options empowers you to use credit wisely and make your finances work for you.

Should You Use a Credit Card for Everyday Purchases?

Credit cards are powerful financial tools — offering convenience, security, and rewards with every swipe. But when used carelessly, they can also lead to debt and unnecessary interest charges. Whether you should use a credit card for everyday expenses depends on how disciplined you are with payments and how well you understand your card’s terms.

The Benefits of Using a Credit Card Daily

1. Convenience and Safety
Carrying a credit card is far safer than handling cash. It’s easier to track expenses digitally and replace a lost card than stolen money. Many cards also offer fraud protection, ensuring you’re not liable for unauthorized charges.

2. Rewards and Cash Back
Everyday spending — groceries, fuel, dining, or utilities — can earn you reward points, cashback, or travel miles. When you pay your balance in full each month, these rewards essentially translate into free money. Over time, they can add up to significant savings or perks.

3. Building a Strong Credit History
Regular use of a credit card, paired with on-time payments, helps build your credit score. A strong score improves your chances of securing loans or mortgages at favorable rates. Even small, consistent purchases can help demonstrate responsible credit behavior.

4. Expense Tracking and Budgeting
Most credit cards provide detailed statements that categorize your spending. This helps identify where your money goes each month and allows you to adjust your budget accordingly.

The Risks of Using a Credit Card for Everyday Spending

1. Overspending Temptation
When swiping feels effortless, it’s easy to lose track of how much you’ve spent. Many people fall into the trap of buy now, worry later, leading to balances they can’t repay in full.

2. Interest and Debt Accumulation
If you don’t pay off your balance each month, interest quickly builds up. Even small everyday purchases can become expensive once interest compounds, especially with cards charging rates above 20%.

3. Fees and Penalties
Late payments, annual fees, or exceeding your credit limit can result in costly penalties. Missing even one payment can hurt your credit score and trigger higher interest rates.

Smart Ways to Use a Credit Card Responsibly

  • Pay in full and on time: Avoid carrying a balance to eliminate interest charges.

  • Set a spending limit: Treat your credit card like a debit card — spend only what you can repay immediately.

  • Use for planned expenses only: Regular bills or groceries are fine; avoid impulsive purchases.

  • Monitor your utilization: Keep your credit usage below 30% of your total limit to maintain a healthy score.

Conclusion

Using a credit card for everyday purchases can be smart — if you manage it wisely. It offers convenience, rewards, and credit-building opportunities, but only if you stay disciplined with payments. The golden rule: treat your credit card as a financial tool, not an invitation to overspend. With responsible use, it can work for you, not against you.
How to Read Your Credit Card Statement

Your credit card statement is more than just a bill — it’s a detailed summary of how you spend, borrow, and repay money each month. Understanding how to read it can help you manage your finances better, avoid unnecessary fees, and protect yourself from fraud. Whether you’re a new cardholder or a seasoned spender, knowing what each section means ensures you stay in control of your credit.

1. Statement Period and Payment Due Date

At the top of your statement, you’ll find two key dates:

  • Statement Period: The range of dates for which transactions are listed (e.g., March 1–March 31).

  • Payment Due Date: The last day to make at least the minimum payment to avoid late fees and interest charges.

Paying your full balance before the due date helps you avoid interest altogether — a practice known as grace period management.

2. Previous Balance and Payments Received

This section shows what you owed on your last statement and any payments made since then. If you paid your balance in full, your “previous balance” and “payments received” should match. If not, the remaining amount carries over to your current balance.

3. New Purchases and Charges

Every transaction you made during the statement period appears here — including purchases, subscriptions, balance transfers, and cash advances. Review this section carefully for any unauthorized or duplicate charges. Reporting suspicious activity promptly can prevent financial loss and protect your credit score.

4. Interest and Fees

If you carry a balance, your statement lists interest charges based on your card’s Annual Percentage Rate (APR). It also includes any late payment fees, cash advance fees, or foreign transaction fees. Understanding these costs helps you see how borrowing behaviors affect your monthly total.

5. Minimum Payment Warning

Your statement shows the minimum payment due — the smallest amount you must pay to remain in good standing. However, only paying the minimum means you’ll incur interest on the remaining balance, potentially keeping you in debt longer. Always aim to pay more than the minimum, if possible.

6. Available Credit and Credit Limit

This section highlights how much credit you have left to use. Keeping your credit utilization ratio below 30% (the percentage of available credit you’re using) can help maintain or improve your credit score.

7. Rewards and Points Summary

If your card offers rewards or cashback, you’ll see a summary of points earned, redeemed, or carried over. Keeping track of these can help you maximize your benefits and plan smarter spending.

Conclusion

Reading your credit card statement isn’t just about checking your balance — it’s about understanding your financial habits. By reviewing each section carefully, you can catch errors early, manage debt responsibly, and make the most of your credit. A few minutes each month can save you money and strengthen your financial health for years to come.

Understanding Credit Card Interest Rates

Credit cards offer convenience and flexibility, but understanding how interest rates work is essential to avoid costly debt. Many people use credit cards without realizing how interest accumulates or how rates vary based on usage. Gaining clarity on these concepts can help you make smarter financial decisions and keep your credit healthy.

What Are Credit Card Interest Rates?

A credit card interest rate, also known as the Annual Percentage Rate (APR), is the cost you pay for borrowing money from your credit card issuer. It’s expressed as a yearly percentage, but it typically applies monthly if you carry a balance. When you don’t pay off your full balance by the due date, the remaining amount starts accruing interest based on your APR. Different types of transactions — such as purchases, balance transfers, and cash advances — can each have their own rate.

How Interest Is Calculated

Credit card interest is usually calculated using your average daily balance. The issuer divides your APR by 365 to find your daily periodic rate, then multiplies it by your balance each day. For example, if your APR is 18%, your daily rate is roughly 0.049%. If your daily balance averages $1,000, you’ll pay about $0.49 in interest per day — which can quickly add up over a month. Compounding interest means that unpaid interest can also start accruing interest, making it harder to pay off debt over time.

Fixed vs. Variable Rates

Credit card APRs can be fixed or variable. A fixed rate stays the same unless your lender notifies you of a change, while a variable rate fluctuates with market conditions — often tied to the prime rate. Understanding which type you have helps you plan ahead, especially during times of economic fluctuation. When interest rates rise nationally, variable APRs can increase without warning, impacting your monthly payments.

Tips to Manage and Reduce Interest

The best way to avoid paying interest is to pay your balance in full each month. If that’s not possible, focus on paying more than the minimum amount due to reduce your balance faster. You can also look for introductory 0% APR offers or balance transfer cards to consolidate debt at a lower rate temporarily. Maintaining a good credit score can help you qualify for lower interest rates over time. Finally, monitor your statements regularly to spot unexpected rate changes or additional fees.

Conclusion

Understanding credit card interest rates is key to staying in control of your finances. By learning how APRs work and managing your payments strategically, you can minimize interest costs, protect your credit score, and make your credit card work for you — not against you.

Building Credit with a Secured Credit Card

For individuals new to credit or trying to rebuild their financial reputation, a secured credit card can be a valuable starting point. Unlike traditional cards, secured cards require a refundable deposit that serves as collateral and determines your credit limit. They help establish a positive payment history, which is crucial for improving your credit score over time. Used wisely, a secured card can open the door to financial independence and better borrowing opportunities.

Benefits of Using a Secured Credit Card

The main advantage of a secured card is its accessibility. Even with poor or no credit history, approval is typically easier since the deposit reduces the lender’s risk. Regular, on-time payments are reported to credit bureaus, gradually improving your credit score. Additionally, secured cards encourage disciplined spending habits because your limit is tied to your deposit, making it easier to manage expenses and avoid excessive debt. Over time, responsible use can help you qualify for unsecured credit cards and better financial products.

How to Use It Effectively

To maximize the benefits, use your secured card strategically. Keep your credit utilization below 30% of your available limit and pay your balance in full each month to avoid interest charges. Set up payment reminders or automatic payments to ensure consistency. Avoid applying for multiple credit products at once, as this can lead to hard inquiries that temporarily lower your score. Regular monitoring of your credit report helps track progress and detect errors early.

Common Mistakes to Avoid

A secured card can harm your credit if misused. Late or missed payments are still reported to credit bureaus, negatively impacting your score. Closing the account too early may also erase your growing credit history. Lastly, carrying high balances defeats the purpose of improving credit utilization ratios. Treat your secured card as a steppingstone — not a long-term dependency — in your credit-building journey.

Conclusion

A secured credit card is an excellent tool for anyone looking to build or rebuild credit responsibly. With consistent use and timely payments, it can strengthen your credit profile and pave the way for financial stability. Remember, the key lies in discipline and long-term commitment to sound financial habits.

Balance Transfers Explained: Pros and Cons

Balance transfers can be a smart financial tool when used strategically, offering a way to consolidate debt and save on interest. Many credit card companies promote balance transfer offers with low or even 0% introductory rates, attracting those struggling with high-interest balances. However, while these offers can provide relief, they also come with potential drawbacks. Understanding how balance transfers work—and when to use them—can help you make informed financial decisions.

The Advantages of Balance Transfers

The most obvious advantage is interest savings. By reducing or eliminating interest temporarily, you can direct more of your payments toward reducing the principal. Another benefit is debt consolidation, which simplifies financial management by combining multiple balances into a single payment. This can also improve your credit utilization ratio, potentially boost your credit score if manage responsibly. For disciplined borrowers, a balance transfer provides a valuable window to clear debts faster without accumulating extra interest.

The Hidden Drawbacks

Despite the appeal, balance transfers are not free of risks. Once the promotional period ends, the interest rate often jumps sharply—sometimes even higher than your original rate. Additionally, any missed payments can cancel the promotional offer, reinstating full interest charges. The balance transfer fee can also reduce your savings if the transferred amount is small or if repayment takes longer than expected. Another pitfall is the temptation to continue spending on the old card after transferring the balance, leading to more debt instead of less.

When a Balance Transfer Makes Sense

A balance transfer works best when you have a clear repayment plan and strong financial discipline. If you can pay off most or all of the balance before the introductory rate expires, the savings can be substantial. It’s also effective for consolidating multiple credit card debts into one manageable account. However, if you tend to miss payments or carry balances beyond the promotional period, the costs can outweigh the benefits.

Conclusion

Balance transfers can be a powerful tool for managing credit card debt—when used wisely. They offer a temporary escape from high interest but require careful planning and discipline. Evaluate the fees, terms, and repayment timeline before making a move to ensure it truly benefits your financial goals.

How Many Credit Cards Should You Really Have?

There is no one-size-fits-all answer to how many credit cards a person should have, but most credit experts recommend holding at least one to build or maintain a good credit history. Having two to three credit cards is generally considered ideal for most people, as this balance allows you to enjoy diverse rewards, a better credit utilization ratio, and backup options while keeping account management practical.

Why Have Multiple Credit Cards?

  • Improve Credit Score: More cards can boost your available credit, lowering your credit utilization ratio—an important factor in your credit score.

  • Maximize Rewards: Different cards offer unique rewards, cashback, or travel benefits; using multiple cards strategically helps maximize value.

  • Backup and Convenience: If a card is lost or temporarily blocked, others serve as backups for emergencies.

Potential Downsides

  • Complexity: Managing more cards increases the risk of missed payments or annual fees.

  • Credit Impact: Each application triggers a hard inquiry and holding too many cards, if not managed well, might hurt your credit.

Expert Recommendations

  • Minimum: One credit card is sufficient for building credit.

  • Ideal Range: Two to three credit cards offer the right mix of benefits and simplicity for most individuals.

  • Customize by Lifestyle: Ultimately, the right number depends on personal spending habits, financial goals, and the ability to manage payments responsibly.

How to Spot and Report Suspicious Credit Card Activity

Credit card fraud and unauthorized use remain significant concerns. Spotting suspicious activity early and reporting it promptly can prevent financial loss and identity theft.

  • Common Signs of Suspicious Activity:

    • Unrecognized transactions or charges on statements.

    • Multiple small transactions in a short period.

    • Unexpected decline of transactions despite available credit.

    • Notifications about password resets or changes you did not initiate.

  • Monitor Regularly: Regularly reviewing credit card statements and using mobile alerts for every transaction helps detect fraud early.

  • Protect Your Card Information: Avoid sharing card details and be cautious when using cards online or in unfamiliar places.

  • Report Immediately: Contact your card issuer or bank immediately if you notice any suspicious transactions. Most banks provide 24/7 fraud helplines.

  • Freeze or Block Your Card: Temporarily freezing the card through the bank’s app or customer service can prevent further unauthorized use while the issue is resolved.

  • File a Police Report if Necessary: For significant fraud cases, a police complaint helps in investigations and formal documentation.

  • Use Fraud Protection Services: Some credit cards come with fraud detection and zero-liability policies, offering additional security and peace of mind.

Being vigilant and proactive is key to protecting your financial health in the digital age.

Different Types of Credit Cards and Their Benefits

Credit cards come in various types, each designed to suit different spending habits and lifestyle needs. Choosing the right card can maximize benefits and rewards.

  • Basic Credit Cards: Ideal for everyday spending with low or no annual fees. They provide rewards points on general purchases and discounts on common expenses like dining and movies.

  • Rewards Credit Cards: Offer points or cashback on every purchase, which can be redeemed for gifts, discounts, or statement credits. Some cards specialize in rewarding specific categories such as groceries or online shopping.

  • Travel Credit Cards: Designed for frequent travelers, these cards offer airport lounge access, flight ticket discounts, travel insurance, and reward points on travel bookings. They can also provide benefits like free hotel stays and concierge services.

  • Premium Credit Cards: These come with higher credit limits and enhanced perks like exclusive event access, concierge service, and complimentary airport lounge access. They usually require a higher income and offer lifestyle-related benefits such as golf and wellness discounts.

  • Co-branded Credit Cards: Issued in partnership with brands, airlines, or retailers, these cards offer extra rewards and benefits when used within the partner network, such as extra air miles or shopping discounts.

  • Fuel Credit Cards: Focused on fuel purchases, these cards provide cashback or discounts at petrol pumps and can offer additional rewards on other categories.