How to Protect Yourself from Credit Card Fraud

Credit cards make everyday life easier, but they also come with risks—especially fraud. Credit card fraud is one of the most common types of financial crime, and it can happen to anyone, from a stolen card number to phishing scams. The good news? With a little awareness and some smart habits, you can significantly reduce your chances of becoming a victim.

1. Monitor Your Accounts Regularly

Check your credit card statements frequently, not just once a month. Many banks offer mobile apps with real-time transaction alerts—enable them. The quicker you catch suspicious activity, the faster you can report it and prevent bigger losses.

2. Use Strong Passwords and Two-Factor Authentication

If you shop online, your accounts may store card information. Protect them with:

  • Strong, unique passwords (avoid reusing across multiple sites).

  • Two-factor authentication (2FA) for an extra layer of security.

3. Be Cautious with Online Shopping

  • Only shop on secure websites (look for “https://” and a padlock symbol).

  • Avoid making purchases over public Wi-Fi. Use a VPN if necessary.

  • Consider using virtual cards or digital wallets like Apple Pay or Google Pay, which mask your actual card number.

4. Watch Out for Phishing Scams

Fraudsters often send emails, texts, or calls pretending to be your bank. Red flags include:

  • Urgent language (“Your account will be closed if…”)

  • Requests for sensitive data (passwords, PINs, card details)

  • Suspicious links—always verify the source before clicking.

5. Keep Your Card Information Secure

  • Don’t share your credit card number over the phone unless you initiated the call.

  • Keep physical cards safe and shred old statements.

  • If your card is lost or stolen, report it immediately.

6. Use Credit Over Debit When Possible

Credit cards often provide stronger fraud protection compared to debit cards. With credit cards, fraudulent charges can usually be reversed quickly without impacting your bank balance.

7. Review Your Credit Report

Regularly check your credit report for accounts or inquiries you don’t recognize.

Final Thoughts

Credit card fraud is a growing concern, but you’re not powerless against it. By monitoring your accounts, practicing safe online habits, and staying alert to scams, you can safeguard your finances and enjoy the convenience of credit with confidence.
How to Choose the Right Credit Card for Your Needs

With so many credit card options available, choosing the right one can be overwhelming. The best credit card for you depends on your spending habits, lifestyle, and financial goals.

If you’re someone who loves traveling, consider a card that offers travel rewards, free airport lounge access, or airline miles. For those who frequently shop online or offline, cashback and rewards cards are ideal. Students or beginners should look for entry-level cards with low annual fees and simple reward structures.

Another important factor is the interest rate (APR). If you often carry a balance, a low-interest credit card will save you money. Also, check for hidden charges like annual fees, foreign transaction fees, and late payment penalties.

Lastly, ensure the card reports to credit bureaus so it helps in building your credit history. Choosing the right card is about balancing benefits with costs. Take time to research, compare, and select the one that aligns with your lifestyle.

Smart Credit Card Habits to Build a Strong Financial Future

Credit cards can be powerful tools when used responsibly. They not only provide convenience for everyday purchases but also help in building a good credit history. However, if not managed carefully, they can lead to debt and financial stress.

One of the smartest habits is paying your credit card bill in full and on time each month. This helps you avoid interest charges and late payment fees. Another important habit is keeping your credit utilization low—ideally under 30% of your credit limit. This shows lenders that you’re financially disciplined.

Additionally, take advantage of credit card rewards, cashback, and perks, but only if you can manage your spending. Overspending just to earn points can backfire. Always monitor your statements for errors or fraudulent charges to ensure your financial security.

When used wisely, credit cards can be steppingstones toward better financial opportunities such as loans and mortgages. Build habits today that will benefit your future.

Common Mistakes That Hurt Your Credit Score

Your credit score is one of the most important aspects of your financial health, but many people unintentionally damage it without realizing. Small mistakes can have a long-term impact, so it’s important to be aware of what to avoid.

One common mistake is missing payments. Even a single late payment can lower your score significantly. Another issue is using too much of your available credit, which signals to lenders that you might be financially stretched. Constantly applying for new credit cards can also hurt, as multiple inquiries make you look risky.

To keep your score healthy, focus on consistent habits: pay bills on time, use less than 30% of your available credit, and avoid unnecessary debt. Building good credit takes time, but avoiding these mistakes will help you move in the right direction.

The Pros and Cons of Using Credit Cards

Credit cards have become an essential part of modern financial life. They offer convenience, security, and the ability to build credit, but they also come with risks if not used wisely. Let’s explore both the advantages and disadvantages.

Pros of Using Credit Cards

  1. Convenience – Credit cards allow you to make purchases without carrying cash. They’re widely accepted both online and in stores.

  2. Build Credit History – Responsible usage helps establish a strong credit score, which is important for loans, mortgages, or even renting an apartment.

  3. Rewards and Cashback – Many credit cards offer cashback, reward points, or travel miles that can save you money.

  4. Purchase Protection – Most credit cards provide fraud protection, extended warranties, and chargeback rights for faulty goods.

  5. Emergency Funds – Credit cards can be a financial backup during unexpected expenses.

Cons of Using Credit Cards

  1. High Interest Rates – Carrying a balance can lead to hefty interest charges.

  2. Debt Trap – Overspending can result in accumulating debt that becomes hard to manage.

  3. Impact on Credit Score – Late payments or high credit utilization can lower your credit rating.

  4. Annual Fees – Some cards charge high fees that may outweigh the benefits.

  5. Hidden Costs – Foreign transaction fees, late fees, and penalty APRs can add up quickly.

Final Thoughts
Credit cards are powerful financial tools when managed responsibly. Paying balances in full, monitoring spending, and avoiding unnecessary debt are key to reaping the benefits while minimizing the drawbacks.

Smart Ways to Use Credit Without Falling Into Debt

Credit cards and loans can be powerful tools when used wisely. But if mismanaged, they can quickly spiral into overwhelming debt. The key is learning to use credit smartly for convenience and growth without harming your financial health.

Smart Credit Habits

  1. Pay in Full, On Time – Always clear your credit card bill before the due date to avoid interest charges.
  2. Track Spending – Use apps or statements to monitor where your money is going.
  3. Avoid Minimum Payments – Paying only the minimum amount due keeps you in debt longer.
  4. Leverage Rewards – Take advantage of cashback, reward points, and discounts, but only on planned purchases.
  5. Borrow Only What You Need – Don’t overextend with unnecessary loans or extra credit cards.

Benefits of Smart Credit Use

  • Builds a strong credit history.
  • Provides financial flexibility during emergencies.
  • Offers perks like travel rewards, discounts, and insurance coverage.

Conclusion

Credit is not the enemy—it’s a tool. When managed responsibly, it helps you build wealth, enjoy rewards, and handle financial challenges with ease. The secret lies in discipline and mindful borrowing.

Understanding Credit Scores – Your Financial Report Card

Introduction

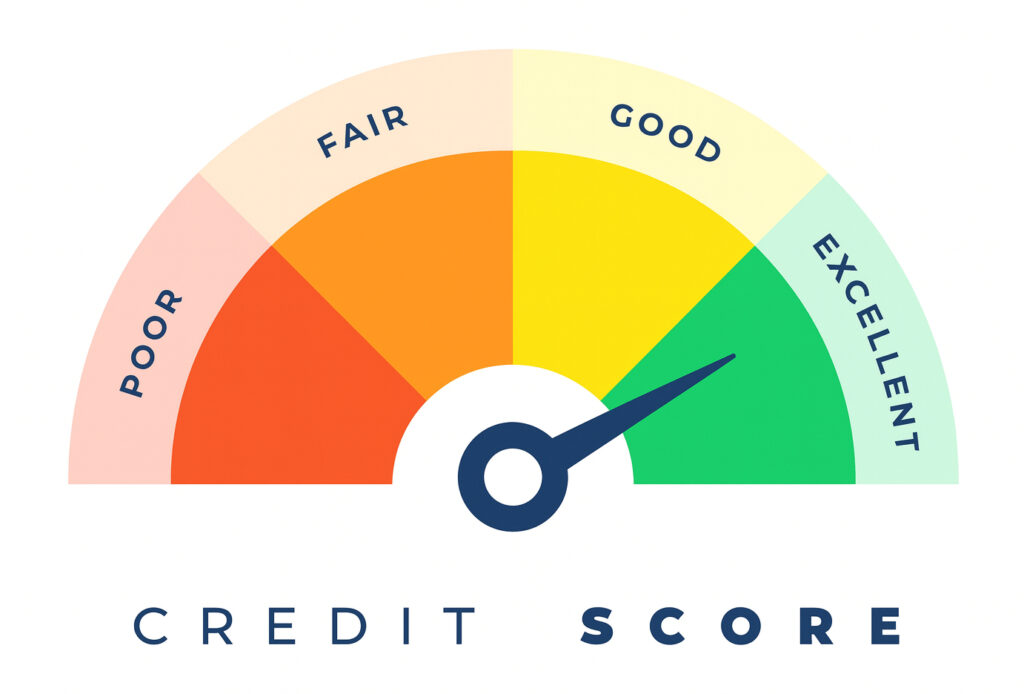
Your credit score is more than just a number—it’s your financial identity. It tells lenders how reliable you are when it comes to borrowing and repaying money. Whether you want a home loan, car loan, or even a new credit card, your credit score plays a vital role.

What is a Credit Score?

A credit score is a three-digit number (usually between 300–900) calculated based on your borrowing and repayment history. The higher the score, the better your chances of getting approved for loans with favorable terms.

Factors That Affect Your Credit Score

  1. Payment History – On-time bill and EMI payments improve your score.

  2. Credit Utilization – Using less than 30% of your available credit keeps your score healthy.

  3. Credit Mix – A balance of credit cards and loans shows responsible borrowing.

  4. Length of Credit History – The longer your credit history, the better.

  5. Hard Inquiries – Frequent loan or card applications can reduce your score.

Why It Matters

  • Easier loan approvals.

  • Lower interest rates.

  • Better credit card offers.

Conclusion

Think of your credit score as a financial passport. Maintaining a strong score not only improves access to credit but also saves you money in the long run.