Supplemental insurance can fill the gaps left by a primary plan, but not every add-on is worth the premium. Start by identifying routine costs and exposures you already pay out of pocket. A clear, focused checklist makes it easier to compare what different policies actually cover. This piece walks through five practical checks to help you avoid surprises and choose coverage that fits everyday life.
Start with the gaps your main plan leaves
Before shopping for extras, list the services your primary coverage either limits or excludes. Look at copays, deductibles, and whether common needs—like urgent care, mental health visits, or durable medical equipment—have high out-of-pocket costs. Understanding these gaps prevents buying redundant coverage that only overlaps existing benefits. That clarity narrows your choices and keeps premiums targeted to real needs.
Once you document those gaps, prioritize them by frequency and cost. Frequent low-cost needs and rare high-cost events should be weighed differently. This helps you decide whether to insure for predictable expenses or rare catastrophes.
Match benefits to likely services
Not all supplemental policies are created equal: some focus on dental and vision, others on hospital indemnity or prescription drug gaps. Choose benefits that reflect your health patterns, current prescriptions, and anticipated checkups. Think seasonally too—if hearing or mobility supports are likely, look for specific riders rather than generic coverage. A narrowly targeted plan can offer more useful protection for less money.
- Dental or vision for regular, predictable care.
- Hospital or critical-illness riders for high-cost events.
- Prescription gap plans if you regularly hit coverage limits.
Compare plans by the same benefit type rather than across types. That makes apples-to-apples comparisons simpler and highlights real differences in payouts and caps.
Compare costs, limits, and exclusions
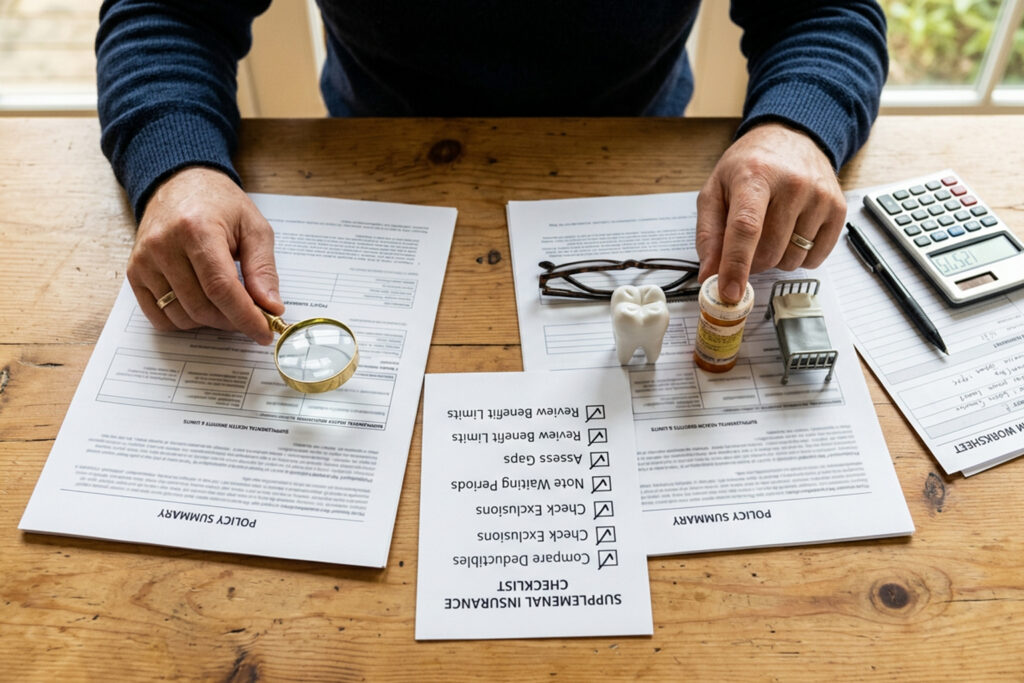
Premiums are only part of the price; inspect limits, waiting periods, and exclusions closely. A low monthly cost can come with long waiting periods or benefit caps that render the plan ineffective when you need it most. Also watch for exclusions tied to preexisting conditions or specific treatments. Small print matters: look for lifetime or annual maximums and how benefits are calculated.
Ask for sample claim scenarios from providers to see how the math works. That practical example often reveals where value is and where gaps remain.
Policy details and practical steps
Before you commit, confirm provider networks, claims filing timelines, and customer service options. Check whether you can bundle plans for a discount and whether there are guaranteed renewability clauses. Keep a one-page summary of key facts—premium, deductible, maximums, and contact info—for easy reference during open enrollment or renewals.
Policies change, so review annually and after any health or financial change. Staying proactive helps you avoid paying for unused benefits or being underinsured at a critical time.
Conclusion
Focus on the real gaps in your primary coverage and match benefits to likely needs. Compare costs against limits, waiting periods, and exclusions before buying. A simple checklist and yearly review will keep your supplemental coverage useful and affordable.