Juggling a wallet full of plastic can feel like extra work for very little payoff.
Cutting down to a smaller set of cards doesn’t mean you have to give up rewards or protection.
This piece shows a practical way to pick a compact set that covers everyday needs and occasional perks.
Follow a few simple habits and you’ll spend less time managing accounts and more time enjoying the benefits.
Pick Two Primary Cards
Choose one card for everyday purchases and one for larger recurring expenses or travel.
The everyday card should offer consistent cash back or a flat-rate reward that applies to most purchases.
Use the second card for bills, subscriptions, and travel where benefits like warranties or insurance matter more.
Limiting to two primary cards forces discipline and makes it easier to monitor spending and due dates.
Keeping this small core reduces the chance of missed payments and lowers the cognitive load of optimization.
You can still keep a third backup for specialty needs if desired.
Map Cards to Spending Categories
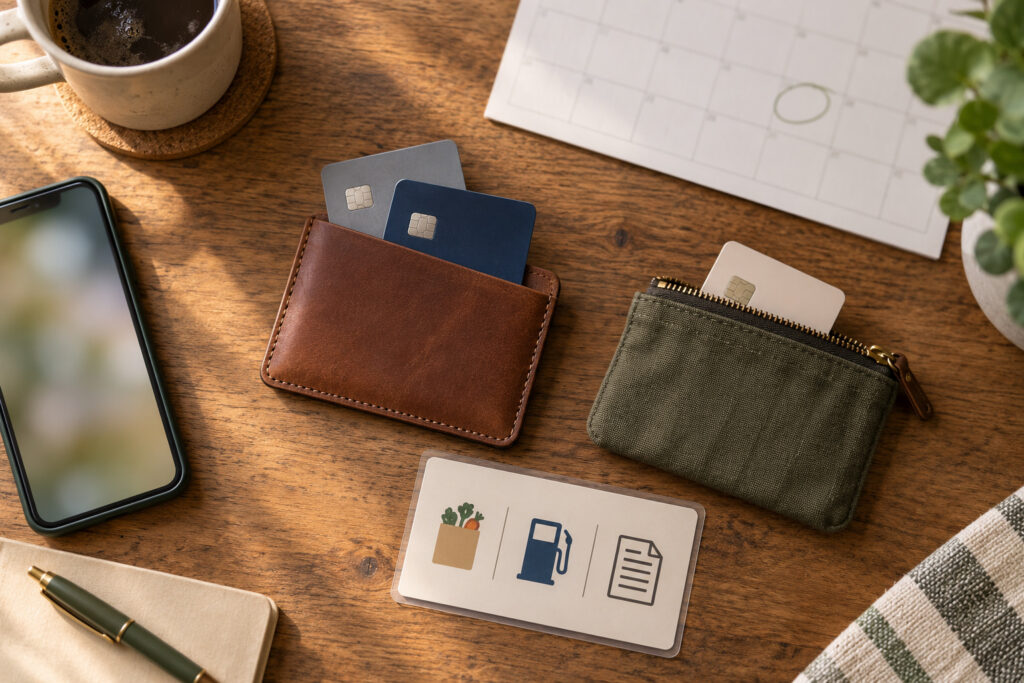
List your biggest monthly categories—groceries, fuel, utilities, dining—and assign the card that rewards each category best.
If one card covers 80 percent of your purchases, make it your primary and lean on others only where they clearly win.
This mapping prevents switching cards at the checkout and ensures you collect predictable value over time.
Review the assignments quarterly since merchant categories and bonus offers change throughout the year.
- Groceries — card A
- Subscriptions and bills — card B
- Gas and transit — card A or specialized card
Once mapped, set that assignment into your budget habits so reaching for the right card becomes automatic.
A simple cheat sheet in your phone or wallet helps at busy registers.
Keep Track of Billing Cycles
Align statement dates and due dates with your cash flow so payments fall after payday when possible.
If moving dates isn’t feasible, use autopay for at least the minimum to avoid late fees, and manually pay the remainder.
Small timing changes can free up short-term cash without carrying balances and interest.
Understanding the cycle also reveals when to make big purchases to maximize interest-free days.
Use calendar reminders or a finance app to watch for upcoming payments and statements.
That little bit of scheduling prevents surprises at the end of the month.
Manage Infrequent Cards and Benefits
Keep cards with annual benefits only if those perks outweigh fees and you will actually use them.
If a card sits unused, consider reassigning its benefit to a card you carry, downgrading the account, or closing it carefully.
Store credentials for occasional cards in a secure place and remove them from autopay if they aren’t active.
That approach preserves perks without bloating your monthly routine.
Regularly audit fees and benefits so you aren’t paying for unused services.
A brief yearly review keeps the small collection focused and valuable.
Conclusion
Fewer cards mean less hassle and clearer earning opportunities.
Keep two primary cards, map spending, and time your payments to suit cash flow.
A short annual audit will protect value and keep your setup tidy.