Open enrollment is the annual moment to stop and reassess supplemental insurance rather than letting the same plan roll forward by default. Small changes in benefits, premiums, or your health needs can leave you paying for options you no longer use or missing coverage you will need. Take time this season to gather plan documents, recent medical bills, and a list of providers you prefer. A focused review now can reduce unexpected costs and improve your care access next year.
Assess what your primary plan already covers
Start by listing services your core plan pays for and where limits or copays appear. Check hospitalization, outpatient procedures, prescription drug tiers, and any limits on therapy or durable medical equipment. Look for gaps such as dental, vision, hearing, or extra home health support that often fall outside a primary policy. Knowing those holes gives you a precise starting point for choosing supplemental benefits.
Gather recent statements and a short summary you can compare across options. That paperwork makes trade-offs between premium increases and out-of-pocket risk much clearer.
Match supplemental benefits to realistic needs
Prioritize benefits you are likely to use rather than every available rider or add-on. If you rarely use specialty care but expect higher prescription costs, a plan with drug coverage or lower drug copays may offer better value. Consider your family medical history and any scheduled procedures when weighing chronic care or skilled nursing benefits. Coverage that seems generous on paper can become costly if it duplicates services already provided.
Keep a simple checklist of must-haves and nice-to-haves to guide decisions during enrollment windows. That keeps choices practical and focused on likely expenses.
Check provider networks and paperwork requirements
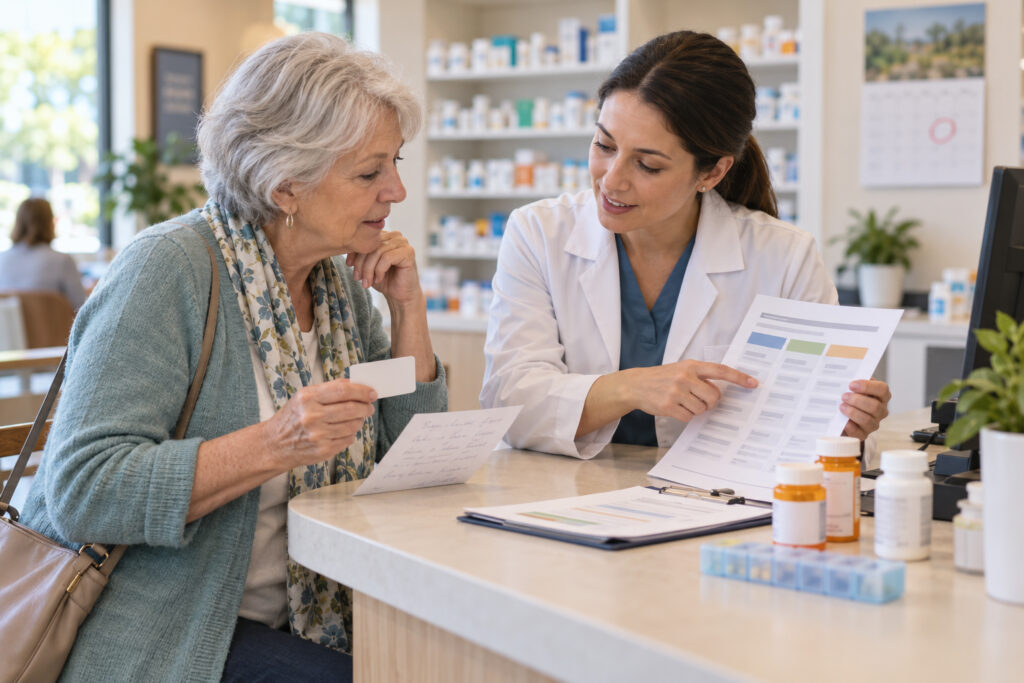
A supplemental plan is only useful if it lets you see clinicians you trust at reasonable cost. Confirm preferred doctors and pharmacies are in-network, and read prior authorization rules that could delay care. Some plans require specific referrals or documentation for benefits to apply, and missing a step can mean denied claims. Time spent clarifying these administrative rules prevents surprises when care is needed.
If switching plans, contact a few of your main providers to confirm acceptance before finalizing enrollment. A quick phone call can save a lot of hassle later.
Watch premiums, limits, and enrollment rules
Compare total annual cost, not just monthly premiums: add deductibles, copays, and the maximum out-of-pocket to see real exposure. Note deadlines and rules for changing or canceling supplemental coverage; outside qualifying events, you may be locked in until the next enrollment period. Also check whether benefits change with age or include step-downs that affect later years.
Balance short-term savings against potential long-term bills so your choice protects both budget and access to care.
Conclusion
Spend an hour this enrollment season assembling documents, comparing real costs, and confirming provider networks. A clear, prioritized checklist helps you pick supplemental benefits that match likely needs without unnecessary extras. Small effort now can prevent expensive surprises and improve care access all year.