Choosing health insurance after age 50 often feels like juggling choices and fine print while life keeps moving. You want dependable access to the doctors and medications that keep you well, but premiums, deductibles, and networks push and pull on your wallet. This article breaks down what matters most so you can make clearer comparisons instead of guessing. Read with a notepad handy — a short checklist makes decisions far less stressful.
Clarify your healthcare priorities
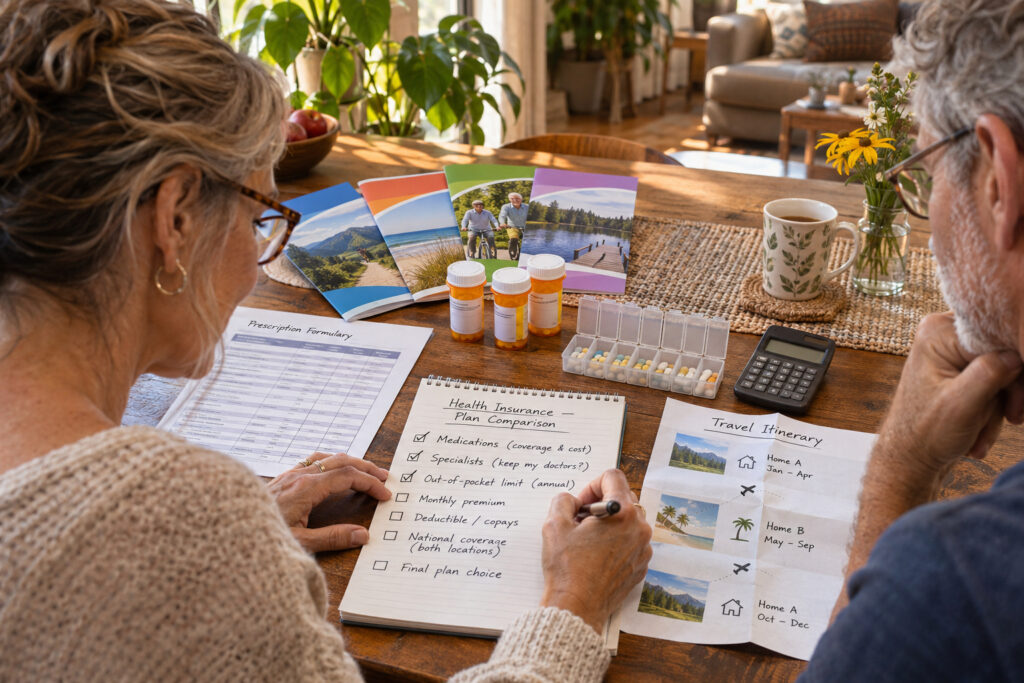
Start by listing how you actually use healthcare: regular specialist visits, a handful of prescriptions, or an expected procedure in the next year. Consider chronic conditions that require steady management and whether continuity of care with a current provider is nonnegotiable. Think about how often you travel or split time between places, since that affects network and out-of-area coverage. If prescription costs dominate your bills, that should steer you toward plans with generous drug coverage even if premiums are higher.
Having a ranked list of needs turns abstract plan comparisons into practical choices. When you know what you won’t compromise on, the rest becomes negotiable.
Understand how plan types differ
Insurance structures vary: some plans emphasize low premiums but higher costs when care is used, while others charge more monthly for predictable copays and lower deductibles. Networks also differ — more restrictive networks often lower premiums but reduce provider choice, whereas broader networks increase flexibility at a cost. Some options pair with savings accounts that let you set aside pre-tax money for medical spending, which can be helpful if you expect larger, planned expenses. Also check whether the plan requires referrals for specialists or uses prior authorization for certain services.
Compare realistic scenarios rather than only the monthly premium: run the numbers for a year of typical use, including prescriptions and a few visits. That arithmetic shows which plan is genuinely cheaper for your situation.
Look past the premium: networks, drugs, and out-of-pocket limits
Premiums are visible but rarely tell the whole story. Examine the drug formulary to see tiers and typical copays, confirm your preferred doctors are in-network, and note the out-of-pocket maximum — that cap is the worst-case protection if major care is needed. Also check rules about referrals, telehealth access, and how emergencies out of network are handled. Small differences in coverage rules can lead to large unexpected bills.
- Network breadth and whether your specialists are listed
- Prescription formulary tiers and estimated monthly drug costs
- Deductible, copays, and the annual out-of-pocket maximum
Use a recent year of medical statements to test plans: plug in typical visits and meds to estimate true annual cost. If something looks risky, reach out to the insurer or an independent advisor for clarification before you enroll.
Conclusion
Choosing the right plan after 50 means balancing cost with reliable access to care and medications you depend on. Take time to compare a few realistic scenarios and prioritize what you won’t compromise on. A thoughtful selection now can reduce surprises and protect your health and finances down the road.