Life shifts — a new diagnosis, a move, or a change in income — are good moments to take another look at supplemental insurance.
Small adjustments now can prevent costly surprises later and keep coverage aligned with everyday needs.
This short guide lists clear, practical steps you can follow when life changes make your current plan feel off-kilter.
Use these checkpoints to decide what to keep, what to tweak, and when to shop around.
Take inventory of your current coverage
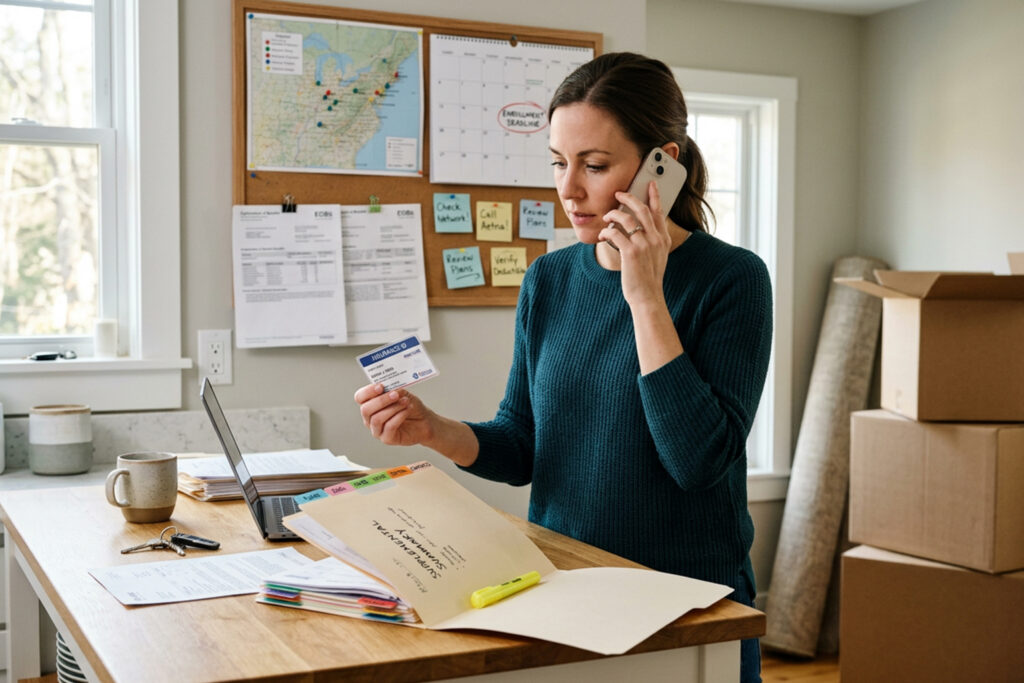
Begin by assembling the policies, ID numbers, and recent explanations of benefits so nothing important is overlooked. Look at deductibles, copays, limits, and any exclusions that matter for your new situation. Note which services are reimbursed and which require preauthorization to avoid denied claims later.
Having a single, organized summary makes comparison easier and reduces the risk of gaps. Keep this summary updated after each medical visit, move, or budget change.
Match benefits to the specific life change
If you moved, check networks and out-of-area coverage; if you added a chronic condition, look for plans that cover specialist visits and durable medical equipment. For budget changes, consider whether higher out-of-pocket exposure could be offset by lower premiums, or vice versa. Think about practical daily needs as well as rare but expensive events.
Focus on the few benefits that will affect you most often; trimming peripheral coverages can save money, but core protections should remain intact. Prioritize based on frequency and cost impact.
Compare real costs, not just premiums
Request sample cost scenarios from insurers: common office visits, a short hospital stay, and a specialist referral. Add premiums, deductibles, copays, and coinsurance to estimate your annual spending under each option. That helps reveal plans that look cheap but become costly when care is needed.
Also check provider lists and claims turnaround times; convenience and predictable payments can matter as much as headline price. A slightly higher premium might be worth it if it reduces surprise bills.
Timing, paperwork, and practical tips
Know enrollment windows and how changes triggered by life events may allow mid-year updates. Keep records of any qualifying life events and gather supporting documents before contacting insurers. When switching, confirm there’s no coverage gap and understand how preexisting conditions are treated.
Take your time to read policy riders and exclusions; short phone calls can clarify confusing clauses and save headaches later. Keep a dated record of every change so future reviews are faster.
Conclusion
Reviewing supplemental insurance after a life change is manageable with a few focused steps.
Inventory your coverage, match benefits to the change, and compare realistic costs before deciding.
Small, timely updates can protect both your health and your budget.