Credit cards don’t need to be complicated to be useful. A short set of clear rules can keep rewards, payments, and balances predictable without constant effort. This article lays out a compact approach you can follow month after month. Read it once, print it if you like, and use it as your quick reference.
Set a Practical Card Hierarchy
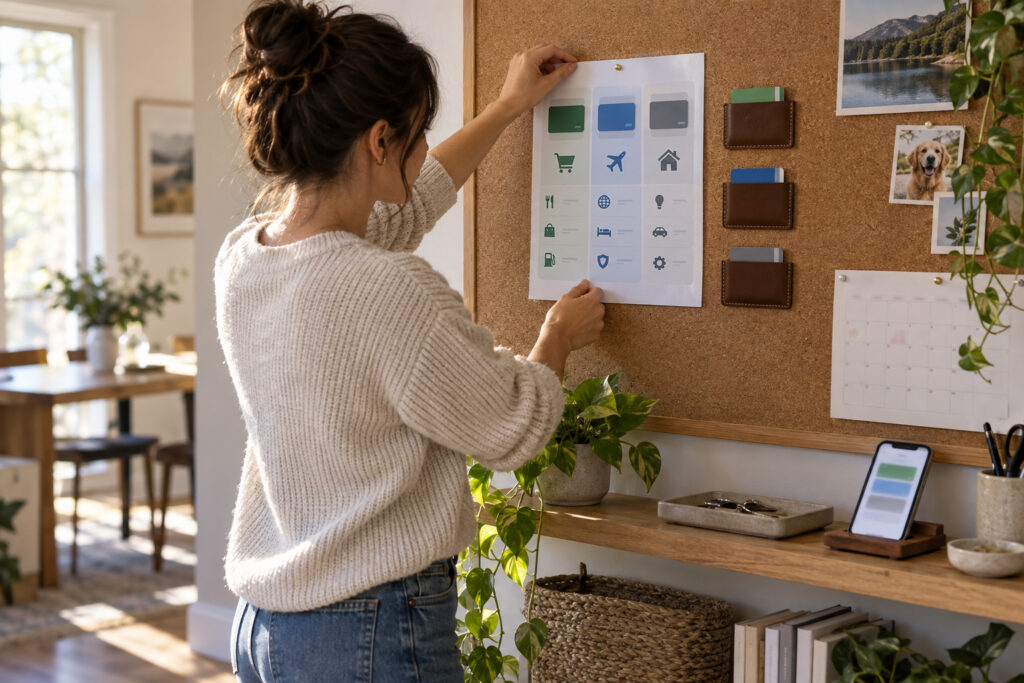
Start by assigning roles to each card so you don’t think about them every time you pay. Pick one card for everyday purchases, one for travel or big-ticket rewards, and one as backup or for specific categories like groceries or gas. Keep the number low enough that you remember which card does what, but high enough to capture meaningful benefits.
Write these roles down where you can see them — a note in your wallet app or a tiny card in your phone. When a new offer arrives, ask how it fits into these roles before applying. This keeps accounts purposeful rather than scattered.
Match Cards to Real Monthly Habits
Look at three months of statements and map spending categories to the cards in your hierarchy. Use the card that gives the best return for a given habit: put groceries on the grocery card, recurring subscriptions on the card with the best protection, and general spending on your primary card. Avoid switching for tiny gains; stability preserves rewards and tracking simplicity.
Set a calendar reminder once per quarter to reassess if your habits change. Small adjustments replace big, confusing overhauls and keep your system efficient. Consistency earns more than chasing every new bonus.
Use Billing Cycles to Your Advantage
Align large purchases with the billing cycle that gives you the longest interest-free float while still paying in full each month. Knowing statement close and due dates for each card reduces overdraft risk and keeps cash flow smoother. For recurring bills, set autopay for the minimum and add a manual payment reminder a few days before the due date to avoid mistakes.
Paying in full is the simplest path to avoid interest and preserve the value of rewards. If you carry a balance, prioritize reducing that amount before optimizing perks. Small timing changes can save real dollars over a year.
Monitor, Prune, and Protect
Review accounts every six months: cancel cards that cost more than they deliver, freeze ones you don’t use, and keep active the ones that match your goals. Check for unexpected fees and duplicate benefits, and consolidate where it reduces complexity without losing value. Protect your cards with alerts and secure passwords on linked accounts.
Regular, light maintenance beats occasional heavy scrambles. Treat cleanup as routine housework, not a crisis task, and your credit toolbox will stay lean and useful.
Conclusion
Pick a few clear roles, align cards with real habits, and time payments around billing cycles.
Keep changes small and review periodically to stay efficient.
A short rule set like this makes credit cards predictable and useful without stress.