Too many cards can turn everyday spending into a juggling act. Pick a small set you actually use and design simple rules for when each one gets charged. That approach keeps rewards meaningful and reduces the chance of missed payments or surprise fees. The goal is fewer choices and clearer wins when you pay.
Align Cards to Real Habits
Start by listing where you spend most—groceries, gas, dining, subscriptions—and match each category to a single card that offers the best return. Keep one general-purpose card for purchases that don’t fit those categories so you don’t lose rewards by guessing. This reduces decision fatigue and makes it easier to remember which card to use in the moment. Over time you’ll see how small adjustments increase effective rewards without extra effort.
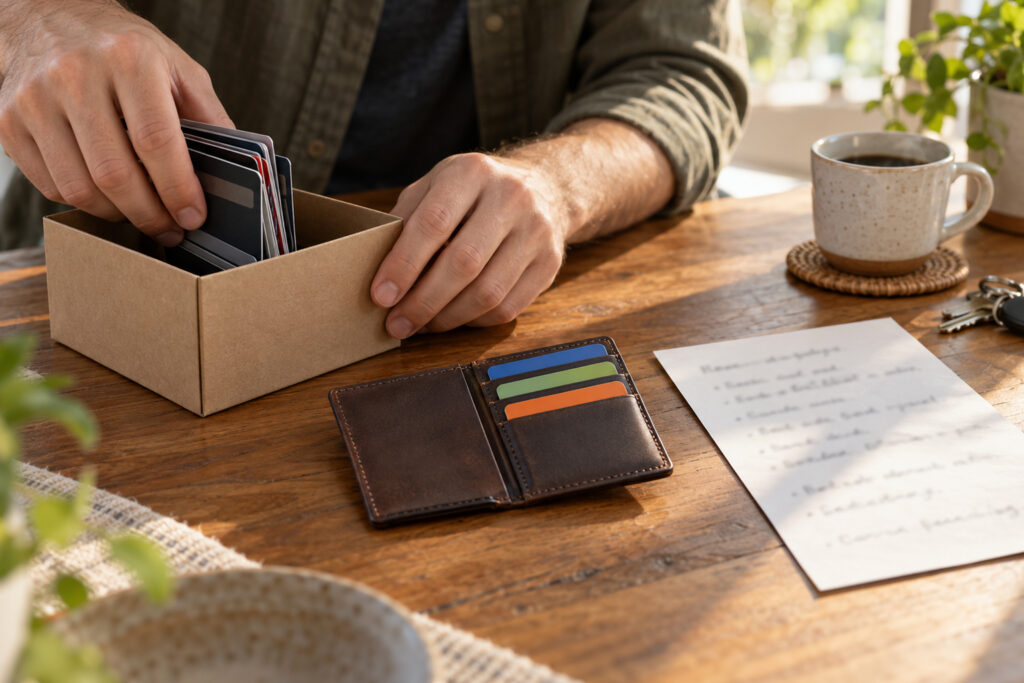
Use obvious cues to anchor choices: put the grocery card near your receipts, set a default card in your phone wallet, or leave unused plastic at home. These simple habits cut accidental charges to the wrong account. The fewer steps between habit and action, the more reliably rewards accumulate.
Reduce Interest and Avoid Overlap
Rewards matter until interest does. If a card carries a balance, its interest can wipe out any benefit from cash back or points, so prioritize paying down high-rate balances before chasing perks. Where overlap exists—two cards offering similar grocery rewards, for example—pick the one with the cleaner fee structure and better protections. Closing redundant accounts may slightly affect credit history, but it often simplifies finances and lowers the risk of missed payments.
Make on-time payments a non-negotiable rule by aligning due dates with paydays or setting automatic minimum payments. When you free up mental space from tracking many statements, you’ll be less likely to incur costly interest or penalties.
Keep an Annual Card Review
Once a year, audit the cards you carry: check fees, perks you actually use, and any welcome bonus timelines. Cancel or downgrade cards that no longer pull their weight, and consider product-changing offers from your issuer before closing an account. A short, regular review prevents slow leaks of value from unused benefits and unnecessary fees.
Document the decisions you make in a one-page note—purpose for each card, typical monthly spend per card, and the next review date. This record keeps your wallet aligned with real life rather than loyalty to offers that no longer fit.
Conclusion
Choosing fewer cards and assigning each a clear role reduces mistakes and improves rewards. Regular reviews and sensible payment rules protect your cash flow and credit. The result: a leaner wallet that reliably supports your everyday finances.