Choosing supplemental insurance can feel like wading through fine print while juggling what matters most: costs, coverage, and peace of mind. A smart choice starts with clear priorities and a quick checklist you can actually use. This piece focuses on the practical questions to ask and the red flags to watch for. Keep these points handy when you compare plans or speak with an agent.
Pinpoint what you truly need
Before you look at plans, list the specific gaps you want to fill so you avoid paying for extras you won’t use. Think about regular prescriptions, frequent specialist visits, dental and vision needs, and potential long-term care expenses. Prioritizing helps you judge whether a plan’s benefits align with your everyday healthcare patterns. It also makes comparisons faster and less overwhelming.
- Typical gaps: copays and deductibles, prescription coverage, outpatient therapies.
- Consider upcoming life changes that may affect needs in the next 12–24 months.
With a short prioritized list you can reject plans that misalign at a glance. That saves time and prevents impulse buys based on glossy brochures or sales pitches.
Read exclusions and benefit limits
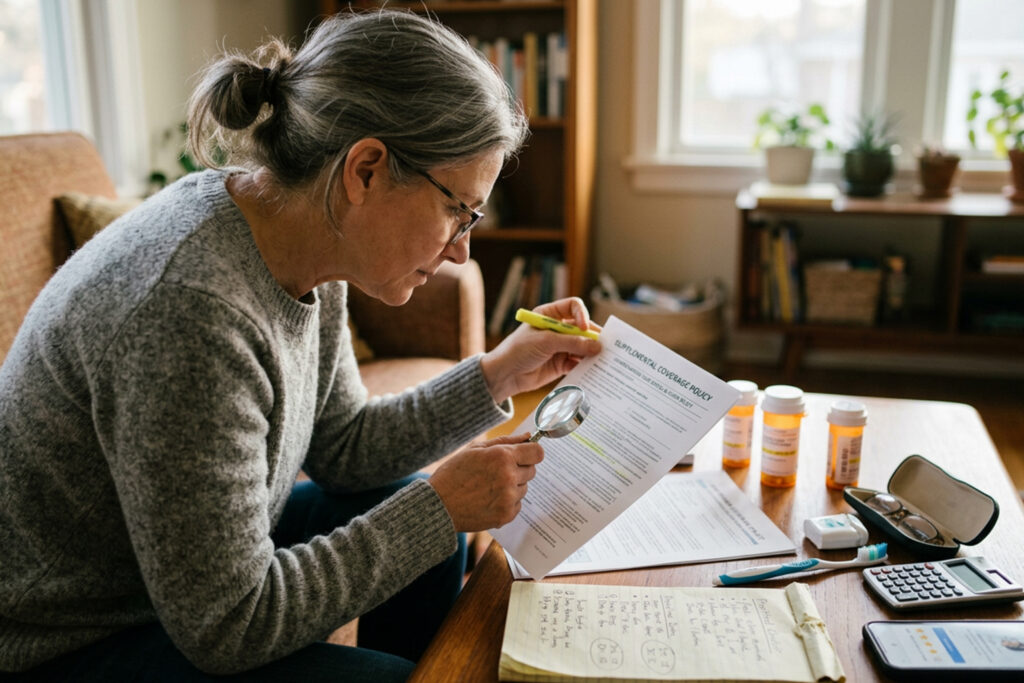
Exclusions and caps are where a promise can fall apart; they determine what won’t be paid even when a claim seems straightforward. Watch for waiting periods, preexisting condition clauses, lifetime maximums, and limits on specific services like mental health or durable medical equipment. Also note whether the plan coordinates with any primary policy to avoid duplicate denials. These details are usually buried in the policy language, so look for them early.
If a plan omits clear language about exclusions, ask for written confirmation. Policies with many caveats often cost less for a reason—make sure that reason doesn’t leave you exposed.
Compare total cost, not just premiums
Premiums are only part of the expense picture. Include deductibles, copay amounts, coinsurance percentages, and any per-claim or annual caps when you do the math. Consider how often you use services: a low premium might be offset by high copays if you visit doctors frequently. Also check whether the plan has network restrictions that could increase out-of-pocket costs if you prefer certain providers.
- Calculate likely annual spend based on your recent medical use.
- Ask whether premiums rise with age or claims history at renewal.
A realistic cost estimate helps you choose a plan that fits both your budget and likely care needs. Don’t let a small monthly price tag be the only deciding factor.
Test claims service and contract flexibility
How a company handles claims reveals a lot about real-world value: check average processing times, dispute procedures, and ease of submitting paperwork. Read reviews or ask for references if possible, and find out how often the insurer changes contract terms at renewal. Flexibility for adding riders or adjusting coverage year to year can be useful as needs change.
Good customer service and clear claims procedures reduce stress when you need care. If a provider is evasive or slow with answers now, assume it won’t improve later.
Conclusion
Take time to match coverage to your actual needs, not to sales materials or lowest premiums alone. Scrutinize exclusions, total costs, and the insurer’s claims record before signing. A careful review today can prevent unpleasant surprises later.