Supplemental insurance can feel like a tangle of fine print and benefit names that sound similar but behave differently.
Many buyers pick a plan because premiums look low or a familiar word appears in the title.
Those simple choices can leave gaps when a claim arrives or a preferred provider isn’t covered.
This piece points out the small items that change how a policy performs when you need it most.
Before you make any switch or add-on, take a moment to look past surface features and understand the mechanics behind them.
Why the fine print matters
Two policies with the same monthly cost can pay out very differently depending on limits, waiting periods, and exclusions. Read the clauses about preexisting conditions, lifetime caps, and what counts as a covered event; they often determine real value more than the headline benefit. Pay attention to how benefits are triggered — some plans require a hospital stay, others pay for outpatient procedures, and that affects whether you’ll see reimbursement. Also note whether inflation or annual adjustments are built in, since fixed-dollar benefits lose buying power over time.
- Look for definitions of key terms like “disability” or “qualified provider.”
- Check how long the insurer has to respond to claims and appeals.
Those items won’t be highlighted in marketing, but they control the speed and amount of any payout. A quick scan now saves frustration later.
Commonly overlooked policy items
People often skip details about network rules, coordination with other insurance, and rider exclusions. Network restrictions can force you to use providers who accept the plan, or leave you paying much more out of pocket for out-of-network care. Coordination clauses explain whether the supplemental plan pays before or after your primary coverage, which affects your immediate bills. Riders and add-ons may seem inexpensive until you realize they duplicate benefits you already have elsewhere.
- Out-of-network penalties and referral requirements.
- How the policy interacts with employer or government benefits.
- Whether certain treatments require prior authorization.
Spotting these items ensures the policy fills genuine gaps instead of offering redundant or unusable coverage. It also helps you compare apples to apples.
Checklist to review before you commit
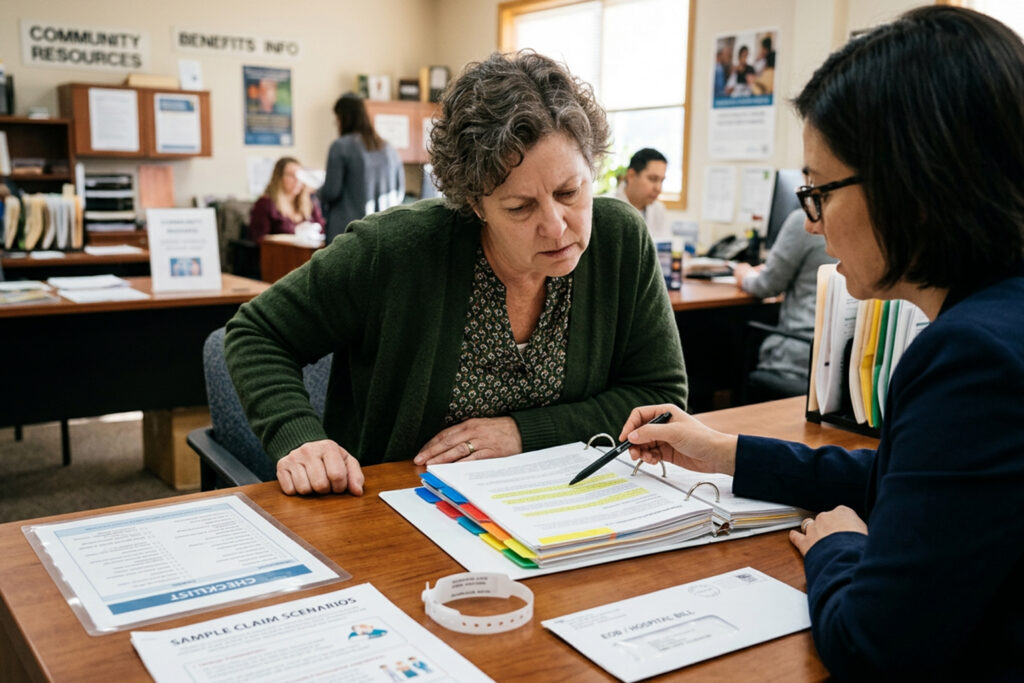
Put a short checklist together: definitions, limits, waiting periods, network rules, coordination, and appeals procedures. Ask for sample claim scenarios from the insurer so you can see how benefits would apply in practice. Confirm any verbal assurances in writing and note the effective date for coverage changes. Finally, compare the total expected annual cost — premiums plus likely out-of-pocket expenses — not just the monthly price.
- Request a copy of the policy and read highlighted clauses.
- Call customer service with specific hypothetical claims to test responses.
- Check review periods and cancellation terms.
- Make sure any agent promises are included in the contract.
These steps help you choose a plan that behaves as you expect when you claim. They also reduce surprises and make comparisons clearer.
Conclusion
Small policy details often determine whether supplemental coverage actually helps when you need it.
Spend time on definitions, limits, and how the plan works with other coverage before you buy.
A focused review now will protect your finances and give you clearer peace of mind later.