Credit scores respond to patterns, not moments. A few consistent choices—timing payments, keeping balances low, and watching your accounts—add up faster than a single big action. That steady behavior signals to lenders that you handle credit responsibly. These are practical shifts people can make without changing their whole financial life.
Prioritize on-time payments
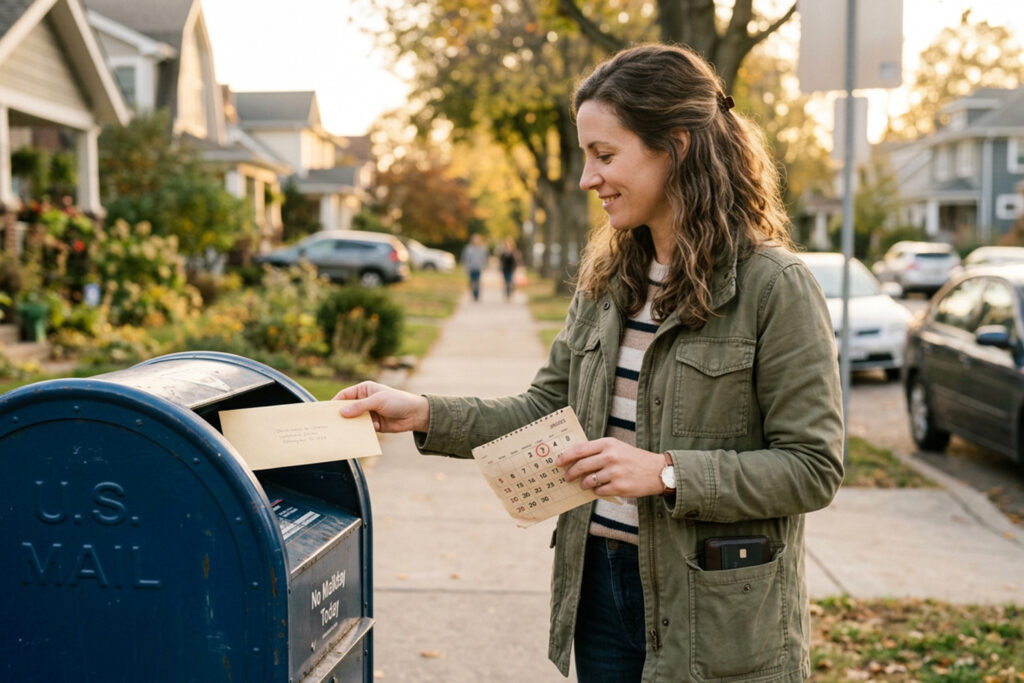
Payment history has the largest influence on most scoring models, so missing a due date can do more damage than a slightly high balance. Set calendar reminders, enroll in autopay for minimums, or schedule payments a few days before the statement closing date to avoid processing delays. If cash flow is uneven, contact creditors to arrange a temporary plan rather than skipping a payment.
Small timing changes matter. Paying even a few days earlier shows reliability and prevents late flags that stay on reports for months or years.
Manage credit utilization
Utilization is the percentage of available credit you’re using; lower is generally better. Aim to keep balances under about 30% of each card’s limit, and ideally much lower on cards lenders scrutinize most. If a statement balance looks high, a quick mid-cycle payment before the statement posts can reduce the reported balance and help your score.
Consider requesting a credit limit increase only if you can keep balances steady. That can lower utilization immediately without adding new accounts.
Use credit tools thoughtfully
Secured cards, credit-builder loans, and authorized-user status can be effective when used with discipline. Choose the simplest tool that fits your situation so you don’t introduce unnecessary complexity. Opening several accounts at once or applying for credit you don’t need can create hard inquiries and short-term dips.
- Start with one product and monitor its effect.
- Avoid closing older accounts unless there’s a strong reason.
These tools are helpful when they support steady habits rather than replace them.
Check reports and correct errors
Errors on credit reports happen more often than people realize and can drag scores down. Pull reports periodically, look for incorrect balances, duplicated accounts, or misreported late payments, and follow each bureau’s process to dispute mistakes. Keeping documentation of payments and communications makes disputes smoother.
Regular checks also help you spot unexpected activity quickly, giving you time to address identity theft or billing errors before they become bigger problems.
Conclusion
Small, consistent choices compound into meaningful credit improvement over time. Focus on timely payments, sensible utilization, and clean reports to build reliable momentum. Those steady habits create the trust lenders look for.