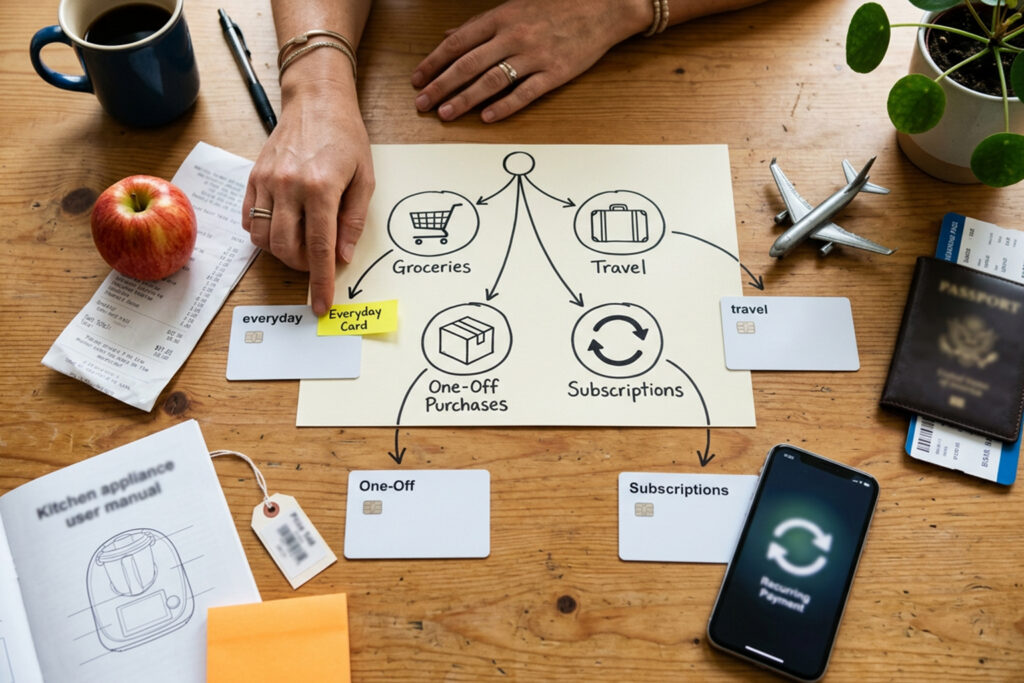
Picking the right card for each purchase doesn’t need to be a spreadsheet puzzle. A few clear rules can save money, earn more rewards, and reduce friction at checkout. Think in terms of purpose: everyday essentials, large one-off buys, travel, and recurring bills each deserve a short list of go-to cards. This article lays out a straightforward decision map so you can act quickly and confidently.
Everyday Spending: Pick for Category Strength
For regular purchases — groceries, gas, dining, and streaming — choose the card that pays most in the relevant category. Keep one primary card for essentials and a backup that boosts rotating or seasonal categories. If you shop at a preferred store regularly, a store or co-branded card that raises earnings there can outweigh a generic cashback card. Balance reward rates against any annual fee: a modest fee can be worth it if it consistently returns more value than you pay.
Set your phone wallet to default to the primary everyday card so you don’t overthink at the register. Periodically check category changes before renewal season to make sure your top card still earns the most. Small habit fixes like these compound into noticeable annual savings.
Large Purchases and 0% Offers
When you need to buy something big — appliances, furniture, or an emergency repair — two criteria matter: financing and protection. A card with a 0% promotional APR can ease cashflow but read the fine print on how long the rate applies and whether a late payment voids it. Cards that include extended warranty or purchase protection may save on repair or replacement costs if something goes wrong soon after purchase. Also check if the issuer offers price protection or negotiated dispute support for hefty items.
Plan the payment timeline before you swipe. If you can pay sooner than the promotional period ends, that often beats carrying a balance at a higher ongoing APR.
Travel, Subscriptions, and Seasonal Rotations
Use travel-focused cards for flights and hotels to access perks like free checked bags, airport lounge access, or travel credits that offset annual fees. For subscriptions, designate a single low-fee card so renewals are easy to track and don’t surprise you with unfamiliar charges. If you have cards with rotating categories, establish a brief checklist each quarter to switch the card you use for bonus categories.
- Assign one travel card for flight and hotel bookings.
- Use a subscription card dedicated to recurring charges.
- Rotate quarterly-bonus cards for groceries and gas.
Keep a simple, visible reminder — a note in your wallet app or a sticker on your card sleeve — so you remember which card rules apply. That small cue prevents mistakes and preserves rewards over time.
Conclusion
Match each purchase to one clear rule: category strength for everyday buys, financing and protection for large purchases, and a single card for subscriptions. Keep the system short and visible so good habits stick without thinking. The fewer decisions you must make at checkout, the more consistent your rewards and savings will be.