Rotate Cards Smartly to Balance Rewards and Simplicity

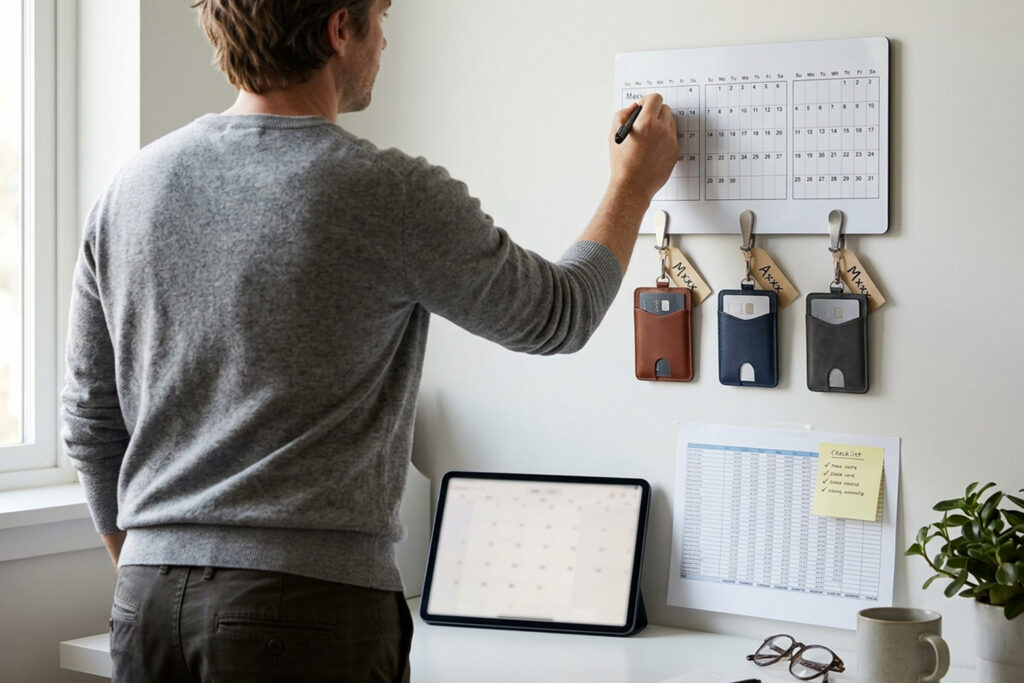
Rotating credit cards on purpose keeps rewards fresh without adding unnecessary accounts or clutter to your life. Choose a small set of cards and use different ones for categories that change month to month or to match bonus periods and merchant promos. That approach squeezes more value from sign-up and category bonuses while keeping tracking realistic and manageable. You’ll need a simple calendar and a few tidy rules so it doesn’t turn into extra work.

Why rotating cards helps

Rotating cards helps you capture limited-time bonuses, quarterly category multipliers, and merchant-specific offers that otherwise sit unused. Instead of chasing every promo, you let each card earn its strength at the right time: groceries on one quarter, gas on another, travel during a bonus window. That concentrated use boosts effective rewards per dollar without requiring dozens of active accounts. It also reduces the risk of interest or late fees by keeping spending predictable and focused.

Think of rotation as strategic focus rather than juggling. Small, consistent rules keep the benefits and cut the hassle. A little planning preserves the upside.

How to design a rotation schedule

Start by listing your regular expenses and mapping which cards offer the best return for each category. Build a three- to six-month calendar that marks rotating bonus windows and major seasonal spends like travel or back-to-school shopping. Set reminders a week before a switch and plan automatic payments to the primary card for subscriptions to avoid missed charges. Keep a single spreadsheet or notes app with clear labels so you can glance and act quickly.

Simplicity is the guardrail that makes rotation sustainable. If a schedule feels busy, lengthen rotations or pare the card set down. A short checklist keeps things consistent.

Preventing mistakes and staying organized

Common mistakes include switching too often, ignoring annual fees, and letting rewards expiration erode value. Watch the math: a small annual fee can be worth it if the card’s targeted bonuses cover more than the cost, but it’s not automatic. Use calendar alerts, check statements weekly, and consolidate rewards into one payout method so redemption remains painless. Avoid carrying revolving balances on cards meant for rewards; interest wipes out benefits fast.

Organization prevents small errors from negating gains. Keep rules minimal and review the plan every few months. Small adjustments can compound into meaningful value.

Conclusion

Rotation can raise rewards while keeping your wallet tidy. The key is a short list of cards, a simple calendar, and rules that match your life. Do a quarterly check and adjust rather than chasing every new offer.
Choosing Supplemental Insurance That Matches Everyday Needs

Supplemental insurance can close gaps your primary plan leaves open, but it’s not one-size-fits-all. Start by listing the services and out-of-pocket costs you encounter most often, such as prescription drugs, dental visits, or vision care. Knowing those everyday patterns helps you compare plans on the benefits that matter, rather than on flashy extras you’ll never use. This short checklist approach keeps choices practical and budgets steady.

Identify the real gaps in your base coverage

Begin with a careful review of your main policy to see what’s excluded or limited. Look for common shortfalls like deductibles, coinsurance, skilled nursing limits, and prescription tiers that could trigger surprises. Pay attention to whether certain providers or treatments require prior authorization or sit on a different coverage tier. This foundation clarifies which supplemental benefits would actually reduce your routine costs.

Once you know the gaps, you can ignore irrelevant add-ons and focus on value. That perspective prevents overlap and saves premiums over time.

Match benefits to likely expenses, not hypotheticals

Estimate your annual use of services—how often you fill prescriptions, see specialists, or need rehabilitation. If prescriptions dominate your out-of-pocket spending, a plan with strong drug coverage and predictable copays will matter more than enhanced dental. For someone with frequent therapy or home health needs, look for supplemental riders that lower coinsurance for those services. Choose benefits that reduce recurring costs rather than those that only help in rare, high-cost situations.

Prioritizing predictable savings makes coverage easier to evaluate and compare. It also helps keep premium increases in perspective.

Consider cost, flexibility, and provider access together

Premium is only one piece of the puzzle; balance it against potential savings and network limitations. A low-premium plan that forces you to change doctors or pay higher copays may not be worth it. Check whether supplemental plans coordinate smoothly with your existing providers and whether they require referrals. Flexibility and continuity of care often deliver better value than small premium differences.

Read the fine print on renewability, exclusions, and guaranteed issue periods so you won’t be locked into unexpected gaps later. These terms affect long-term affordability and access.

Conclusion

Focus on the benefits you actually use and compare how each plan lowers those specific costs. Balance premium with provider access and predictable savings to avoid unpleasant surprises. A targeted approach keeps coverage useful and affordable over time.

Slow Wins: Practical Routines for Better Credit

Improving your credit doesn’t require dramatic moves overnight.
Small, steady routines build trust with lenders and make future borrowing simpler.
A handful of predictable monthly habits can prevent mistakes and gradually raise your score.
This piece lays out practical, low-stress steps you can start using this month.

Regular checks: catch mistakes before they cost you

Run a credit report or view your score at least once a month to spot errors and unfamiliar accounts. Errors — like a misreported late payment or an old collection — can shave points and linger if left unchecked. When something looks wrong, document the detail, contact the creditor, and file a dispute with the reporting bureau. Routine checking turns surprises into manageable tasks rather than crises.

Keeping a short monthly checklist makes this habit painless and consistent. Note any recent inquiries, new accounts, or balance jumps and act quickly if anything seems off.

Pay smarter: timing and minimums matter

On-time payments are the single biggest influence on most scoring models, so prioritize them without overcomplicating your budget. If a single due date causes stress, split payments or set automatic drafts a few days before the bill is due to avoid glitches. Paying more than the minimum when possible lowers interest and reduces balances faster, which helps scores long-term. Small buffer strategies protect you from one-off slips that stick on your record.

Use calendar alerts or autopay to make punctuality routine rather than a repeated decision. Keep small emergency funds so you aren’t forced to miss a payment when cash is tight.

Mange balances: keep utilization low and predictable

Credit utilization — the percent of available credit you use — is a powerful, often overlooked factor. Aim to keep individual card balances well below their limits and your overall utilization under about a third of available credit, or lower if you can. If a big purchase spikes utilization, pay down the card before the statement closes or spread the purchase across cards sensibly. Small, frequent payments can prevent a large statement balance from hurting your score.

Monitor how balances trend each statement cycle and adjust spending or payment timing to avoid surprises. Consistent low usage is easier to maintain than occasional deep cuts.

Build quietly: add positive accounts thoughtfully

If your history is thin, consider a secured card or a small installment loan designed to report payments to the bureaus. Don’t open accounts just for variety — each new account triggers a hard inquiry and short-term dip for most scoring systems. Instead, add one reliable tradeline and maintain punctual payments to establish a record. Over time, a few clean accounts with on-time history outweigh a long list of unused credit.

Choose products that report to all three bureaus so your positive behavior is visible everywhere. Patience pays off more than churn.

Conclusion

Small, consistent habits compound into meaningful credit improvement over months and years.
Focus on on-time payments, manageable balances, and simple monitoring routines.
Stick to a few reliable moves and your score will reflect the effort.

When to Keep or Close a Credit Card: A Practical Guide

Deciding whether to keep or close a credit card can feel unexpectedly complicated.
Small details—annual fees, rewards, account age—matter more than you might think.
A few deliberate checks will usually give you a clear answer without drama.
This guide offers practical steps so you don’t make a hurried decision you’ll regret.

Assess the Financial Role of Each Card

Start by listing what each card contributes: rewards, insurance, purchase protection, or a reliable backup for emergencies. Consider how each card affects your credit utilization and the average age of accounts, since those influence your credit profile. If a card earns cash back or points you actually use, it likely delivers ongoing value even with a modest fee. Conversely, a rarely used card without benefits is a candidate for re-evaluation.

Keep cards that help you meet clear goals: travel perks you redeem, a low-rate card for planned purchases, or a longstanding account that supports your credit history. Treat sentimental or duplicate cards skeptically unless they serve a practical purpose.

Signs It’s Time to Close a Card

Closing makes sense when the costs exceed the benefits: a steep annual fee without matching perks, repeated fraud concerns, or a card that tempts you into overspending. If an account offers no unique advantage and you never use it, the administrative burden isn’t worth keeping it open. Also consider security: an issuer with poor customer service or frequent breaches may not be worth the risk.

Before shutting an account, weigh the trade-offs. An abrupt closure can nudge up utilization or shorten average account age, so plan the move rather than acting on impulse.

Close Strategically to Protect Your Score

When you decide to close, take steps that minimize damage: pay down balances on other cards to keep utilization low, shift recurring payments to a different card, and ask the issuer about downgrading to a no-fee product instead of closing. Check your credit report after the change to confirm balances and account statuses are reported correctly. Timing matters—avoid closing several accounts at once, and consider waiting until after a major loan application.

Document the closure with the issuer and request written confirmation that the account balance is zero and the status is closed at consumer’s request. That record helps resolve any future reporting errors without stress.

Conclusion

Keep cards that save you money, support important protections, or strengthen your credit profile.
Close cards that are costly, risky, or simply unused—but do so thoughtfully to avoid side effects.
A brief checklist and a calm plan will keep your credit healthy and your finances simpler.

Building a Clear Backup Plan for Retirement Health Costs

Retirement brings more predictable routines but less tolerance for surprise medical bills. A clear backup plan helps you cover what primary insurance does not — from copays to services often excluded from base plans. Putting simple steps in place now reduces stress later and keeps choices flexible as needs change. This short guide outlines practical moves to protect your health and your savings without overcomplicating decisions.

Why a backup plan matters

Primary retirement health coverage reduces many costs but usually leaves holes: deductibles, specialist fees, and non-covered services can still add up quickly. A backup plan acts like a tether — keeping unexpected out-of-pocket expenses from derailing a monthly budget or emergency fund. It also lets you pick comfort choices such as private rooms, preferred providers, or quicker access to particular services. Treating backup coverage as part of your household budget, not a luxury, makes trade-offs easier to evaluate.

Start by mapping how often you use healthcare each year and which bills caused the biggest surprises. That snapshot will show whether you need a modest safety cushion or broader supplemental coverage. Revisit that map annually or after any health change.

Common gaps in retirement health coverage

Several predictable gaps crop up for retirees: limited dental and vision benefits, higher prescription copays, and long-term care costs that insurers often exclude. Routine services that feel small — like hearing aids or mobility aids — can become significant expenses over time. Travel for specialty care and short-term rehabilitation stays are other budget risks many overlook. Identifying these weak spots early helps you decide which add-ons are worth the premium.

  • Dental, vision, and hearing support
  • Prescription drug coverage gaps
  • Long-term care and in-home services

Once you list likely gaps, prioritize them by cost and frequency. Focus first on the items that could blow a year’s budget if they occur.

Practical steps to build your backup

Begin with a liquid emergency fund sized to cover several months of medical-related expenses. If you prefer insurance to savings, compare supplemental policies that specifically target your highest-risk gaps. Consider short-term or limited-benefit plans for episodic needs and look closely at exclusions, waiting periods, and annual maximums. Use plan comparison tools or a planner to line up costs side-by-side rather than relying on premiums alone.

Coordinate benefits so you aren’t paying twice for overlapping coverage. Small adjustments — raising a deductible to lower premiums or choosing a partial benefit rider — can free up money for other priorities.

Choosing sensible additions without overpaying

A sensible addition addresses a clear need, not a hypothetical fear. Ask three practical questions: How often will I use this? What is the realistic cost if I don’t have it? Is there a cheaper alternative, like a health savings buffer or targeted riders? Avoid broad policies with many rarely used benefits when a focused supplement will do.

Shop during open enrollment windows but don’t wait for a crisis to decide. Small, timely adjustments make a backup plan affordable and effective.

Conclusion

Build your backup plan around real risks and realistic costs, not marketing promises. Keep a mix of liquid savings and targeted supplements so you can adapt as circumstances change. Regular check-ins ensure the plan stays useful and cost-effective.

Small Monthly Habits That Grow Your Credit Confidence

Improving a credit score doesn’t require dramatic moves, costly products, or major lifestyle upheaval. Small, repeated habits over weeks and months compound into steady, reliable progress that you can see on statements. Below are practical monthly checkpoints—simple actions and reminders you can add to a calendar or phone alert. Track results, make small adjustments, and let momentum do the rest.

Take one clear inventory each month

Open a single spreadsheet or a note where you list every credit card and loan, current balances, minimum payments, interest rates, and due dates so nothing hides from view. Keeping one monthly snapshot prevents missed charges and reveals which accounts need focused attention first, such as high-interest loans or nearly maxed cards. Update it each time statements arrive and after any big purchase so your numbers reflect new activity and you avoid unpleasant surprises when you reconcile. That discipline makes monthly decisions faster and less stressful.

Review which accounts are near high utilization thresholds and prioritize them for payments or balance transfers if appropriate. The clearer the picture, the easier it is to pick a small, effective target that moves your score over time.

Pay smarter: timing over extra cash

On-time payments remain the most influential factor in most scoring models, so set payments to post a day or two before the official due date to avoid late marks. Automate minimum payments to prevent mishaps, and schedule extra payments in months you have spare cash to chip away at balances faster. For revolving accounts, consider an additional mid-cycle payment to lower the balance that gets reported to bureaus without needing to change spending habits. Those timing tweaks can reduce reported utilization and show consistent repayment behavior, which scoring systems reward.

Automation removes human error and reduces the chance of an avoidable late payment harming your record. Periodically check that funds cleared and that your bank and creditors record payments on the intended dates.

Keep credit limits healthy and review new offers

High utilization hurts more than having several open accounts, so avoid maxing any card even temporarily and spread charges across cards when possible. If you qualify for a modest credit-limit increase, that can immediately improve your utilization ratio without adding new spending capacity you don’t need. Be cautious about opening many new accounts in a short span because new inquiries and short account age can lower scores briefly. Still, targeted, well-timed additions combined with consistently low balances can support growth over the long term.

Each month, scan for sensible offers and weigh the short-term score dip against potential long-term benefits like lower interest or improved capacity. Keep older accounts active with a small charge and prompt payoff to preserve account age and show continued use.

Conclusion

A few focused monthly habits reduce surprises and build steady credit momentum that becomes visible on reports and offers. Track balances, time payments carefully, and prioritize small wins instead of chasing quick fixes. Over several months those measured choices add up to better borrowing options and more financial confidence.

Designating One Card for Subscriptions Cuts Headaches and Fees

Monthly subscriptions sneak into budgets faster than most one-off purchases, and when they live on different cards it becomes easy to lose track of renewals, trial charges, and unexpected fee increases. Naming a single card for recurring charges reduces surprises and makes disputes and cancellations simpler. It also helps you see the true monthly burden at a glance and spot duplicate or forgotten services. For people juggling several accounts, a dedicated subscription card is a low-effort control that pays off in fewer billing headaches.

Why dedicate a card to subscriptions

Putting all recurring charges on one card centralizes recordkeeping and strengthens fraud detection because unfamiliar charges stand out immediately. It lowers the cognitive load of reconciling statements: instead of scanning three or four accounts you only review one account for the subscriptions line item. A single-card approach can also protect your main spending card from unwanted holds or temporary authorizations that some services use. Finally, it gives you a clean timeline when you need to cancel or dispute a charge.

  • Streaming, music, and entertainment memberships
  • Software subscriptions and cloud services
  • Clubs, recurring donations, and annual renewals

Keep the list short and purposeful so the card remains a clear indicator of recurring outflows. If you need to move a service later, transferring it off the subscription card should be a deliberate decision, not a slip of habit.

How to pick the right card and set it up

Choose a card that minimizes cost and maximizes protection: low or no annual fee is helpful since the card will see regular small charges. Favor a card with reliable fraud and dispute resolution, plus good online statement tools that let you tag or search merchant names easily. If rewards matter, pick one that pays consistent cash back or enhanced returns on service-type spending so your recurring bills earn something back. Also consider billing cycle dates and align autopay timing with your cash flow to avoid unexpected overdrafts.

  • Compile a list of subscriptions and their billing dates
  • Update autopay details to the chosen card and save confirmation emails
  • Enable alerts for charges and set a quarterly review reminder

Those three setup steps make the system durable and help you catch accidental renewals early. Small routines like a quarterly check turn a good idea into a lasting habit.

When splitting subscriptions makes sense

Not every service belongs on the same card: high-cost annual subscriptions might fit better on a card that offers purchase protection or bonus category rewards. Businesses should keep company subscriptions on a separate business card for accounting clarity and tax tracking. And if you use a card for trials, consider a different one to avoid impacting your main rewards strategy when you forget to cancel.

Ultimately, flexibility matters—use one card most of the time but move services deliberately when there’s a clear benefit. The goal is control, not rigidity.

Conclusion

Assigning a single card to recurring subscriptions simplifies tracking, reduces fraud risk, and makes cancellations straightforward. Pick a low-fee option with solid dispute protections and set a short list of services to keep the card focused. Routine checks and a few setup steps will keep subscriptions from quietly inflating your monthly bills.

Practical Choices to Improve Your Retirement Health Coverage

Choosing supplemental health coverage in retirement feels like a balancing act between comfort and cost. Start by looking at what your main plan already pays for and which services leave you exposed. That clarity makes it easier to decide whether a supplemental policy is a necessity or an added luxury. Read on for concrete steps to make choices that fit both your health outlook and your budget.

Know the gaps your primary plan leaves

Your base insurance may cover hospital stays and major procedures but not the routine or emerging costs that add up over time. Prescription drugs, dental work, vision care, and extended home health services are common shortfalls. List the services you and your spouse use most often and compare that list to plan summaries. This focused inventory points you to the types of supplemental coverages that would actually lower your out-of-pocket risk.

Don’t assume every rider or add-on is helpful; some overlap with existing benefits. A narrow, well-chosen supplement often beats a broad policy with needless extras. Keep the needs-first mindset as you shop.

Prioritize the benefits that matter most

Once you know the gaps, rank them by likely cost and frequency. High-frequency, moderate-cost needs like prescriptions or dental exams often justify coverage more readily than rare, high-cost events. Think about your health trajectory: chronic conditions increase the value of predictable coverage, while generally healthy people might prefer savings over comprehensive riders. That ranking helps you avoid paying for benefits you’ll seldom use.

  • Prescription drug coverage — high priority for chronic medications.
  • Dental and vision — often excluded but used frequently.
  • Long-term care or home health riders — consider if family support is limited.

Use that prioritized list to filter plans quickly instead of comparing every feature. Filtering saves time and reduces impulse choices.

Compare costs beyond the premium

Monthly premiums are easy to spot, but the real cost picture includes deductibles, copays, and coverage limits. Check annual maximums, waiting periods, and exclusions that could leave you vulnerable. Run through a few realistic scenarios — a routine year, a year with higher medication needs, and a year with a hospitalization — to see how each plan performs. That scenario testing exposes surprises a premium-only comparison will miss.

Also review provider networks and prior authorization rules to avoid service denials. A lower premium is pointless if the plan denies the care you actually need.

Shop timing, rules, and practical checks

Open enrollment and special enrollment periods determine when you can buy or change supplemental plans, and penalties or medical underwriting may apply outside those windows. Gather plan documents, ask specific questions about exclusions, and get confirmations in writing. If possible, compare at least three carriers and read policy summaries side by side to spot critical differences.

Finally, check customer service reputation and claims turnaround; responsiveness matters when you need care. A policy that pays claims reliably will reduce stress and unexpected bills.

Conclusion

Start with a clear list of what your main plan doesn’t cover and rank gaps by likely cost and frequency. Compare total costs and real-world scenarios, not just premiums, and confirm timing and underwriting rules before you buy. Thoughtful, needs-focused choices will give you coverage that protects your wallet and your health without paying for what you won’t use.

Everyday Payment Tweaks That Quietly Improve Credit

Big credit improvements rarely start with dramatic moves. More often they come from modest, repeatable payment changes that steer how lenders see your risk. Shifting when and how much you pay can lower reported balances, avoid late marks and build a dependable pattern on your file. Over months, those tiny adjustments add up into noticeable score gains without extra spending or complex strategies.

Pay before the statement closing date

Timing matters: credit scores often reflect the balance that appears on your statement, not the balance after you make a payment. Paying a few days or a week before the closing date can reduce the amount that gets reported to the bureaus. That simple change lowers your utilization ratio and can lift scores even if you keep spending at the same rate.

Set a calendar reminder or schedule an automatic transfer a few days earlier than usual. This is a practical tweak that costs nothing and is easy to maintain once it becomes routine.

Lower reported balances, not just the minimum

Meeting the minimum keeps accounts current, but it doesn’t always help utilization. Aim to pay down balances so each card reports well below its limit—many advisers suggest targets under 30%, with better results at single digits for top scores. You don’t need to clear accounts completely every month; even one extra payment mid-cycle can make a visible difference.

  • Split large purchases into two payments within the billing cycle.
  • Transfer small amounts from checking to credit before the statement posts.
  • Use balance notifications from your card issuer to stay aware.

These tactics help the numbers lenders see, which is what influences score models most directly. Consistency is the actual weapon here.

Keep older accounts and a predictable routine

Length of credit history and on-time payment patterns both favor accounts kept in good standing. Closing old cards can shorten your average account age and remove useful available credit. Instead, keep low-use cards open and put a small recurring charge on them to ensure activity.

Reliability matters more than novelty. A dependable sequence of payments and open lines tends to beat frequently opening and closing accounts when it comes to steady score gains.

Check reports and correct small errors

Small mistakes—misreported balances, duplicate collections, wrong dates—can ding your score for months if left unchecked. Pull your reports periodically and flag anything that looks off; many corrections are straightforward and fast to resolve. Early detection also prevents minor issues from becoming larger headaches.

Combine regular checks with the payment habits above and you’ll remove friction from a process that otherwise drags down progress.

Conclusion

Improving credit doesn’t always require grand gestures—consistent, smart payment tweaks often do the heavy lifting. Pick one timing or payment habit to test for a few months, then add another once it’s routine. Over time those small moves compound into meaningful, lasting improvement.

Trim Your Wallet: Use Cards That Fit Your Life

Too many cards can turn everyday spending into a juggling act. Pick a small set you actually use and design simple rules for when each one gets charged. That approach keeps rewards meaningful and reduces the chance of missed payments or surprise fees. The goal is fewer choices and clearer wins when you pay.

Align Cards to Real Habits

Start by listing where you spend most—groceries, gas, dining, subscriptions—and match each category to a single card that offers the best return. Keep one general-purpose card for purchases that don’t fit those categories so you don’t lose rewards by guessing. This reduces decision fatigue and makes it easier to remember which card to use in the moment. Over time you’ll see how small adjustments increase effective rewards without extra effort.

Use obvious cues to anchor choices: put the grocery card near your receipts, set a default card in your phone wallet, or leave unused plastic at home. These simple habits cut accidental charges to the wrong account. The fewer steps between habit and action, the more reliably rewards accumulate.

Reduce Interest and Avoid Overlap

Rewards matter until interest does. If a card carries a balance, its interest can wipe out any benefit from cash back or points, so prioritize paying down high-rate balances before chasing perks. Where overlap exists—two cards offering similar grocery rewards, for example—pick the one with the cleaner fee structure and better protections. Closing redundant accounts may slightly affect credit history, but it often simplifies finances and lowers the risk of missed payments.

Make on-time payments a non-negotiable rule by aligning due dates with paydays or setting automatic minimum payments. When you free up mental space from tracking many statements, you’ll be less likely to incur costly interest or penalties.

Keep an Annual Card Review

Once a year, audit the cards you carry: check fees, perks you actually use, and any welcome bonus timelines. Cancel or downgrade cards that no longer pull their weight, and consider product-changing offers from your issuer before closing an account. A short, regular review prevents slow leaks of value from unused benefits and unnecessary fees.

Document the decisions you make in a one-page note—purpose for each card, typical monthly spend per card, and the next review date. This record keeps your wallet aligned with real life rather than loyalty to offers that no longer fit.

Conclusion

Choosing fewer cards and assigning each a clear role reduces mistakes and improves rewards. Regular reviews and sensible payment rules protect your cash flow and credit. The result: a leaner wallet that reliably supports your everyday finances.