Small, consistent choices about when and how you use credit shape the scores lenders see. This article focuses on practical moves you can adopt without overhauling your entire budget. Pick a couple of tactics and stick with them for a few months to see steady improvements. The goal is momentum: gradual progress that becomes routine.
Prioritize Payment Timing
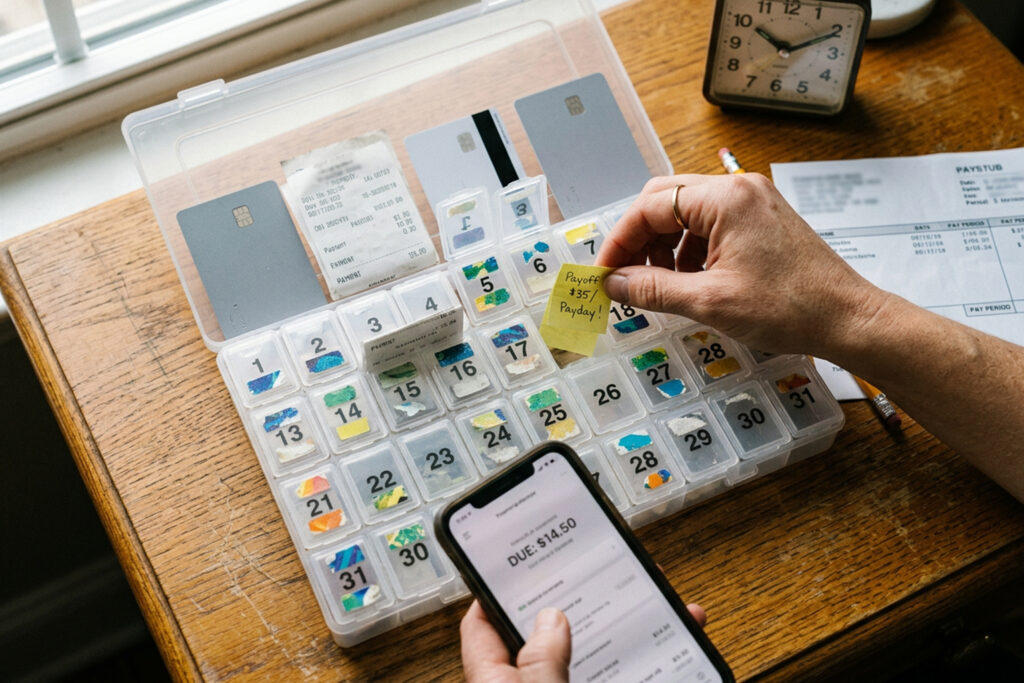
Paying on time is the single most influential habit for most credit scores, and timing matters more than many people realize. Set payments a few days before the due date and align them with your pay schedule so you never miss a cycle. If you struggle with one account, move its due date or set an automated partial payment immediately after payday. Consistent punctual payments build a reliable history that lenders favor.
Automate where it helps and review statements monthly to catch stray charges. Even small late fees or a missed payment can slow progress, so make timing a simple protective routine.
Lower Utilization, Raise Scores
Credit utilization—the percent of available revolving credit you use—is a fast-moving factor you can influence. Try to keep utilization under roughly 30% on each card and overall, and aim lower if you want quicker gains. If a statement balance is high one month, make an extra payment before the statement closing date to reduce the reported balance. Increasing your credit limit can also help, but only if it doesn’t encourage more spending.
Watch each account’s reported balance rather than just your current balance. Small, repeated reductions will help the score reflect safer borrowing behavior.
Keep Accounts Active Strategically
The age and diversity of accounts contribute to credit profiles, so closing old cards can sometimes do more harm than good. Use older accounts occasionally for small purchases you pay off quickly to keep them active. For new accounts, resist opening several at once because multiple inquiries and a shortened average age can weigh on your score. Think of each account as a long-term piece of your credit history.
Maintain a balance between keeping older accounts open and avoiding unnecessary new ones. Strategic activity protects your credit age and mix over time.
Monitor and Correct Your Report
Regularly checking your credit report reveals mistakes and unexpected activity that could drag your score down. Dispute clear errors promptly and follow up until they’re corrected; even one erroneous late payment can have a large effect. Monitoring alerts also helps you spot identity issues early, letting you act before larger problems develop.
Use free annual reports and low-cost monitoring tools as suits your comfort level. Knowing what’s on your report gives you control to make informed, corrective decisions.
Conclusion
Small, repeatable payment and usage habits reliably change credit trends over months rather than overnight. Focus on timing, utilization, account management, and regular checking to build credit with confidence. Consistency matters more than perfection, and steady choices add up.