Small, consistent choices have more impact on credit than dramatic one-off moves.
If you focus on when you pay, how much credit you use, and whether your reports are accurate, scores tend to improve steadily.
This piece lays out a few practical adjustments you can make without adding stress to your day.
Read on for specific, repeatable steps that fit into ordinary routines.
Set clear payment priorities
Start by identifying the bills that matter most to scoring: on-time payments for loans and revolving accounts. Use calendar alerts or automatic payments to avoid missed due dates, but keep enough control to adjust amounts when cash is tight. If you must choose what to pay first, prioritize accounts that have recently fallen behind and those with the largest balances relative to their limits. These focused moves protect score factors that weigh most heavily in most scoring models.
Make a weekly review part of your routine so payments stay on track. A short check-in helps catch anomalies before they become delinquencies.
Manage balances and credit limits
Credit utilization—the ratio of your balances to available limits—affects scores quickly. Aim to keep utilization well below the apparent maximum by paying down cards during the billing cycle, not just at statement due date. If you can, request higher limits on stable accounts; that reduces utilization without increasing debt. Avoid opening multiple new accounts at once, as new inquiries and new limits can temporarily lower a score.
Small reductions in utilization often produce visible score improvement. Treat limits like a tool rather than extra spending room.
Use tools that reduce friction
Technology makes staying on top of credit simpler than ever. Set up autopay for fixed amounts, enable text or app alerts for high balances, and schedule monthly time to reconcile statements. For unpredictable months, lower an autopay temporarily and plan a catch-up when cash is steadier. These modest systems stop reactive scrambling and reduce the chance of errors or missed payments.
- Autopay for minimums, manual top-ups for extra reductions.
- Alerts for balances above chosen thresholds.
Build these protections gradually so they become habits, not chores. Consistency matters more than perfection.
Monitor reports and fix mistakes
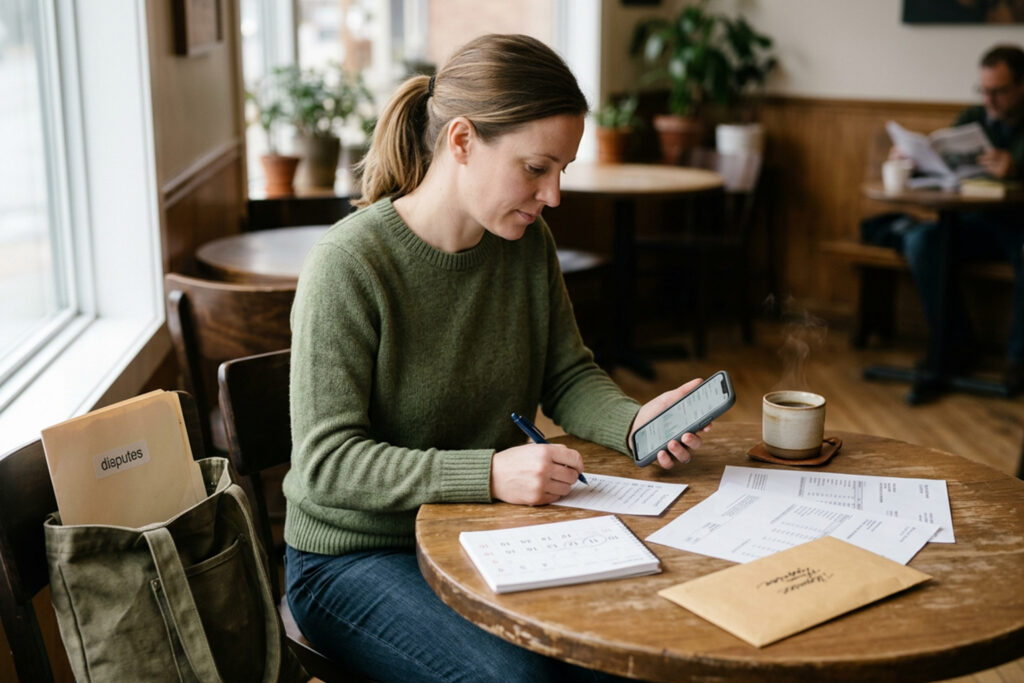
Errors on credit reports are common and removable, but they won’t correct themselves. Check reports at least once a year and dispute any inaccuracies promptly. If identity theft or a billing mistake shows up, act quickly with the creditor and the reporting agency to file disputes and document responses. Even small, corrected errors can lift a score faster than months of careful payments.
Keep a simple folder or digital record of disputes and outcomes. That documentation speeds follow-ups if issues reappear.
Conclusion
Small timing adjustments, disciplined balance management, and routine checks add up over months.
They reduce risk of setbacks while nudging scores upward in measurable ways.
Stick to practical systems and review results periodically to stay on course.