Choosing supplemental health coverage can feel like sorting through a maze of options, premiums, and fine print. Start by clarifying what your base plan already pays for and where it leaves you exposed. Think about the services you use regularly and the expenses that would hurt your budget if they weren’t covered. A clear list of those risks makes the rest of the process far more purposeful.
Begin with realistic expectations about what insurance will do and what it will not. Keep the focus on practical protection rather than trying to eliminate every possible cost.
Start with a clear inventory
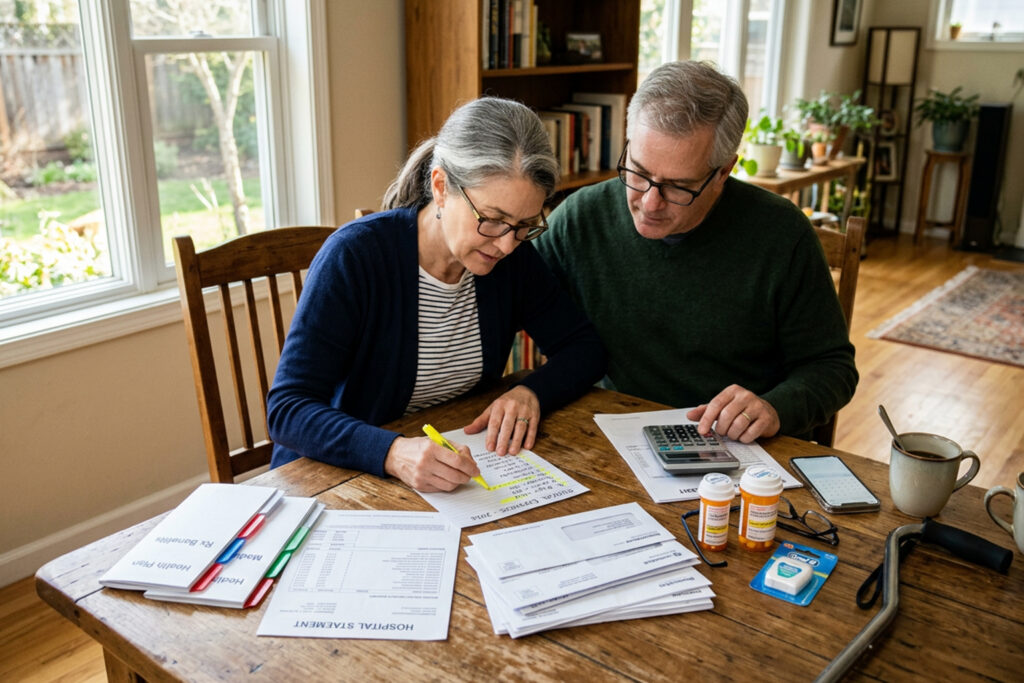
Begin by listing the benefits your primary insurance covers and marking the gaps: deductibles, co-payments, long hospital stays, or outpatient services. Include likely near-term needs such as prescription medication, routine dental work, or planned procedures. Knowing the dollar amounts attached to those gaps helps you compare plans like-for-like. This step prevents buying redundant coverage that adds cost without meaningful extra protection.
Documenting recent medical bills and expected expenses makes choices concrete rather than abstract. Keep those notes handy when reviewing quotes or talking to an agent.
Match coverage to likely needs
Not every extra benefit is worth the same to every person; align options with your personal health picture. For example, if prescriptions are your main expense, a plan that offers lower drug co-pays may be more valuable than broader hospitalization benefits. If mobility or dental work looms ahead, prioritize those riders instead. Aim to cover the highest-probability, highest-cost items first.
- Prescription cost-sharing for chronic meds
- Hospital indemnity for occasional long stays
- Dental and vision for planned maintenance
Focus on a small set of priorities to keep premiums reasonable and benefits targeted. That balance is the heart of smart supplemental planning.
Weigh cost against real benefits
Compare annual premiums against the out-of-pocket exposure each plan reduces. A lower premium can be tempting but might leave you facing large bills for a single event. Look at maximum out-of-pocket limits and what triggers full benefits, not just the headline premium. Also consider how a plan coordinates with other insurance rather than overlaps unnecessarily.
Run simple scenarios: what happens if you need a week-long hospital stay or several months of specialty medication. Those quick calculations reveal which plans truly protect your finances.
Watch for exclusions and timing
Read exclusions carefully and note waiting periods, pre-existing condition clauses, and enrollment windows. Some benefits only start after a waiting period or exclude certain services forever, which can make a policy less useful when you need it. Timing matters: missing an enrollment window can mean limited options or higher costs later. Ask clear questions and get answers in writing when a policy detail is important to you.
Keep renewal dates and annual review reminders on your calendar so coverage still fits your needs next year. A small review each season can save surprises down the road.
Conclusion
Practical supplemental coverage begins with a clear list of gaps and likely expenses. Match benefits to those needs, compare real costs against potential savings, and check exclusions and timing carefully. With focused choices and an annual review, you can secure useful protection without paying for what you don’t need.