Improving your credit doesn’t require dramatic moves or expensive services.
Small, regular choices add up over months.
This article lays out practical daily habits you can adopt without stress.
Follow a few steady routines to see more consistent score gains.
Check Your Credit Reports Regularly
Spend a few minutes each week scanning one credit report or a consolidated view from a free tool. Look specifically for unfamiliar accounts, incorrect balances, or misreported payment dates rather than trying to read every line. When you find an error, document it immediately: note the account, the date, and what looks wrong so you can file a clear dispute. Consistent, small checks make large surprises far less likely when you need credit.
- Set a weekly calendar reminder to review part of a report.
- Keep a short dispute log with dates and responses.
- Save screenshots of items you plan to contest.
Doing this regularly reduces the time and stress involved in corrections. It also helps you spot identity theft early, which preserves your score and peace of mind.
Prioritize On-Time Payments
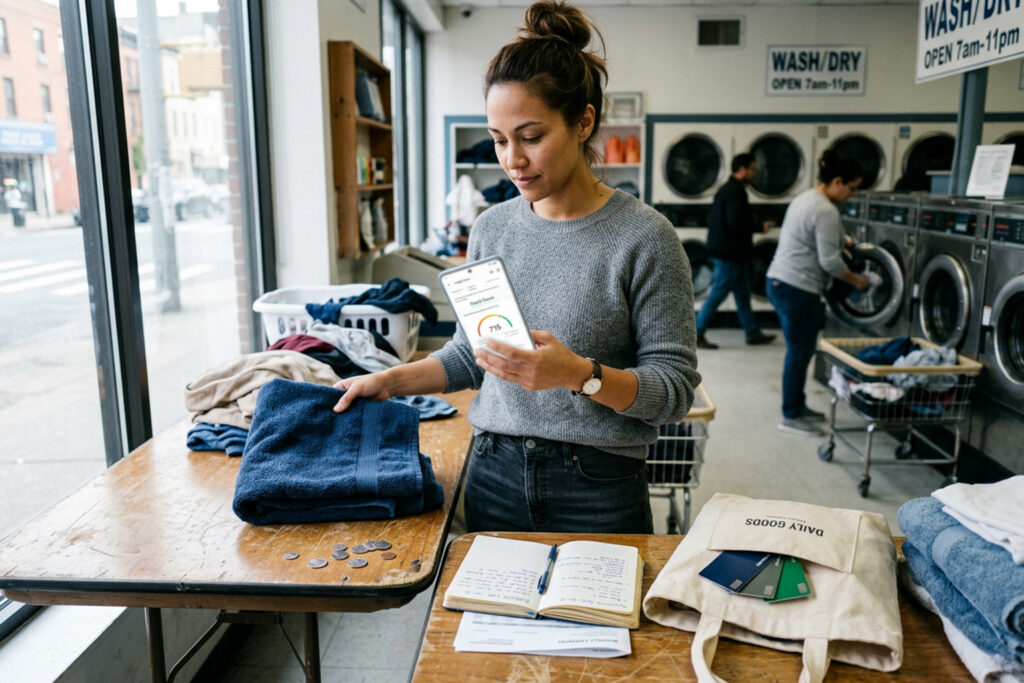
Payment history carries heavy weight in scoring and even a single late mark can linger. Automate at least the minimum payment, and schedule additional payments when cash flow allows so balances move down faster. If bill dates and pay dates don’t align, move payment due dates or split payments into smaller, more frequent transfers. Treat on-time payment as a daily habit: check balances and upcoming due dates during a quick morning or evening routine.
- Set phone alerts a few days before due dates.
- Consider two payments per month to lower reported balances.
Consistent punctual payments are the clearest, most reliable path toward steady score improvement. Small scheduling tweaks can prevent costly mistakes.
Manage Balances and New Credit Carefully
Keep card balances noticeably below limits; aim for well under half of each credit line whenever possible. Scoring looks at both overall utilization and individual account usage, so spreading small balances strategically helps. Avoid opening new accounts purely to raise available credit; new inquiries and account age changes can temporarily lower scores. When you need more room, ask for a credit limit increase instead of applying for another card.
- Make off-cycle payments after big purchases to lower reported utilization.
- Use balance alerts to avoid surprises.
- Pay down the highest-rate balances first to reduce interest drag.
Small, frequent payments and a mindful approach to new accounts protect progress. Managing utilization daily keeps scores from fluctuating wildly.
Conclusion
Small, repeatable actions—checking reports, paying on time, and managing balances—add up into measurable credit progress.
You don’t need perfect finances to improve; you need steady, sensible habits and occasional adjustments.
Start with one daily routine and build from there to maintain upward momentum.