Credit cards don’t have to be chaotic. A short, repeatable monthly routine turns them into reliable tools that save money and reduce stress. This piece lays out concrete steps you can apply within one billing cycle so statements and due dates stop surprising you. Follow a few consistent choices and your cards will serve planned goals instead of impulse habits.
Match Cards to Real Spending
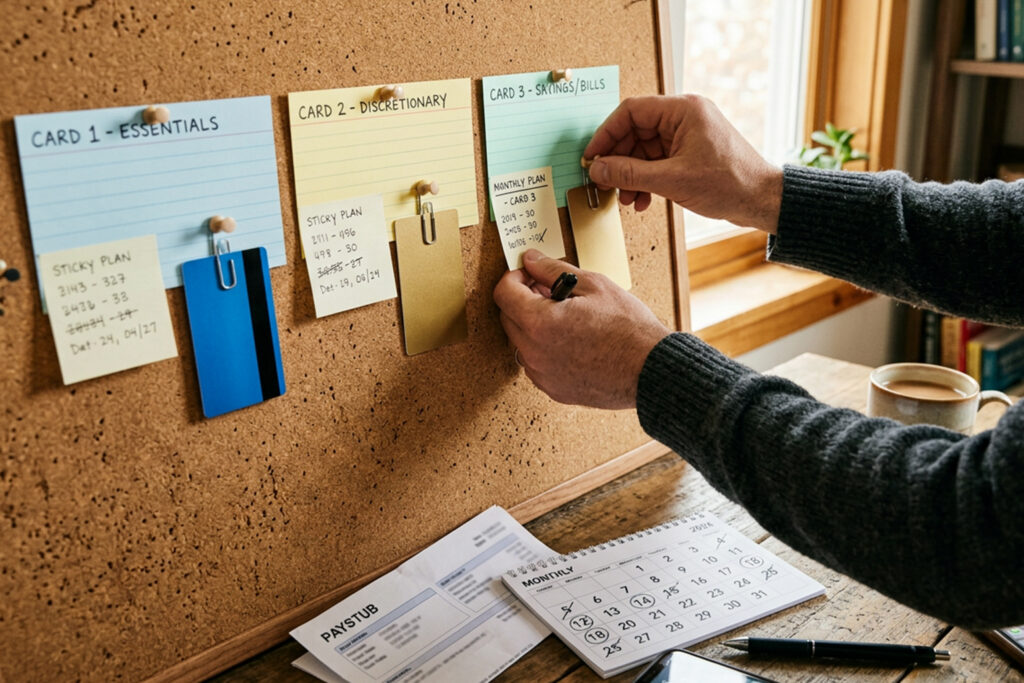
Assign each card a clear purpose that reflects how you actually spend, not what an issuer promises. One card can handle groceries, another subscriptions, and a primary card can take large purchases or anything tied to a preferred rewards category. Keep that setup simple: two or three cards cover most households without fragmenting rewards or tracking. This clarity reduces accidental fee-bearing charges and makes monthly reconciliation straightforward.
When each card has a role, decision-making becomes quick and repeatable rather than ad hoc. You’ll use benefits intentionally and avoid carrying balances on cards that don’t fit the purchase.
Work Billing Cycles Into Your Pay Schedule
Look at statement closing dates and due dates, then slot payments around when money arrives. If a card closes six days before payday, it effectively charges you interest-free for a different window than one that closes after pay. Moving payment amounts between cards or timing large buys to the start of a cycle can extend interest-free periods without extra cost. This approach requires only a short monthly calendar check, not constant micromanagement.
Aligning cycles with paydays smooths cash flow and cuts the temptation to borrow short term at high rates. Over time the small timing tweaks add up to fewer surprises and lower finance charges.
Keep Interest and Fees From Sneaking Up
Prevent fees by setting a low-alert threshold on balances and paying above the minimum whenever possible. Auto-pay for at least the statement balance so you avoid late fees and preserve credit score benefits; then make one extra payment mid-cycle if you carry sizable expenses. Watch for annual fee renewal dates and decide each year whether the rewards justify the cost. A little vigilance each month prevents common culprits from eroding the value of rewards.
Combine alerts with a short monthly review and you unlock predictable outcomes: fewer surprises, clearer tracking of rewards, and less interest paid. Small, repeatable actions beat occasional big fixes.
Conclusion
Pick a simple card purpose plan, align billing with paydays, and guard against fees with auto-pay and alerts. These steps take minutes each month but deliver steady savings and mental space. Predictable habits make credit cards work for you rather than the other way around.