Choosing layers of insurance in retirement can feel overwhelming, but a few focused decisions cut through the noise. Start by identifying gaps in your base coverage and the costs that would hurt your household the most. Think about how often you use services today and how that might change over the next few years. With clear priorities, shopping becomes a practical way to protect savings without piling on unnecessary premiums.
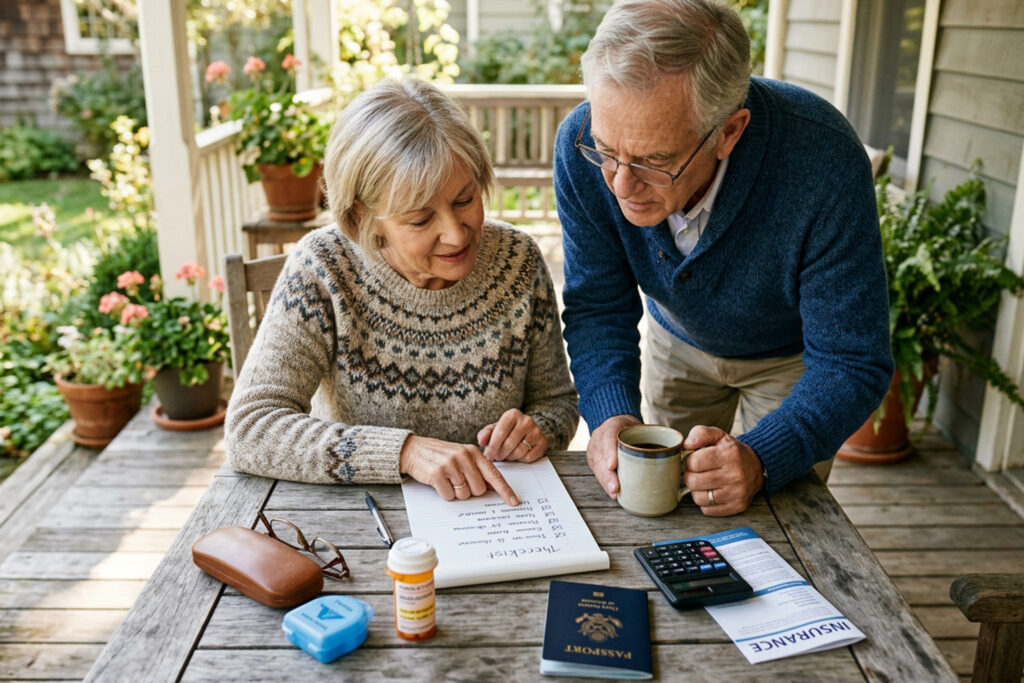
Begin with a short checklist of out-of-pocket risks and current medical needs to guide which policies deserve your attention. Keep that list handy when comparing quotes and benefit details.
Where extra policies fill real gaps
Supplemental plans exist to handle expenses your main plan won’t cover, such as copays, deductibles, or services like dental and vision. Identify the expenses you could not pay comfortably from savings if they happened all at once. For many people, protection against long hospital stays, frequent outpatient visits, or major dental work is most valuable. Don’t assume every add-on is necessary; match benefits to the specific gaps you listed earlier.
Focus on the few benefits that would create real financial relief rather than every possible perk. That keeps premiums reasonable and coverage useful when you need it.
Balancing monthly cost with out-of-pocket risk
Premiums and potential savings trade off: lower monthly cost usually means higher bills when care is needed. Compare typical year scenarios—for example, a year with routine care versus one with surgery—to see which plan saves you money overall. Watch for categories with caps or limits that could leave you exposed in a costly year. Also check whether annual changes or lifetime limits apply, since those details affect real protection.
Run a simple cost comparison for plausible care patterns before you buy. That practical math often reveals the smarter long-term value.
Common add-ons and when they matter
Popular riders include dental, vision, foreign travel, and specific disease riders that cover cancer or chronic illness costs. Dental and vision matter if you already anticipate treatments or replacements, while travel coverage is worth considering if you travel frequently. Disease-specific riders can be expensive and overlap with other coverage, so read exclusions carefully. Avoid riders that pay only small fixed amounts for big risks; those rarely deliver meaningful protection.
Choose a small number of riders tied directly to your likely needs and budget. Unnecessary extras add cost without improving real security.
Conclusion
Prioritize protection for the costs that would derail your finances and skip benefits that don’t match your risks. Compare real-year scenarios and keep your checklist handy during enrollment to stay focused. A small set of well-chosen policies usually beats a larger bundle of marginal extras.