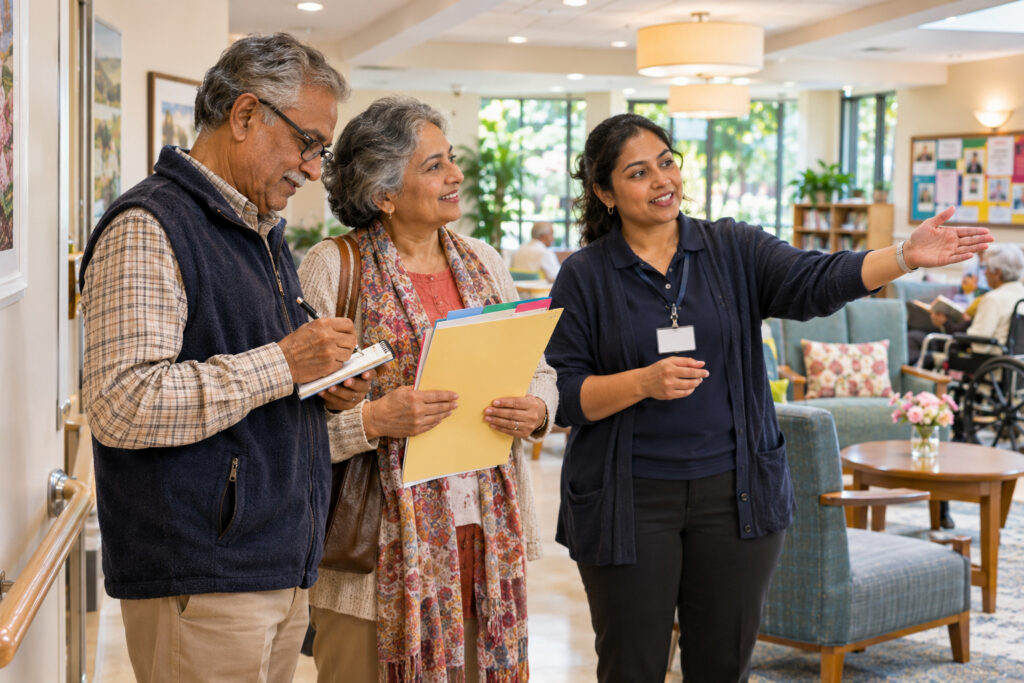
Insurance for later-life care is not a single purchase and forget decision.
Small choices now can reduce stress and expenses down the road.
This article focuses on modest, practical adjustments that make existing policies more useful.
You don’t need to overhaul everything to get better protection.
Assess Your Current Policy
Start by reading the fine print: benefit triggers, daily limits, elimination periods, and any exclusions.
Note whether home care, assisted living, and facility care are treated differently and how inflation adjustments are handled.
If terminology feels dense, request a plain-language summary from your insurer or agent and compare it to what you actually expect to need.
This clarity helps identify gaps without guessing at future needs.
Once you know the gaps, prioritize which shortfalls matter most to you—cost exposure, access to services, or flexibility of care location.
That prioritization will guide whether to add riders, increase benefits, or shop for a new policy.
Small Add-Ons That Matter
Certain riders and add-ons deliver outsized value for relatively little cost.
Common examples include inflation protection, respite care benefits, and shared care for couples.
Another useful option is a return-of-premium rider that refunds some payments if benefits aren’t used.
These features can shift how long a policy will actually support you.
- Inflation protection helps benefits keep pace with rising care costs.
- Respite care offers temporary relief for family caregivers.
- Shared benefits let partners pool coverage when one needs care.
Compare rider costs against the extra protection they provide, and avoid stacking features that duplicate one another.
Select the few that address your most likely gaps.
Timing and Cost Considerations
Age and health influence premium rates, so small choices made earlier often cost less over time.
If you’re healthy, a modest upgrade now can lock in lower premiums for lifetime coverage or a rider.
Conversely, waiting can limit options or increase exclusions if health changes.
Balance short-term budget impacts with the long-term value those changes deliver.
Ask for quotes that show both current premiums and projected increases, and factor those into comparisons.
A clear picture of future costs helps avoid surprises.
How Families Can Coordinate Coverage
Families can reduce gaps by dividing responsibilities and coverage thoughtfully.
One partner might prioritize in-home benefits while another secures facility coverage, or children can coordinate supplemental private pay resources.
Clear communication about expectations prevents duplicated purchases and ensures needs are covered.
Documentation of who will handle claims and contacts speeds access when care is required.
Schedule a family meeting to review policies and name a point person for each insurer.
This simple step eases administration when time and attention are limited.
Conclusion
Small, targeted changes can make an existing policy far more useful.
Focus on practical riders, clear priorities, and family coordination to close coverage gaps.
A modest investment today often pays off in reduced uncertainty and better care options later.