Picking the right credit card can quietly save you hundreds over a year, but it requires paying attention to a few simple details. Start by looking at where you spend most often, then compare common features like annual fees, reward types, and interest rates. A better match between card perks and everyday habits usually outperforms a headline bonus that doesn’t fit your life. This short guide highlights practical steps to lower costs and get more value from the cards you carry.
Match the Card to Your Spending
Not every rewards program suits every wallet. If you spend heavily on groceries and transit, a card that returns higher points in those categories will outperform a general cash-back card with a thin baseline rate. Think beyond introductory bonuses and calculate expected annual returns based on realistic monthly bills. Also check restrictions: some high-earning categories rotate or cap rewards, which can erode the apparent advantage.
Reconcile your priorities before applying: do you want flexible cash back, statement credits, or travel perks? Aligning rewards with regular expenses keeps redemptions simple and valuable. A card that feels natural to use will deliver steady benefit without complex tracking.
Understand Fees, Rates, and Rewards
Fees and interest can wipe out rewards if you carry a balance or pay for benefits you don’t use. Compare annual fees against tangible perks like insurance, extended warranties, or lounge access, and ask whether those extras actually save you money. The card’s purchase APR matters mainly if you sometimes carry balances; a low or 0% introductory APR can be useful but avoid treating it as free money. Read the fine print on reward expiration, redemption minimums, and foreign transaction fees.
- Check whether the rewards convert to statement credits or have travel blackout dates.
- Watch for caps on bonus categories and limits on total points earned.
- Confirm how long introductory rates and bonus offers last before they revert.
When in doubt, run a one-year cost-benefit comparison: add expected rewards, subtract fees and typical interest, and see which card comes out ahead. Repeat annually since offers and your habits change.
Using Cards Wisely to Protect Credit
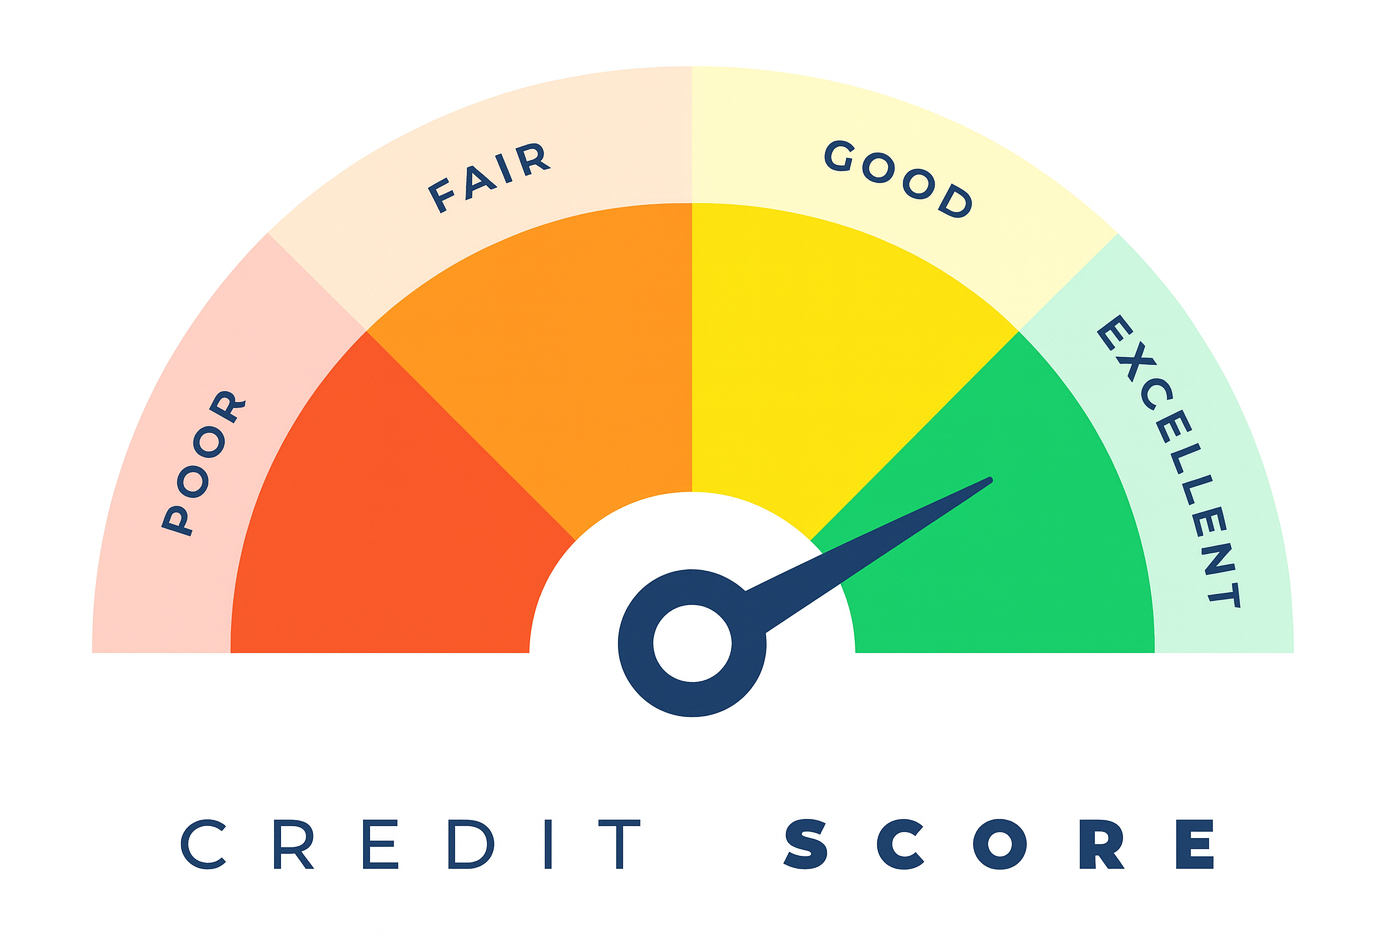
Responsible use preserves the benefits cards offer. Make on-time payments to avoid late fees and credit damage; set autopay or calendar reminders to stay current. Keep credit utilization low by spreading balances across cards or paying midway through the month, which helps your score without changing spending. Consider a small recurring charge you can pay off each month to keep older accounts active and credit history steady.
Finally, review statements regularly for errors or unauthorized charges and dispute anything suspicious quickly. Periodic account reviews can reveal better offers or prompt you to downgrade a card whose annual fee no longer makes sense.
Conclusion
Choosing a credit card is a practical exercise in matching benefits to real spending and habits. Focus on fees, reward structure, and habits rather than marketing slogans. Small adjustments in card selection and use can produce meaningful annual savings and better financial flexibility.