Getting Started
Choosing the right insurance as you approach retirement means thinking beyond the monthly premium. Look at what a plan actually pays for: doctor visits, hospital stays, prescriptions, and out-of-pocket caps. Track the providers you and your family use most and see whether they are in-network under each option. Consider how your health needs might change in the next five years and build some flexibility into your decision.
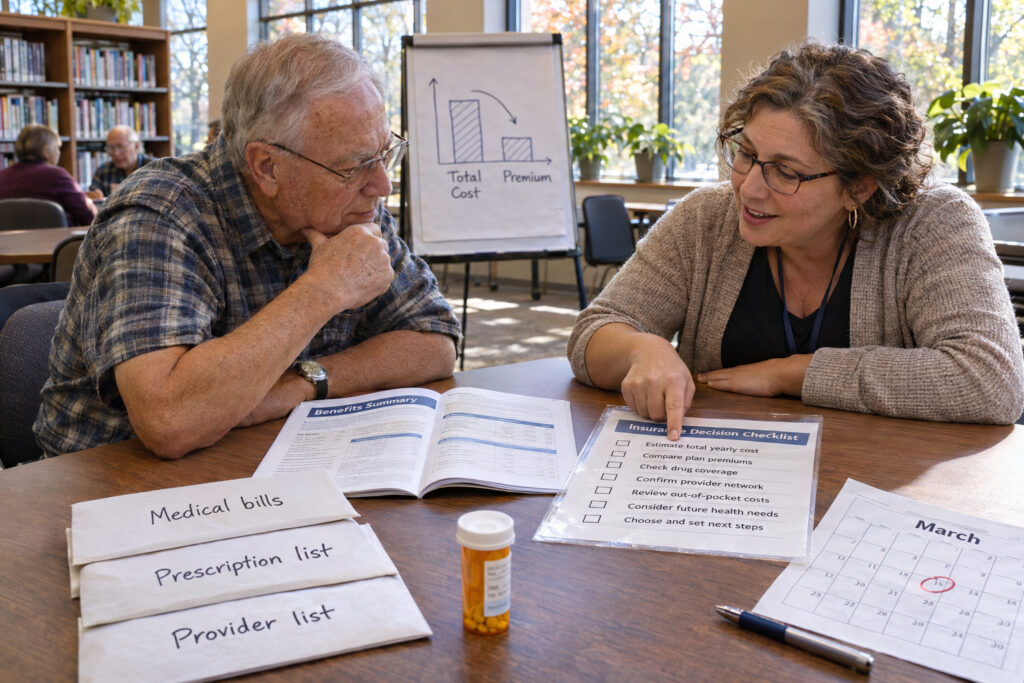
Start by gathering your recent medical bills, a current medication list, and notes on any planned procedures. Small upfront work can prevent big surprises later.
Compare What Matters Most
Premiums are easy to compare, but total yearly cost is what matters: premiums plus deductibles, copays, coinsurance and any limits on benefits. Check prescription formularies closely; a low-premium plan can become expensive if it places your regular drugs on a non-preferred tier. Pay attention to network breadth and whether specialists you trust are covered without referrals. Also review annual out-of-pocket maximums so you know the worst-case exposure for a severe illness.
Run a simple cost scenario for typical and worst-case years to see which plan holds up. That practical comparison often reveals hidden trade-offs.
Watch for Common Pitfalls
Avoid choosing a plan based only on one factor like price or a single good benefit. Enrollment deadlines and special enrollment rules vary by plan type, and missing a window can lock you into a plan for a year. Beware of aggressive sales tactics promising benefits that aren’t guaranteed; always read the fine print and official notices. Finally, don’t forget to reassess coverage annually when carriers publish their changes for the next year.
- Don’t assume a favorite doctor remains in-network.
- Don’t ignore the drug formulary when comparing plans.
- Don’t forget the impact of supplemental plans on total cost.
Staying cautious about these pitfalls will reduce the chance of costly surprises. A little diligence pays off.
Practical Steps Before You Enroll
Make a short checklist: collect your provider list, write down drug names and dosages, and estimate annual usage of services like physical therapy. Use plan comparison tools and ask for a benefits summary that shows typical member costs for common services. Consider consulting a licensed advisor or a nonprofit counselor if the choices feel overwhelming. Finally, plan for premium increases by checking the carrier’s recent rate history.
Taking these concrete steps will help you pick a plan suited to both your health and your budget. It reduces uncertainty and gives you confidence at enrollment time.
Conclusion
Focus on total cost and real access to care rather than a single metric. Prepare a short, factual checklist before comparing options. Review your choice annually to avoid unwelcome surprises.