Improving a credit score is a gradual process that rewards consistent, informed choices.
This article outlines practical steps you can apply month by month to build healthier credit.
Small changes in payment timing, credit usage, and monitoring add up over time.
Use these methods to create a steady plan that fits your financial life.
Check and Understand Your Reports
Start by obtaining your credit reports and reviewing them carefully for errors and unfamiliar accounts. Dispute inaccuracies promptly and note any accounts that appear overdue or incorrectly reported. Understanding what contributes to your score—payment history, utilization, length of history, new accounts, and mix—lets you prioritize actions. Regular review also helps you spot potential identity theft early.
Keep a simple log of any disputes and follow up until resolved. This foundation reduces surprises and guides your next steps.
Prioritize Payments and Balances
On-time payments have the largest single impact on many scoring models; set up reminders or autopay to avoid missed due dates. If possible, pay balances in full each month to minimize interest and lower credit utilization. When paying minimums only, focus extra payments on high-interest or high-utilization accounts to improve your utilization ratio faster. Even small extra payments can reduce reported balances and support steady score gains.
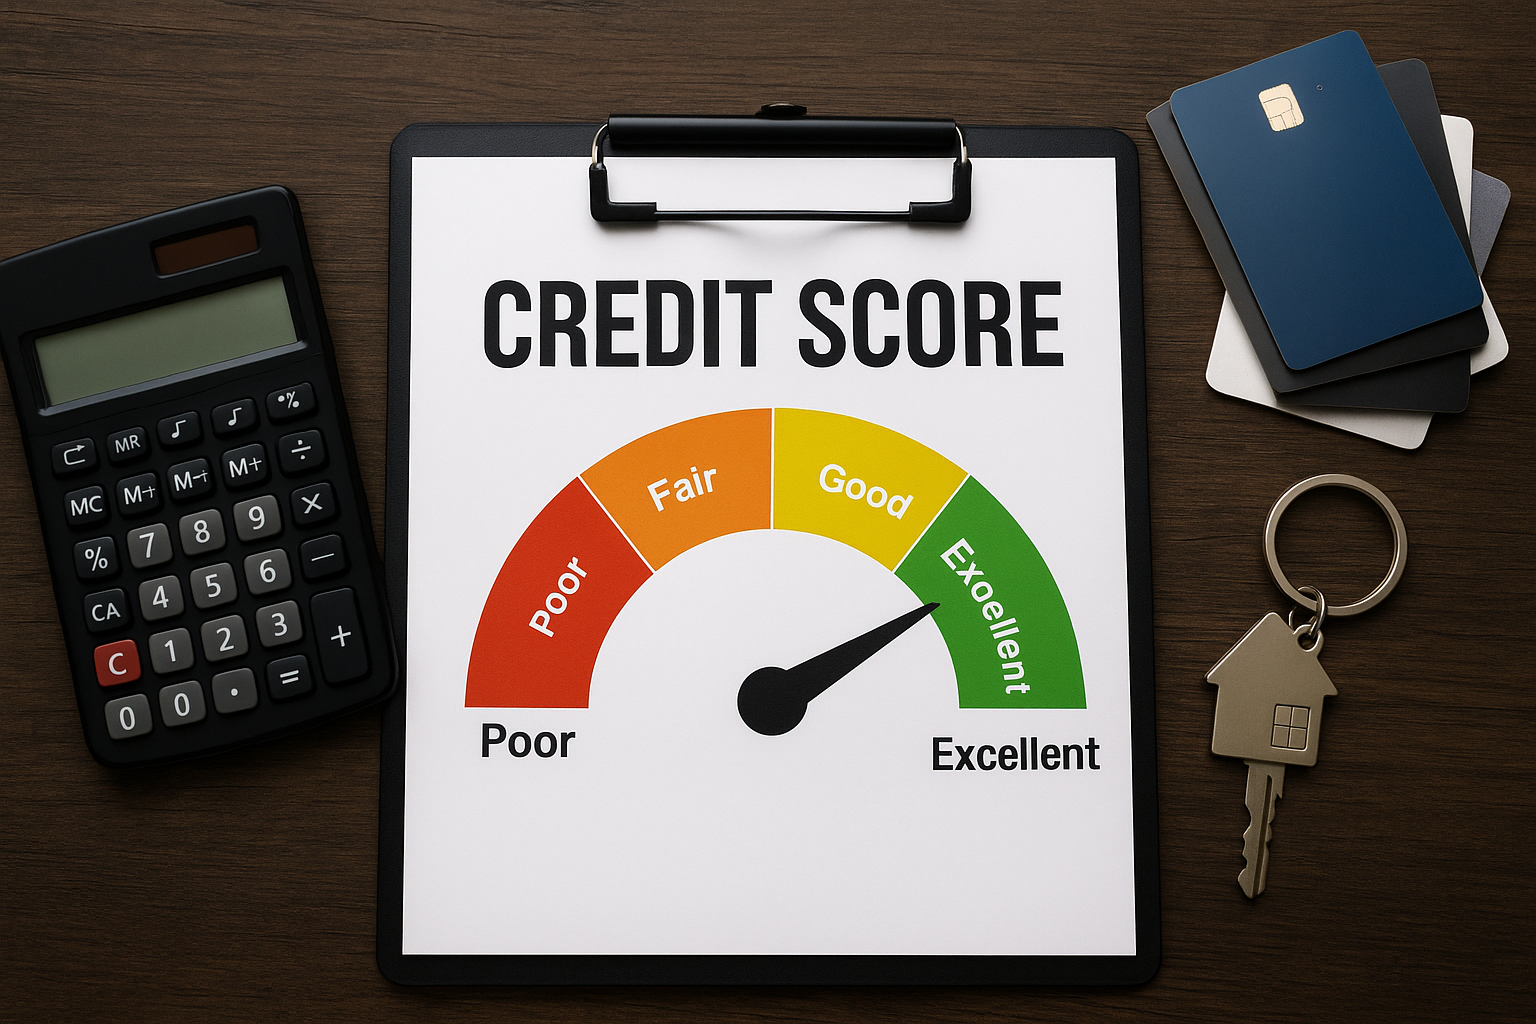
Aim to keep utilization below 30%, and ideally much lower on individual cards. Consistent payment habits compound positively over time.
Use Credit Tools Strategically
Tools like secured cards, credit-builder loans, or authorized-user status can help establish or rebuild positive history when used responsibly. Avoid opening many new accounts at once, since hard inquiries and short average age of accounts can temporarily lower scores. Maintain older accounts open unless fees outweigh benefits, because length of history matters. Regularly checking a soft-score snapshot lets you track progress without harming your credit.
Combine these tools with disciplined payment behavior to see lasting improvement. Make incremental adjustments rather than radical moves.
Plan for Long-Term Credit Health
Create a long-term plan that aligns credit-building actions with broader financial goals such as saving and debt reduction. Maintain an emergency fund to avoid relying on credit for unexpected expenses, which can destabilize progress. Regularly review where you stand against your plan and adjust priorities when life events change income or expenses. Remember that steady, predictable improvements are more sustainable than aggressive short-term tactics that may carry risk.
Set measurable milestones, such as lowering utilization by a set percentage or achieving consecutive on-time payments. Celebrate progress and recalibrate when needed to keep momentum without taking unnecessary risk.
Conclusion
Improving credit is a marathon, not a sprint.
Prioritize accuracy, timely payments, and manageable balances.
With steady habits, your score will reflect your financial discipline.