Small Predictable Steps to Reduce Credit Risk and Improve Scores

Improving your credit score doesn’t require a big reset or complicated tricks. Small, repeatable actions often move the needle more reliably than dramatic one-off efforts. This piece breaks down practical steps you can add to your routine that lower risk and help scores recover. Read on for clear tactics that fit into an ordinary month.

Prioritize on-time payments

Payment history is the backbone of most scoring models, so a single habit change—paying on time—has outsized benefits. Automate at least the minimum payment on each account and set calendar reminders a few days before due dates to avoid accidental late posts. If a payment will be late, contact your lender; some will agree to a one-time grace or waive a fee and not report a late payment. Repeated punctuality builds a clean record that signals low credit risk.

Consistency beats perfection here: missing one payment is forgivable, but habits shape how accounts are viewed. Make punctuality part of a broader money routine and keep momentum by reviewing upcoming bills weekly.

Trim your credit utilization

High balances relative to limits can weigh down a score even when payments are timely. Aim to keep revolving utilization under roughly 30%, and lower if you can—single-digit utilization helps more. If balances spike occasionally, ask for a credit limit increase or move purchases to a card with more available space. Small transfers or shifting recurring charges between cards can also balance utilization without new credit.

  • Set a reminder to check card balances mid-cycle.
  • Make a small extra payment before the statement closes.

These minor scheduling tweaks keep reported balances lower and show lenders you manage available credit responsibly.

Keep accounts open and check your reports

Length of credit history and account mix matter, so closing oldest cards can unintentionally hurt scores. Keep accounts you use occasionally active by running a small automated charge and paying it off. Regularly review your credit reports to spot errors like incorrect balances or unfamiliar accounts that could damage your profile.

Disputing mistakes promptly often leads to quick fixes, and maintaining a long, active record supports long-term score improvement. Small, routine checks prevent surprises when you need credit.

Use small wins to rebuild trust

If your score has setbacks, start with achievable actions: on-time payments, reduced utilization, and correcting report errors. Consider a secured card or a credit-builder loan if access is limited—these products can create positive entries when managed responsibly. The goal is steady, verifiable improvements rather than rapid fixes that might carry risk.

Track progress monthly and celebrate milestones like a single clean year of payments. Over time, those small wins add up into meaningful credit repair.

Conclusion

Small, predictable steps compound into measurable credit improvement over months. Commit to on-time payments, lower utilization, and routine report checks. These modest habits reduce risk and help scores rise steadily.
Smart Payment Rhythms to Strengthen Your Credit Score

Credit scores move slowly, but deliberate payment habits make a measurable difference. Small shifts in when and how you pay can cut utilization, prevent late marks, and show steady responsibility. You don’t need a dramatic overhaul—consistency and clarity in payment timing often do the heavy lifting. This piece lays out clear, practical timing strategies you can adopt without stress.

Start with predictable actions and watch modest gains stack up over months rather than overnight. The rest of the article breaks the approach into focused steps you can try immediately.

Set payment dates that suit your cash flow

Aligning card due dates with payday removes friction and reduces missed payments. Call your card issuer or use the online settings to shift due dates to a few days after you get paid. That small calendar change lowers the odds of carrying unexpected balances and helps keep each account current. It also makes it easier to automate payments without worrying about overdrafts.

Once dates match your schedule, automate at least the minimum payment. Automation preserves the rhythm and protects your score from accidental slips.

Lower utilization by splitting payments

High utilization can dent your score even when you pay in full each month. Paying in two smaller chunks—mid-cycle and before the statement closing date—keeps reported balances low. This tactic reduces the percentage of available credit you’re using when issuers report to bureaus. It’s especially useful on cards with large limits or seasonal spending spikes.

  • Make a mid-cycle payment to cut the balance before it’s reported.
  • Clear remaining charges before the statement closes to show a low balance.

These moves take a few extra minutes monthly but can improve the utilization slice of your score fairly quickly. Consider calendar alerts to keep the rhythm consistent.

Use automation smartly and review regularly

Automatic payments reduce human error but aren’t a set-and-forget cure. Schedule automatic payments for fixed amounts and check statements monthly for surprise charges or billing errors. Review your autopay settings after any change in income or card activity so you don’t overdraw your bank. Regular checks keep automation working in your favor rather than creating new problems.

Combine automation with spot checks to catch anomalies early. That balance preserves convenience while guarding your credit health.

Conclusion

Consistent timing choices—matching due dates to paydays, splitting payments, and smart automation—build a positive credit narrative. These habits reduce late payments and lower reported balances, two factors that improve scoring behavior. Start with one change this month and add another next month to maintain momentum.

Quiet Ways to Improve Your Credit Without Stress

Improving your credit doesn’t require dramatic moves or risky shortcuts.
Small consistent choices — a few smart payments, a little attention to balances, and a simple plan — can change how lenders view you.
This article lays out clear, manageable steps you can take on a regular basis to nudge your score upward.
No jargon, no pressure; just practical actions you can start this week.

Understand the Pieces That Move Your Score

Your credit score is a composite of several factors: payment history, the amount you owe relative to limits, the length of your accounts, new credit activity, and the mix of accounts you hold.
Payment history typically carries the most weight, so a single missed payment can have an outsized effect.
Credit utilization — how much of your available credit you use — often responds quickly to changes and is something you can influence within a month or two.
Knowing which pieces matter most helps you prioritize actions that produce the biggest benefits.

Start by pulling a free credit report or checking a score dashboard so you know where you stand.
That snapshot tells you whether to focus on on-time payments, lowering balances, or correcting inaccuracies.

Practical Payment Habits That Add Up

Paying on time is the single simplest habit to form: set reminders, use autopay, or schedule payments right after payday.
If you struggle with large monthly minimums, make multiple smaller payments across the month to keep balances and utilization lower.
When possible, pay more than the minimum — reducing principal faster lowers interest costs and shortens the time you carry debt.
Regularly review due dates and consider aligning them with income cycles so missed payments become less likely.

Even modest extra payments can make a measurable difference over time.
Consistency beats perfection: steady on-time payments rebuild confidence in your credit profile.

Manage Credit Use and Accounts Wisely

Keep older accounts open when it makes sense; the age of accounts contributes positively to your score.
Avoid opening multiple new accounts in a short period — each application can cause a small, temporary dip.
If your utilization is high, ask for a credit limit increase or pay down balances focused on cards with the highest percentage used.
If you find errors on your report, dispute them promptly: correcting mistakes can restore points you didn’t even know you lost.

  • Target utilization below roughly 30% overall and lower on individual cards.
  • Request limit increases only when your financial behavior supports it.
  • Dispute inaccuracies with documentation for faster resolution.

Small account-management decisions compound over months.
Handle accounts thoughtfully and your score will reflect that steadiness.

Conclusion

Improving credit is more about steady habits than dramatic fixes.
Focus on timely payments, sensible use of available credit, and correcting errors.
Those quiet, consistent moves will yield clearer options and better terms over time.

Smart Steps For Gradual, Sustainable Credit Improvement

Improving a credit score rarely happens overnight.
Small, consistent actions compound into meaningful change.
This article outlines practical steps you can use each month to make steady progress.
The focus is on sustainable habits that protect your financial reputation while avoiding risky shortcuts.

Why your credit score changes matter

Your credit score affects more than loan rates; it influences rental approvals, insurance premiums, and sometimes job screening processes. Small point gains can translate into significant savings over time, so incremental improvement is worth pursuing. Understanding the components of your score—payment history, utilization, length of history, new credit, and account mix—helps you target the most effective actions. Prioritizing the areas with the biggest impact will accelerate progress without unnecessary complexity.

Start by reviewing your credit report for errors and unfamiliar accounts, as inaccuracies can drag your score down. Regular monitoring helps you catch identity issues and verify that improvements are reflected in your profile.

Concrete actions to raise your score

Focus on three to five repeatable behaviors that fit your budget and schedule so improvement becomes automatic. Pay on time every month and set reminders or autopay for at least the minimum due to avoid late payments that harm your score. Lower your credit utilization by paying down balances and keeping card usage well below available limits. Avoid opening multiple new accounts in a short span, which can temporarily reduce your average account age and trigger inquiries.

  • Pay bills by or before the due date to protect payment history.
  • Target utilization under 30 percent, and ideally under 10 percent for faster gains.
  • Keep older accounts open to maintain length of history when it makes sense.

Combine these actions into a simple monthly routine: check balances, schedule payments, and review one line item on your credit report. Over time this disciplined approach builds a stronger, more resilient score.

Staying on track and avoiding setbacks

Set realistic milestones and celebrate small wins to maintain motivation during a multi-month process. If you face a financial setback, communicate with lenders—many offer hardship plans that prevent late payments from being reported. Re-evaluate your budget periodically to ensure you can sustain the behaviors that drive improvement. Use alerts and automatic transfers to reduce the chance of human error undermining progress.

Persistence matters more than perfection; a short misstep can be corrected with consistent follow-up. Keep learning and adjust strategies as your credit situation evolves.

Conclusion

Gradual credit improvement relies on repeatable, manageable habits.
Focus on timely payments, sensible utilization, and regular monitoring.
With a consistent approach, your score will reflect steady, lasting gains.

Quarterly Actions to Strengthen Your Credit Profile

Improving a credit score doesn’t require dramatic moves overnight.
Small, well-timed adjustments each quarter can add sustained improvements.
This approach focuses on measurable tasks and routine reviews.
The result is gradual but reliable progress toward stronger credit.

Assess Your Starting Point

Begin by pulling your credit reports and reviewing key metrics such as balances, recent inquiries, and open account ages. Look for anomalies, missed payments, or accounts you no longer use that may be dragging your profile down. Understanding where your score currently stands helps you prioritize actions that will have the biggest impact. Aim to document three to five areas to address over the next quarter.

  • Track current utilization per card and overall.
  • Note any late payments or collections.
  • Record account ages and recent openings.

Having a clear snapshot makes quarterly planning practical and focused. Use this as your baseline for measuring progress at the end of the period.

Set Quarterly Targets and Routines

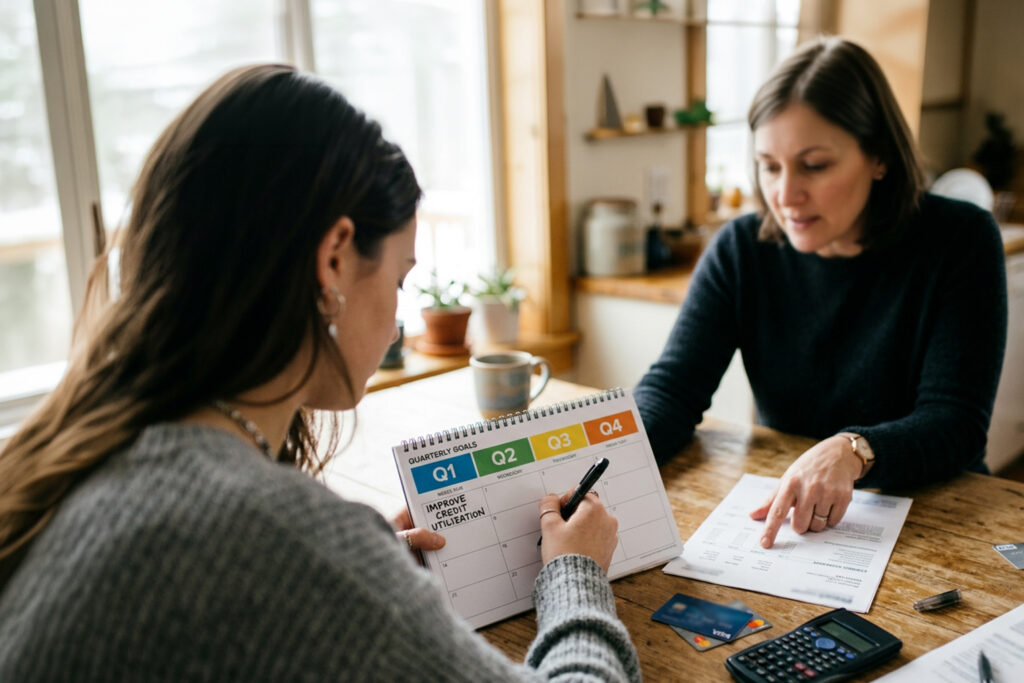
Create specific, achievable targets for a 90-day window instead of vague resolutions. Examples include reducing overall utilization by a set percentage, disputing errors, or bringing a delinquent account current. Schedule recurring reminders to check balances and due dates so small habits become consistent. Regular, modest wins compound and protect your score against setbacks.

  • Target a utilization drop of 5–10% per quarter.
  • Plan one dispute or verification task each month.

These routines help maintain momentum without overwhelming your schedule. Quarterly reviews let you adjust targets based on real results.

Reduce Balances and Optimize Utilization

Lowering credit utilization is one of the most effective short-term levers to improve scores. Focus payments on higher-rate or high-balance cards first while preserving on-time payments across all accounts. Consider small balance transfers only when fees and terms clearly support savings over time. Avoid opening new accounts solely to increase available credit without a repayment plan.

  • Prioritize payments to reduce the highest utilization lines.
  • Keep at least a couple of accounts with low balances to show responsible use.

Consistency matters: make steady payments each billing cycle and avoid maxing out cards. Over several quarters, utilization improvements can produce measurable score gains.

Monitor Reports and Manage Errors

Set a habit of reviewing one report per month so you cover all bureaus each quarter. Dispute inaccuracies promptly and follow up until they are resolved to prevent lingering negative effects. Also monitor for unauthorized activity and freeze or lock accounts when appropriate. Regular monitoring reduces surprises and supports sustained improvement.

Document each dispute and the outcomes to build a clear history. This record helps if issues reappear or require further escalation.

Conclusion

Quarterly planning turns abstract goals into manageable actions.
Small, consistent improvements compound into meaningful score changes over time.
Stay disciplined, track progress, and adjust targets each quarter.

Timing and Organization Habits That Boost Credit Scores

Small changes in how you schedule payments and organize accounts can have a meaningful impact on your credit score. Reviewing reports regularly and aligning due dates with pay cycles reduces the risk of late payments and high utilization. This article focuses on practical timing and organization habits that drive steady improvement. Implementing these habits consistently creates measurable momentum over months.

Check Your Reports and Prioritize Corrections

Start by obtaining your credit reports and reviewing them for inaccuracies, outdated items, or unfamiliar accounts. Look for errors in balances, payment histories, and personal details, and file disputes promptly when you find mistakes. Correcting inaccuracies can remove unjust negative items and sometimes boost your score quickly. Keep a log of disputes and responses so you can follow up without losing track.

Prioritizing corrections also helps you target the most impactful problems first, such as late payments and high balances. Regular maintenance prevents small issues from becoming long-term blemishes on your file. Treat report review as a monthly habit to stay ahead.

Adjust Payment Timing and Reduce Balances

Payment timing affects both on-time status and reported utilization, so align due dates with your cash flow when possible. Paying before the statement closing date lowers the balance that is reported to creditors, which can improve utilization ratios. Even modest reductions in reported balances often translate into visible score changes. Automating payments or setting reminders reduces the chance of missed due dates.

  • Set payments a few days before the statement closing date to lower reported balances.
  • Make multiple smaller payments throughout the month to keep utilization low.

These adjustments are simple to implement and compound over time, making credit healthier without major lifestyle changes. They also reduce stress by keeping accounts in better standing.

Manage New Accounts, Credit Mix, and Monitoring

Opening new accounts can help diversify your mix but may temporarily lower your score due to inquiries, so plan additions strategically. Focus on maintaining older accounts in good standing and avoid unnecessary applications. Use credit monitoring tools to track changes and receive alerts for unusual activity or balance spikes. Monitoring gives you time to respond before issues escalate.

Balance new account benefits with the short-term impact of inquiries, and opt for secured or low-limit additions if you need to build history. A thoughtful approach to account management supports steady score growth.

Conclusion

Organize payments, review reports, and monitor activity regularly to influence your score in measurable ways.
Make small timing adjustments and automate where possible to reduce errors and reported balances.
Consistent habits create steady improvements that compound into long-term credit health.

A Clear Plan for Improving and Maintaining Credit Health

Understanding your credit profile is the first step toward measurable improvement. Start by pulling your credit reports and noting any errors, balances, and account ages that influence your score. Knowing which factors carry the most weight helps you prioritize actions that deliver the fastest gains. This approach keeps improvement structured, manageable, and trackable over time.

Assess Your Current Credit Picture

Begin with a clear snapshot: current scores, recent inquiries, and the status of all open accounts. Look for reporting mistakes, outdated collection entries, or duplicated accounts that can be disputed. Identify high-balance cards or accounts nearing limits because utilization is often the quickest lever to pull. A focused assessment shows where small changes will have the largest impact.

  • Order reports from major bureaus and compare line by line.
  • Flag inaccuracies and prepare documentation for disputes.
  • Note accounts with high utilization or missed payments.

Once you’ve cataloged the issues, assign priorities and timelines for each item. This turns an overwhelming list into a set of achievable tasks that you can track weekly and monthly.

Targeted Actions That Move the Needle

Paying down high interest and near-limit balances can reduce utilization quickly and often raises scores within a billing cycle. Bring past-due accounts current to stop ongoing negative reporting and consider negotiating with collectors for goodwill adjustments where appropriate. Avoid opening new credit lines unless needed, since hard inquiries and short account age can suppress gains. Use targeted payments to address the most impactful items first.

  • Focus on cards with utilization above 30%.
  • Set up payment reminders or automatic transfers.
  • Consider reallocating payments to accelerate payoff.

Tactical payments and selective dispute actions yield measurable results without wholesale changes to your finances. Keep momentum by celebrating small wins and adjusting the plan as scores respond.

Maintain Momentum With Smart Routines

Sustained credit health depends on consistent habits: on-time payments, low utilization, and periodic report reviews. Automate minimum or full payments to avoid late marks, and schedule a quarterly review of your reports for new errors or fraud. Keep older, healthy accounts open to preserve average account age and be cautious with new credit applications. Over time, consistent behavior compounds into stronger, more resilient scores.

  • Automate payments for key accounts each month.
  • Check reports quarterly and freeze or monitor for fraud.
  • Use credit-building tools sparingly and strategically.

Routines reduce the chance of setbacks and make progress predictable. Revisit goals every three to six months and refine tactics based on results.

Conclusion

Improving credit is a process of clear assessment, targeted actions, and consistent routines. Small, prioritized steps often produce the clearest, quickest improvements while minimizing disruption. With a plan and regular reviews, better credit becomes a sustainable outcome rather than a one-time fix.

Monthly Habits That Gradually Rebuild Your Credit Score

Rebuilding credit is less about one big move and more about consistent monthly habits.
Small, deliberate actions compound over time to repair missed payments, lower balances, and demonstrate reliability.
This article outlines practical steps to take each month so progress is measurable and steady.
Follow these habits and adjust as needed to fit your budget and credit goals.

Review and Understand Your Credit Reports

Get your credit reports from the major bureaus and review them carefully for errors, outdated entries, or accounts you don’t recognize. Disputing inaccuracies can remove negative items that drag your score down, and understanding the reports helps you target the right behaviors. Look at the details: payment history, credit utilization, account age, and types of credit. This knowledge makes monthly planning more effective.

Schedule a quarterly check to catch issues early and note any changes in your credit mix. Early detection prevents surprises and supports steady improvement.

Prioritize On-Time Payments and Lower Utilization

Consistently paying on time is the single most influential habit for rebuilding credit, so set up autopay or calendar reminders to avoid late payments. Aim to pay more than the minimum when possible to reduce interest and shorten the repayment timeline. Keep credit utilization low by paying down revolving balances and, if feasible, requesting small credit line increases rather than opening new accounts. Lower utilization and a spotless payment record together signal lower risk to lenders.

Even modest extra payments each month accelerate progress and improve your utilization ratio. Over time, these changes strengthen your credit profile.

Use Credit-Building Tools Strategically

Consider credit-building tools like secured credit cards or a credit-builder loan to demonstrate responsible borrowing when traditional credit is limited. Becoming an authorized user on a seasoned account can help if the primary user has strong history. Avoid frequent hard inquiries and new accounts that can temporarily lower your score. Use these tools with discipline and a clear plan for repayment.

Choose one or two tools that match your needs and commit to monthly, predictable behavior with them. Consistency pays off more than chasing quick fixes.

Avoid Common Pitfalls and Stay Patient

Resist the urge to open multiple new accounts rapidly; each hard inquiry and short-lived account can temporarily nudge your score downward. Be wary of high-interest rescue products and pay-day style options that promise fast improvement but trap you in cycles of debt. Maintain an emergency buffer so monthly payments remain on track during unexpected expenses. Patience matters: many positive changes need several months to reflect on reporting cycles and update scores.

Set realistic timelines and track small wins monthly to stay motivated. Slow, steady improvements are the most durable route to stronger credit.

Conclusion

Rebuilding credit takes time, but reliable monthly habits produce measurable results.
Focus on accurate reporting, timely payments, and responsible use of credit tools.
Regular review and small improvements will build lasting credit strength.

How to Prioritize Credit Tasks for Lasting Score Gains

Improving your credit score is a process that rewards consistency and focus. Small, well-chosen tasks completed regularly can compound into meaningful gains over time. This article explains how to prioritize the most impactful actions so you spend effort where it counts. Read on for a practical framework you can apply each month.

Understand the components that drive scores

Credit scores are influenced by a handful of measurable factors, each with different weight. Payment history, credit utilization, length of credit history, recent activity, and account mix all matter, but the relative importance varies by scoring model. Focusing on on-time payments and keeping balances low typically delivers the fastest improvement. Identifying which factor is weakest for your profile helps you set priorities.

Start by pulling a recent credit report and a score summary to see where you stand. Track one or two metrics rather than trying to address everything at once. This targeted approach helps preserve momentum and avoid frustration.

Prioritize high-impact, low-effort actions

Not all credit actions deliver equal returns for the time invested. Making every payment on time and reducing utilization below 30% are high-impact moves that require modest ongoing effort. Small, regular payments and automated reminders cut missed payments dramatically. Meanwhile, opening or closing accounts should be judged more carefully because those changes can shift your overall profile in complex ways.

Build routines that remove friction: autopay for recurring bills, alerts for due dates, and a simple spreadsheet or app to monitor balances. Consistency beats sporadic, intensive efforts when improving credit over months.

Monthly checklist to keep progress steady

A concise monthly checklist keeps priorities visible and manageable. Limit it to a few items that address payment timeliness, balances, and monitoring. Check progress monthly so you can adjust focus without becoming overwhelmed by detail.

  • Confirm all payments are scheduled and on time.
  • Bring credit card utilization under targeted thresholds.
  • Review recent inquiries and new accounts for errors.
  • Set aside a small buffer to avoid missed payments.
  • Note any large upcoming expenses and plan accordingly.

Use this checklist as a habits scaffold rather than an inflexible rule set. Over time you can tighten targets as individual metrics improve.

Common mistakes and how to avoid them

People often chase the newest hack instead of reinforcing basics; opening multiple accounts or closing old ones can backfire. Another frequent error is neglecting monitoring, which allows errors or fraud to persist. Finally, reacting impulsively to short-term score changes can lead to decisions that harm long-term stability.

Focus on regular maintenance and verify changes with data from your credit report. When in doubt, prioritize actions that support steady improvements rather than quick fixes.

Conclusion

Prioritizing payment reliability and sensible utilization produces the most consistent score gains. A short monthly checklist and simple automation keep progress sustainable. Small, repeatable actions add up to lasting improvement.

Daily Credit Habits That Build Long-Term Strength

Improving your credit score is less about dramatic moves and more about consistent daily choices. Small actions repeated over time create a stronger credit profile and more financial options. This article outlines practical habits you can adopt now and maintain to see steady progress. Use these steps as a foundation for sustainable credit health.

Why consistent habits matter

Credit scoring models reward patterns that indicate reliability and responsible behavior. Lenders look for a history of on-time payments, balanced utilization, and stable account management. Sporadic fixes or one-off payments rarely shift the trend your report displays to creditors. Building a dependable routine produces measurable improvements in both short- and long-term scoring factors.

Adopting manageable daily and monthly practices reduces stress and prevents reactive financial decisions. Over time these habits compound into meaningful score changes and better borrowing choices.

Simple daily and monthly routines

Consistent review and small actions make a big difference. Checking your accounts daily for upcoming payments, setting payment reminders, and scheduling transfers keep balances under control. Monthly tasks like paying more than the minimum and keeping card balances low relative to limits directly influence utilization metrics.

  • Set automated payments for recurring bills to avoid late marks.
  • Use calendar alerts a week before due dates for discretionary bills.
  • Keep credit utilization under 30%, ideally below 10% for faster gains.

These routines require minimal time but protect your score from avoidable dips. Consistency is the key to turning these actions into reliable credit signals.

Managing accounts and credit mix

How you manage different types of credit affects scoring models. Maintain older accounts open when they don’t cost you fees, since account age contributes to your profile strength. Be cautious when opening new lines; each application can cause a brief inquiry that may slightly lower your score.

Balancing installment loans and revolving credit can help, but only take on what fits your budget. Thoughtful account management preserves history and reduces risk of sudden negative events.

Monitor reports and correct errors promptly

Regularly reviewing your credit reports helps catch inaccuracies, fraudulent accounts, or misreported payments early. Disputing errors and following up with creditors can restore accurate information and prevent unnecessary score damage. Monitoring tools and annual report checks offer visibility into how daily habits translate into scoring changes.

Address discrepancies as soon as you spot them and document communications. Quick correction maintains the integrity of your credit history and supports long-term improvement.

Conclusion

Small, repeatable actions—on-time payments, controlled utilization, and mindful account management—create reliable credit momentum. Regular monitoring and correcting errors ensure your progress isn’t undermined by inaccuracies or fraud. Commit to consistent habits and measure improvements over months rather than days.