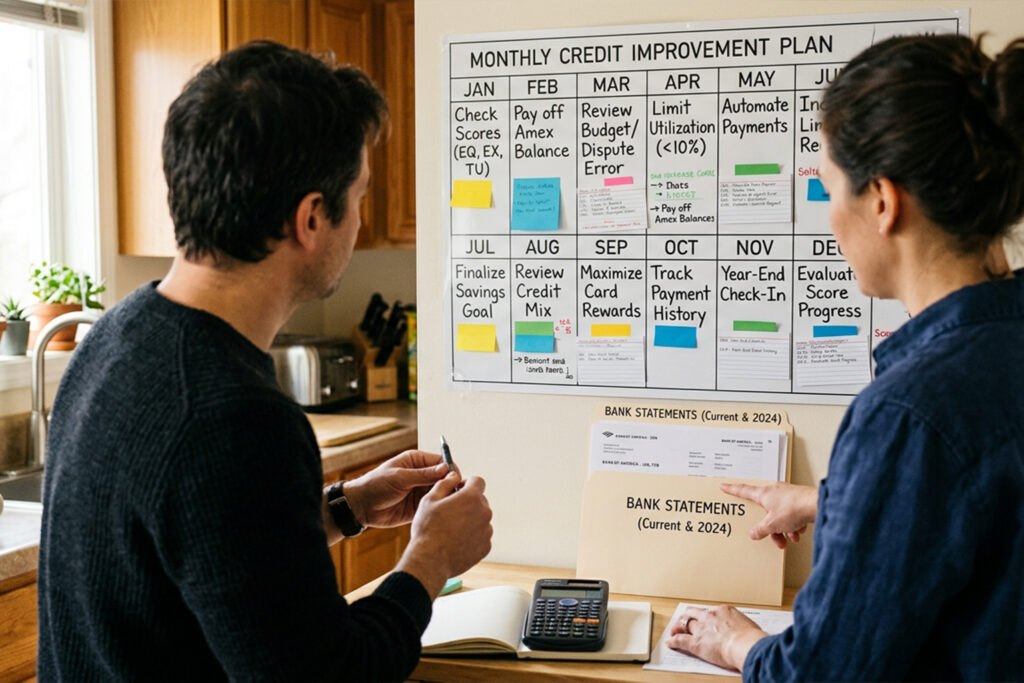
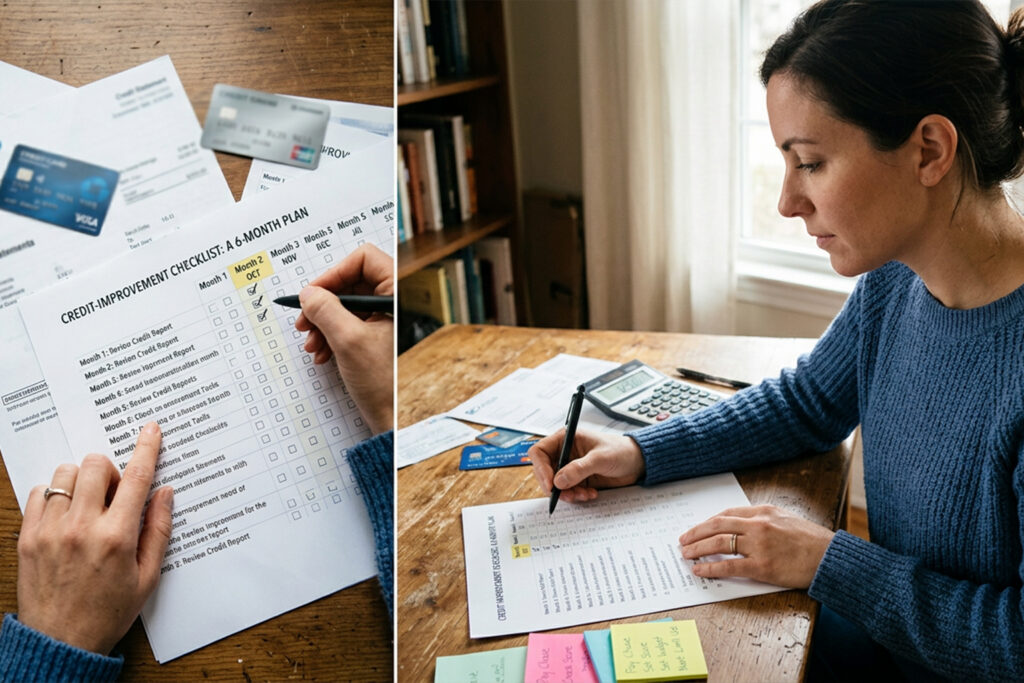
Five Focused Actions to Build a Healthier Credit Profile

Improving your credit score doesn’t require dramatic changes overnight.
Small, focused actions repeated consistently have outsized effects over time.
This article lays out five practical steps you can prioritize to strengthen your credit profile.
Use these steps to create a clear, manageable plan and monitor progress regularly.
These practices are suitable for a wide range of credit situations.

Assess Your Current Credit

Start by obtaining copies of your credit reports and current scores from reliable sources. Review accounts, balances, payment history, and any errors or unfamiliar items. Look for outdated negatives, duplicate entries, or incorrect personal data that could harm your score. Document any discrepancies and prepare to dispute inaccuracies with the reporting agency.

A clear snapshot helps you prioritize. Accurate records reduce surprises during improvement.

Prioritize High-Impact Actions

Address immediate, high-impact items first: past-due accounts, collections, and missed payments. Bringing accounts current and negotiating with lenders can stop ongoing score damage and may open doors for goodwill removals or payment plans. Lowering delinquencies often yields faster score improvements than opening new accounts. Focus on actions that correct active negatives before pursuing additional credit.

Targeted efforts create momentum. Small wins build credibility with future lenders.

Manage Credit Utilization and Payments

Credit utilization — the ratio of revolving balances to limits — is one of the strongest factors in many scoring models. Aim to keep utilization low both per account and overall; moving balances, paying down high-interest cards, or requesting modest credit limit increases can help. Automate on-time payments to prevent new late marks and consider multiple payments per month to lower reported balances. Regularly monitor statements to avoid surprises and maintain consistent habits.

Consistent payments show reliability over time. Reducing utilization often produces measurable score benefits. Small adjustments compound into real gains over time.

Build Positive Credit Events

Establishing a record of timely payments and a mix of account types strengthens your profile. If appropriate, add a small installment loan or a secured card and manage it responsibly to create additional positive history. Becoming an authorized user on a trusted account can help, but confirm the primary user maintains low utilization and on-time payments. Keep older accounts open to preserve length of history when they remain in good standing.

Positive events compound over months and years. Patience and consistency are essential. Celebrate milestones to stay motivated and maintain momentum.

Conclusion

Start with a clear assessment and tackle the highest-impact problems first.
Maintain low utilization and flawless payment timing while adding positive accounts cautiously.
Track progress and adjust your plan as your situation improves.

A Balanced Approach to Improving Your Credit Score

Improving a credit score is a gradual process that rewards consistent, informed choices.
This article outlines practical steps you can apply month by month to build healthier credit.
Small changes in payment timing, credit usage, and monitoring add up over time.
Use these methods to create a steady plan that fits your financial life.

Check and Understand Your Reports

Start by obtaining your credit reports and reviewing them carefully for errors and unfamiliar accounts. Dispute inaccuracies promptly and note any accounts that appear overdue or incorrectly reported. Understanding what contributes to your score—payment history, utilization, length of history, new accounts, and mix—lets you prioritize actions. Regular review also helps you spot potential identity theft early.

Keep a simple log of any disputes and follow up until resolved. This foundation reduces surprises and guides your next steps.

Prioritize Payments and Balances

On-time payments have the largest single impact on many scoring models; set up reminders or autopay to avoid missed due dates. If possible, pay balances in full each month to minimize interest and lower credit utilization. When paying minimums only, focus extra payments on high-interest or high-utilization accounts to improve your utilization ratio faster. Even small extra payments can reduce reported balances and support steady score gains.

Aim to keep utilization below 30%, and ideally much lower on individual cards. Consistent payment habits compound positively over time.

Use Credit Tools Strategically

Tools like secured cards, credit-builder loans, or authorized-user status can help establish or rebuild positive history when used responsibly. Avoid opening many new accounts at once, since hard inquiries and short average age of accounts can temporarily lower scores. Maintain older accounts open unless fees outweigh benefits, because length of history matters. Regularly checking a soft-score snapshot lets you track progress without harming your credit.

Combine these tools with disciplined payment behavior to see lasting improvement. Make incremental adjustments rather than radical moves.

Plan for Long-Term Credit Health

Create a long-term plan that aligns credit-building actions with broader financial goals such as saving and debt reduction. Maintain an emergency fund to avoid relying on credit for unexpected expenses, which can destabilize progress. Regularly review where you stand against your plan and adjust priorities when life events change income or expenses. Remember that steady, predictable improvements are more sustainable than aggressive short-term tactics that may carry risk.

Set measurable milestones, such as lowering utilization by a set percentage or achieving consecutive on-time payments. Celebrate progress and recalibrate when needed to keep momentum without taking unnecessary risk.

Conclusion

Improving credit is a marathon, not a sprint.
Prioritize accuracy, timely payments, and manageable balances.
With steady habits, your score will reflect your financial discipline.

Creating Credit Resilience Through Consistent Small Steps

Building reliable credit is less about sudden changes and more about steady daily and monthly actions that add up. Small adjustments to how you pay, use, and monitor credit can reduce volatility and improve long-term standing. This article outlines practical, low-friction steps designed to create credit resilience over time. Use these habits to create a stable foundation that responds well to life’s ups and downs.

These approaches prioritize consistency, clarity, and manageable effort. They work together to reduce risk and improve your profile in a gradual, sustainable way.

Start with consistent on-time payments

Payment history is one of the strongest signals in credit evaluations, so making payments on or before the due date prevents negative marks. Automating at least the minimum payment reduces human error and helps keep accounts current even during busy months. If full balances are not possible every cycle, aim to pay more than the minimum when you can to lower interest and principal. Consistency here builds trust with lenders and avoids the setbacks that come from late payments.

Consider using calendar reminders or automated transfers tied to paydays. These small process tweaks remove friction and make reliable payments habitual.

Keep utilization low and strategic

Credit utilization — the percentage of available revolving credit you are using — influences scoring and perceived risk. Aim to keep utilization under a conservative threshold each month, and if one card is high while others are low, redistribute spending or make early payments to lower that ratio. Lower utilization shows capacity to manage credit and reduces the likelihood of score dips from sudden balances. Regularly reviewing balances ahead of statement closing dates helps control reported utilization.

  • Make payments before statement dates to reduce reported balances.
  • Spread purchases across multiple accounts to avoid a single high-utilization account.
  • Request modest credit line increases judiciously when your history supports it.

These tactics are simple and often free, but they require deliberate timing and periodic review. Over months, they can materially affect the numeric score and lender perception.

Thoughtfully diversify and maintain account age

A mix of credit types and a longer average account age can demonstrate credit depth and stability. Opening new accounts introduces short-term volatility, so weigh the immediate benefits against potential impact on age and inquiries. Keep older accounts open when they do not carry high fees or risks; closing longstanding cards can shorten average age and reduce resilience. Choose new credit only when it serves a clear, necessary purpose.

Balanced and patient account management signals steady behavior to scoring models. Over time, responsible diversification can broaden options and strengthen your profile.

Monitor, correct errors, and adapt

Regular monitoring helps you spot reporting mistakes, identity issues, or sudden shifts that require action. Obtain periodic reports, check for inaccuracies, and dispute errors promptly to prevent long-term damage. Use alerts for large changes or new accounts and review key metrics monthly so you can adapt spending and payment plans when needed. Transparency gives you agency to respond before small problems become significant.

Set realistic review routines and treat them as part of your financial hygiene. Small, timely corrections preserve the momentum of other good habits.

Conclusion

Creating credit resilience is a process built from consistent, sensible choices that accumulate over time. Focus on punctual payments, controlled utilization, measured diversification, and regular monitoring. These practices form a durable framework that supports steady credit improvement and stability.

Practical Weekly Steps That Build Credit Momentum

Small, consistent actions each week can steadily improve your credit profile.
Focusing on monitoring, utilization, and timely payments creates measurable momentum.
This guide breaks weekly habits into manageable steps you can follow.
Adoptable routines help you track progress without overwhelming your finances.

Weekly Monitoring and Small Wins

Start each week by reviewing key elements of your credit report and score, paying special attention to recent inquiries and balances so you can spot anomalies quickly. Look for errors, unexpected accounts, or sudden changes and flag them for investigation, then set reminders to follow up on any disputes you open. Regular monitoring helps you detect identity issues early and prevents small problems from becoming major setbacks that are harder to resolve. Use free tools or credit monitoring alerts to maintain visibility without extra cost and consolidate findings in a simple weekly note to track trends.

These short checks take little time and deliver peace of mind, and they often reveal small opportunities for improvement. Make monitoring a nonnegotiable part of your weekly routine to keep momentum steady.

Manage Utilization and Payments

Aim to keep revolving credit utilization low by spreading balances across cards and making periodic payments mid-cycle, which can reduce the balance that is reported to lenders. Paying down high balances before the statement closing date reduces reported utilization and can impact your score faster than waiting to pay the full statement, so prioritize accounts with the highest utilization. Automate minimum payments to avoid late marks, then schedule additional payments when possible to chip away at principal and shorten the time you carry significant balances. This two-pronged approach balances timeliness with strategic reduction of reported balances and supports healthier credit behavior overall.

Small, strategic payments each week can lower utilization meaningfully and improve reported ratios. Consistency here compounds into stronger credit results over months, so treat these payments as part of your routine.

Strategic Account Management

Review which accounts contribute positively—older, well-managed accounts often help your credit age and mix, so recognize their value before making changes. Avoid closing long-standing cards unless fees outweigh benefits, and consider adjusting credit limits responsibly rather than canceling accounts to preserve available credit. If opening new credit, do so sparingly and with purpose, since inquiries can temporarily dip your score and new accounts change your mix; plan openings around specific needs. Periodically rebalance accounts to ensure you retain a healthy mix of installment and revolving credit while aligning actions with your broader goals.

Thoughtful account decisions keep your profile stable and predictable and reduce surprise impacts on your score. Use weekly check-ins to decide actions that align with your long-term goals and adapt as circumstances change.

Conclusion

Small weekly habits compound into measurable credit improvements.
Focus on monitoring, utilization, and account strategy.
Stay consistent and review progress monthly to stay on track.

Structured Steps to Lift Your Credit Score Gradually

Improving your credit score doesn’t require dramatic moves, but it does need a clear plan.
This article lays out a structured, month-by-month approach that focuses on high-impact habits.
You’ll learn how to prioritize actions, track progress, and reduce common mistakes that slow improvement.
The goal is steady gains you can sustain rather than risky shortcuts.
Small, consistent changes compound into meaningful score improvements over months.

Understand Your Credit Snapshot

Start by pulling your credit reports and score so you know exactly where you stand. Look closely for inaccuracies, outdated accounts, or unfamiliar inquiries that could be harming your score. Identify which accounts drive the most weight, typically payment history and utilization, and calculate realistic targets for each. Understanding the baseline helps you choose the most effective first steps. This analysis helps you avoid chasing low-impact fixes.

  • Check all three bureaus if possible.
  • Note balances, limits, and delinquent items.
  • Record your current score and set target milestones.

Make corrections through official dispute channels and document everything during the process. Accurate reports create a firm foundation for improvement.

Prioritize High-Impact Actions

Focus first on actions that move the needle fastest: bring past-due accounts current, and lower revolving balances to reduce utilization. Even modest reductions below 30% utilization can produce measurable change, and under 10% is ideal for stronger gains. Keep a plan for paying down balances that targets high-rate or high-utilization accounts first. Consider strategic credit limit increases or balance transfers only if they reduce utilization without adding risk. If debt is large, consider a formal repayment strategy to avoid cycling balances.

  • Pay more than the minimum where possible.
  • Set specific payoff targets each month.
  • Avoid opening new accounts solely to increase available credit.

These focused moves produce the quickest improvements while minimizing disruption to long-term history. Stay disciplined and reassess progress monthly.

Maintain Momentum with Habits

Sustain gains by building consistent habits that support score stability over time. Use automatic payments to avoid late payments, monitor accounts for unexpected changes, and keep new credit applications infrequent. Diversify credit types carefully, and respect the age of your accounts—older, well-managed accounts are valuable. Regularly revisit goals and adjust plans as your financial picture evolves. Also, keep emergency savings so you avoid unexpected credit reliance during shortfalls.

Good habits compound faster than quick fixes and reduce the risk of setbacks. Keep tracking and celebrate incremental wins to stay motivated.

Conclusion

Improving your credit score is a manageable, long-term project.
Steady, prioritized actions yield reliable results over time.
Start with one clear step this month and build from there.

Step-by-Step Guide to Sustainable Credit Improvement

Improving your credit score is a gradual process that rewards consistent habits and informed choices.
Start by understanding the components that influence your score so you can prioritize actions effectively.
Small, regular improvements often yield better long-term results than dramatic short-term fixes.
This guide outlines practical steps you can follow to strengthen credit health over time.

Understand Your Current Report

Begin with a careful review of your credit report to identify errors, outdated information, and accounts that affect your score most heavily. Check for incorrect balances, unfamiliar accounts, and reporting errors, and note any adverse entries such as late payments or collections. Knowing the specific items on your report helps you form a targeted plan rather than applying generic fixes. Accurate information is the foundation for any meaningful credit improvement effort.

Once you have a clear picture, prioritize items that have the largest negative impact. Disputing genuine errors with the reporting agency can remove damage quickly, while negotiating with creditors might resolve legitimate delinquencies. Keep records of all communication and confirmations during the dispute process. Regularly recheck your report after actions are taken to confirm updates.

Address High-Impact Issues

Focus on the factors that typically influence scores most: payment history, credit utilization, and the age and mix of accounts. Bringing past-due accounts current and establishing an on-time payment record will steadily restore trust in your credit profile. Lowering credit card balances to reduce utilization often produces noticeable score improvement in a short period. Avoid closing older accounts solely to reduce the number of accounts, as age and available credit can be beneficial.

When dealing with collections or charged-off accounts, consider seeking a pay-for-delete agreement or asking for a goodwill deletion after payment. Make sure any settlement is documented in writing before you pay. If debts are legitimate but burdensome, explore repayment plans or professional counseling to create a sustainable path forward. Responsible management of these issues prevents recurring damage.

Make Consistent Positive Moves

Consistency matters: on-time payments, modest credit use, and careful new-account activity build a stronger profile over months and years. Automate payments to prevent accidental late payments and set target utilization ratios to keep balances low relative to limits. Diversifying credit types responsibly can help, but only when you can manage additional obligations without stress. Patience and steady habits usually outperform quick fixes or risky credit maneuvers.

Track progress regularly and adjust the plan as your circumstances change. Celebrate milestones, like reducing utilization or adding several months of on-time payments, to stay motivated. Remember that rebuilding credit is measurable and achievable with clarity and persistence.

Conclusion

Consistent, informed actions produce reliable improvement in credit scores over time.
Focus on correcting errors, addressing high-impact problems, and sustaining good habits month to month.
With patience and a clear plan, your credit health can steadily strengthen and open new opportunities.

Everyday Financial Moves That Improve Your Credit Score

Improving your credit score is a gradual process shaped by daily financial choices. Small changes in how you handle payments, balances, and accounts can produce meaningful gains over time. Tracking progress helps keep momentum and prevents small issues from becoming major setbacks. This article lays out practical habits you can start using today to strengthen your credit profile.

Track Your Credit Regularly

Begin by reviewing your credit reports and scores periodically to identify errors, unexpected inquiries, or signs of identity issues. Regular checks make it easier to address inaccuracies and to understand how specific behaviors affect your score. Use reputable services or tools that provide consolidated views and alerts for material changes. Making monitoring a routine helps you react quickly and keep your profile healthy.

When you find discrepancies, follow up promptly with the relevant creditor or reporting agency. Early corrections protect your score and reduce the risk of long-term consequences.

Prioritize On-Time Payments

Payment history is a major factor in most scoring models, so focus on paying bills on schedule. Automate recurring payments where possible and use reminders for manually paid obligations to avoid accidental late payments. If a payment is missed, bring the account current and communicate with the creditor about options to resolve the issue. Establishing reliable payment habits builds a positive record over time.

Simple tools like calendar reminders or automatic transfers can substantially reduce missed due dates. Consistently on-time payments are one of the most reliable ways to improve your standing.

Manage Balances and Credit Utilization

Keep revolving balances low relative to available credit to maintain a healthy utilization ratio. Paying down high balances, making multiple payments in a billing cycle, and avoiding maxing out cards can lower reported utilization. Be cautious about closing older accounts, since length of credit and available limits influence calculations. Thoughtful balance management signals lower risk to lenders and tends to support score gains.

  • Aim to stay well below high utilization—under 30% is a common target.
  • Lower utilization, such as below 10%, can deliver even better results.

Monitor statements and adjust spending to prevent creeping balances. Incremental reductions in utilization often produce steady score improvements.

Build a Diverse, Responsible Credit Mix

A responsible mix of credit types—revolving and installment—can demonstrate your ability to manage different obligations. That doesn’t mean taking on unnecessary debt; instead, choose products that meet real needs and that you can reliably repay. Keeping long-standing accounts open while using new credit sparingly also helps. Focus on consistent, responsible management rather than variety for its own sake.

Apply for new credit only when there is a clear benefit, and avoid frequent hard inquiries. Over time, a stable, well-managed mix supports a stronger profile.

Use Tools and Professional Resources

Leverage budgeting apps, credit-tracking tools, and educational resources to stay organized and informed about your habits. Free reports, fraud alerts, and secured credit options can be practical steps for establishing or rebuilding history. If you face complex challenges, a non-profit credit counselor can provide tailored guidance. Verify any paid service before committing and prioritize reputable providers.

  • Free annual reports and alerts are good starting points.
  • Non-profit counseling can offer personalized strategies.

Combining self-monitoring tools with trusted advice amplifies your efforts. The right resources make steady improvement more achievable.

Conclusion

Improving your credit score comes down to consistent, responsible actions over time. Monitor reports, pay on time, manage utilization, and use tools that support your goals. Small daily habits compounded over months typically yield the most reliable gains.

A Practical Monthly Plan to Boost Your Credit

Improving your credit score doesn’t require dramatic changes overnight. Small, consistent monthly actions can add up to meaningful improvements. This plan lays out simple steps you can follow every month to strengthen credit habits. Follow it for several months and measure progress to stay motivated.

Set a Monthly Credit Checklist

Begin each month by reviewing key credit tasks and setting priorities. Check upcoming payment due dates, recent balances, and any notices from lenders. Allocate time to update a budget and set auto-pay where helpful. A short checklist prevents oversights that can lower a score. Also glance at your credit score trend to spot progress or declines early.

  • Confirm due dates and calendar reminders.
  • Set payment amounts and automation where sensible.
  • Review high balances and work to reduce utilization.
  • Note any new inquiries or recently opened accounts.

Keep the checklist visible and update it as circumstances change. A steady routine reduces missed payments and keeps utilization in view.

Keep Balances Low and Payments Timely

Payment history and credit utilization are two of the largest influences on most scoring models. Aim to pay at least the minimum on time, and ideally pay full balances when possible. Try to keep individual card utilization below 30% and aggregate utilization low. Making multiple small payments across the month can help lower reported balances. If possible, schedule payments a few days before due dates to avoid processing delays.

Consistent, on-time payments build a reliable history that lenders favor. Reducing utilization signals lower risk and often lifts scores.

Use Credit Mix and New Accounts Carefully

A diverse credit mix can help, but opening new accounts should be deliberate. New credit inquiries and short account age can temporarily lower scores. Consider whether a new card or installment loan addresses a specific need or improves terms. If opening accounts, space applications and maintain older accounts. Where appropriate, consider small credit-builder products to diversify the mix without risking large debt.

Responsible use of different account types can be beneficial over time. Avoid unnecessary applications that provide little long-term value.

Monitor Reports and Correct Errors

Regularly review your credit reports to catch inaccuracies, identity issues, or outdated information. Mistakes like wrong balances or unfamiliar accounts can drag scores down if uncorrected. Dispute verified errors promptly and document communications with bureaus or creditors. Monitoring tools and alerts can flag sudden changes to investigate quickly. If you suspect fraud, place alerts or freezes and follow up with creditors to limit damage.

Timely corrections protect your profile and restore accurate standing. Staying aware also deters fraud and unexpected score shifts.

Conclusion

Stick to these monthly habits and track your progress.
Small, sustained actions compound into noticeable score improvements.
Review and adjust the plan as your financial situation evolves.

A Practical Roadmap to Better Credit in a Year

Improving your credit score is a practical process that rewards consistent habits.
Small adjustments to payment timing, balances, and credit use compound over months.
This article lays out a realistic, month-by-month roadmap you can follow for a year.
Apply these steps steadily to build measurable improvement without drastic changes.

Assess Your Starting Point

Begin by reviewing your current credit reports and scores to identify priorities and errors. Look for missed payments, high balances, unusually high utilization, and unfamiliar accounts. Establish which items are hurting your score the most so you can address them first. A clear baseline helps you set realistic monthly targets and measure progress.

Record key metrics such as total available credit, current utilization rate, and any derogatory marks. Updating this snapshot every month will reveal which actions have the greatest impact. Small, consistent reductions in utilization and timely payments will become evident over a few reporting cycles.

Prioritize On-Time Payments

Payment history is a top factor in most scoring models, so focus on making every payment on time. Automate recurring bills where possible and set calendar reminders a few days before due dates to avoid accidental lapses. If you have past-due accounts, contact creditors to arrange payment plans or settlements that may limit further negative reporting. Rebuilding positive payment records is one of the fastest ways to improve your score over time.

  • Set up autopay for minimums, then add extra when feasible.
  • Use payment apps or calendar alerts as backup reminders.
  • Prioritize creditors that report to major bureaus.

Consistency matters more than perfection; avoid new missed payments and stay the course. Over months, on-time history will outweigh older negatives as long as you maintain good behavior.

Manage Balances and Utilization

High credit utilization can suppress scores even when payments are timely, so reduce revolving balances strategically. Aim to keep utilization below a conservative threshold and pay down the highest-interest or highest-balance accounts first. Consider making multiple payments each month to lower reported balances by statement dates. Small reductions in utilization often translate to noticeable score improvements.

  • Target accounts with utilization over 30% first.
  • Make payments before statement closing dates to record lower balances.

Balancing payment timing and reduction plans helps you free up available credit gradually. Over several months this approach can produce steady score gains.

Use Credit Mix and New Accounts Carefully

A diverse mix of credit types and a modest number of responsibly managed accounts can benefit your profile. Avoid opening multiple new accounts at once since inquiries and short account age can lower your score temporarily. When you need new credit, compare offers and choose products that support long-term goals, such as a low-interest card or a secure loan to build history. Think strategically about when and why to apply rather than reacting to every offer.

Maintain older, healthy accounts open to preserve account age and history. Thoughtful, infrequent new credit along with steady management will support gradual improvement.

Monitor and Dispute Errors

Regular monitoring helps you spot inaccuracies that could unfairly lower your score, such as duplicate accounts or incorrect late payments. If you find errors, file disputes with the reporting agencies and provide documentation promptly. Correcting mistakes can produce quick improvements when they are resolved. Use free monitoring tools or periodic manual checks to stay informed about changes to your reports.

Document all communications and follow up until disputes are closed. Accurate reporting paired with consistent financial habits leads to the most reliable long-term gains.

Conclusion

Steady habits produce steady score gains over time.
Track progress monthly and adjust tactics as needed.
Stay patient—consistent choices compound into stronger credit.

Actionable Credit Score Checklist for the Next Six Months

Improving your credit score can feel overwhelming without a clear, prioritized plan.
This checklist breaks down priorities into manageable monthly tasks and realistic checkpoints.
Use the sequence to reduce risk, address errors, and build a pattern of positive account activity.
Follow these steps consistently to see measurable improvement over six months and set new habits.

Assess Your Starting Point

Begin by collecting your credit reports and current score from available sources, then record key dates and balances. Review accounts for errors, outdated information, or unfamiliar inquiries that may need disputes and supporting documentation. Note accounts with high utilization and any late payments that require remediation or negotiating with creditors. Understanding the baseline helps you set realistic targets and prioritize actions that will have the most impact.

  • Check report for incorrect personal info.
  • Identify accounts over 30% utilization.
  • List any recent late payments and their dates.

After this inventory, set a clear numeric goal and timeline. A specific target makes it easier to measure progress and stay accountable.

Prioritize High-Impact Actions

Tackle items that influence score the most first: payment history, collections, and credit utilization. Bring any past-due accounts current and create a plan to avoid missed payments, including communication with creditors when necessary. Reduce balances on revolving accounts to lower utilization to below 30%, aiming for 10–20% if possible, and focus on the highest-rate or highest-balance cards first. If you have unused accounts, avoid closing them unless necessary to preserve average age and available credit, and consider asking for credit line increases on stable accounts.

  • Set automatic payments for minimums.
  • Make two payments per month to reduce reported balances.

These actions typically yield the quickest score gains. Consistency is essential for sustained improvement, so track outcomes and tweak tactics monthly.

Build Positive Activity and Monitor Progress

Add small, regular positive behaviors like on-time payments, small credit line usage to show activity, and responsible handling of any new credit. Consider a secured card or a credit-builder loan if you lack current accounts in good standing; these tools can establish positive payment history when used responsibly. Track your score monthly and adjust strategies based on changes, seasonal spending, or life events that might affect balances and payments. Continue to dispute inaccuracies promptly and document any communications for reference; clear records speed resolutions and support future disputes if needed.

Monitor trends rather than daily fluctuations to avoid overreacting. Celebrate milestones to keep momentum and reinforce the habits that led to each gain.

Conclusion

Create a six-month plan focused on high-impact fixes and steady habits.
Review and adjust monthly, keeping disputes and payments organized.
Small, consistent actions compound into noticeable credit improvement.