Digital Identity Insurance: Protecting Your Data Footprint, Biometrics & Online Behavior

As our lives move deeper into the digital world, everything from our habits to our fingerprints becomes part of our online identity. But with this convenience comes vulnerability. Digital Identity Insurance is emerging as a new form of protection designed to safeguard your data footprint, biometric markers, and online behavioral patterns. Instead of waiting for identity theft to happen, this insurance model works proactively to monitor risks and cover the financial and emotional damage of digital breaches.

In an era where cyberattacks are increasingly sophisticated, protecting digital identity has become just as essential as protecting your home or your car. Digital Identity Insurance offers peace of mind in a world where nearly every login, purchase, or online interaction leaves a trace.

Why Digital Identity Needs Stronger Protection

Identity theft no longer relies only on stolen passwords. Hackers now target biometric data like face scans, fingerprints, and voice patterns — identifiers that can’t be changed once compromised. Additionally, online behavior profiles created from browsing patterns and metadata allow attackers to impersonate individuals more convincingly. As these digital markers become more permanent, the consequences of theft become more severe. Insurance steps in to guard against these evolving risks.

What Digital Identity Insurance Covers

Modern policies protect more than just stolen credit card numbers. They monitor biometric records, alert users to unauthorized access attempts, cover costs associated with identity restoration, and provide support if personal data is sold or misused online. Some plans even include dark-web monitoring, behavioral analytics alerts, legal assistance, and compensation for fraudulent financial activity.

How This Coverage Works

Insurers use advanced threat-detection tools that scan for unusual login patterns, device anomalies, or changes in biometric usage. Policyholders receive instant notifications when suspicious activity occurs. If identity theft happens, the insurance covers recovery expenses like legal fees, account restoration, and lost wages. The goal is not just to fix the damage but to prevent it before it escalates.

Why This Matters in a Digital Economy

Every year, billions of data records are exposed to cyber breaches. As smart devices, online banking, digital passports, and biometric authentication become widespread, the stakes continue to rise. Digital Identity Insurance offers a safety net, ensuring individuals have support when their digital identity is compromised — and helping them navigate a complex, interconnected world with confidence.

Conclusion

Digital Identity Insurance represents the next evolution in personal protection. By safeguarding your data footprint, biometrics, and online behavior, it provides security in a landscape where digital risks are constantly expanding. Investing in this coverage is not just about preventing loss — it’s about protecting the modern version of who you are.
How AI Is Helping Insurers Create Sustainable Insurance Models

As the insurance industry faces increasing pressure to adapt to changing consumer needs, environmental challenges, and economic uncertainties, AI (artificial intelligence) is playing a pivotal role in shaping more sustainable and resilient insurance models. By harnessing the power of big data, predictive analytics, and machine learning, insurers are enhancing risk assessment, reducing costs, and improving customer experiences. AI is driving efficiencies that not only boost profitability but also contribute to more sustainable and socially responsible business practices.

Optimizing Risk Assessment for Sustainability

AI enables insurers to make more accurate and detailed risk assessments by analyzing vast amounts of data. Through machine learning algorithms, AI systems can identify patterns, predict potential losses, and assess risks with higher precision than traditional models. This allows insurers to better allocate resources, set more accurate premiums, and reduce waste. More accurate risk assessments also help insurers offer policies that are more aligned with the actual risks faced by individuals, businesses, and even environmental factors, supporting a more sustainable approach to underwriting.

Encouraging Green Insurance Products

The growing demand for sustainability in the insurance industry has led to the development of green insurance products. AI plays a critical role in creating policies that support renewable energy, electric vehicles, and eco-friendly buildings. By analyzing data related to carbon footprints, energy consumption, and environmental risks, AI helps insurers tailor policies that reward customers for environmentally friendly behaviors. For example, drivers with electric vehicles or homeowners who install solar panels may receive discounts on premiums, encouraging a broader shift toward sustainability in the marketplace.

Enhancing Fraud Detection and Prevention

Fraudulent claims not only result in financial losses for insurers but also contribute to higher premiums for all policyholders. AI-driven fraud detection systems use machine learning algorithms to analyze large datasets for signs of suspicious activity, enabling insurers to identify fraudulent claims more quickly and accurately. By reducing fraud, insurers can maintain more affordable premiums and create more efficient, sustainable business models that focus on real risk rather than inflated costs due to fraud.

Improving Operational Efficiency and Reducing Waste

AI helps insurers streamline their operations and reduce unnecessary overhead costs. By automating routine tasks such as claims processing, customer service inquiries, and administrative duties, insurers can operate more efficiently, freeing up resources for higher-value activities. This efficiency not only reduces operational costs but also contributes to sustainability by reducing the carbon footprint of paper-based processes and manual workflows. Additionally, AI can optimize resource allocation, ensuring that insurers are investing in the right areas of their business.

Data-Driven Sustainability Decisions

The availability of vast amounts of data enables AI systems to make smarter decisions that contribute to long-term sustainability. For instance, AI can predict environmental risks such as natural disasters, helping insurers adjust their policies accordingly and better prepare for future events. AI also supports the use of “smart” insurance policies that adapt in real time to changing conditions, such as adjusting premiums based on a customer’s energy usage or carbon emissions. These data-driven decisions not only enhance profitability but also help insurers align with global sustainability goals.

Conclusion

AI is transforming the insurance industry by creating more sustainable, efficient, and customer-focused business models. From optimizing risk assessments and preventing fraud to offering green insurance products and enhancing operational efficiency, AI is helping insurers build resilient frameworks that benefit both the environment and their bottom line. As the industry continues to evolve, AI will remain a key enabler of sustainable growth, providing innovative solutions to the challenges of tomorrow.

Eco-Adjusted Life Insurance: How Your Sustainability Lifestyle Can Increase Your Policy Value

As sustainability becomes a core part of modern living, life insurance companies are beginning to reward individuals who make eco-conscious choices. Eco-adjusted life insurance is a growing trend that aligns environmental responsibility with financial benefits. Instead of simply assessing age and health, insurers now consider lifestyle habits such as reduced carbon footprints, low environmental impact, and long-term wellness practices. For policyholders, this means living sustainably can translate into real, measurable value.

Why Sustainability Matters to Insurers

Healthy habits often overlap with eco-friendly behaviors. People who bike to work, reduce emissions, choose plant-forward diets, or live in energy-efficient homes typically experience better long-term health outcomes. Insurers recognize this connection: environmentally conscious lifestyles can lead to fewer medical issues and lower risk factors over time. By rewarding these habits, companies encourage policyholders to stay committed to choices that benefit both their health and the planet.

What Eco-Adjusted Policies Work

Eco-adjusted life insurance evaluates sustainability metrics alongside traditional underwriting factors. These metrics may include energy usage, waste reduction, transportation methods, and even participation in green community programs. Policyholders demonstrating consistent eco-friendly habits may receive lower premiums, bonus credits, or enhanced policy value. Some insurers integrate data from smart home devices, fitness apps, and carbon-tracking tools to provide personalized incentives that reflect real behavior.

Benefits for Environmentally Conscious Households

Households practicing sustainability can unlock meaningful rewards through eco-adjusted policies. Families using solar power, energy-efficient appliances, or low-emission vehicles may qualify for added discounts. Additionally, individuals who engage in outdoor activities, reduce processed food consumption, and maintain low-impact lifestyles tend to experience improved physical and mental wellness. These benefits strengthen the link between environmental stewardship and long-term financial security.

Encouraging a Greener Future

Eco-adjusted life insurance creates a powerful cycle of positive change. When consumers adopt sustainable practices, insurers reward them. This financial encouragement motivates even more people to embrace eco-friendly habits, promoting a healthier society and a cleaner environment. As awareness grows, the insurance industry is expected to expand these offerings, making sustainable living both meaningful and financially advantageous.

Conclusion

Eco-adjusted life insurance reflects a growing trend where sustainability and financial well-being intersect. By rewarding environmentally conscious habits, insurers help policyholders increase their policy value while promoting a greener lifestyle. As more people adopt sustainable practices, this innovative approach will continue to shape the future of life insurance.

New Frontiers: Space, Drone, and Climate Risk Insurance

As technology advances and global risks evolve, the insurance industry is entering a new era of innovation. Space exploration, commercial drone operations, and climate-related disasters are expanding faster than traditional insurance models can keep up. In response, insurers are developing specialized coverage solutions designed to protect emerging industries and help organizations manage unprecedented levels of uncertainty.

Space Insurance for a Rapidly Growing Industry

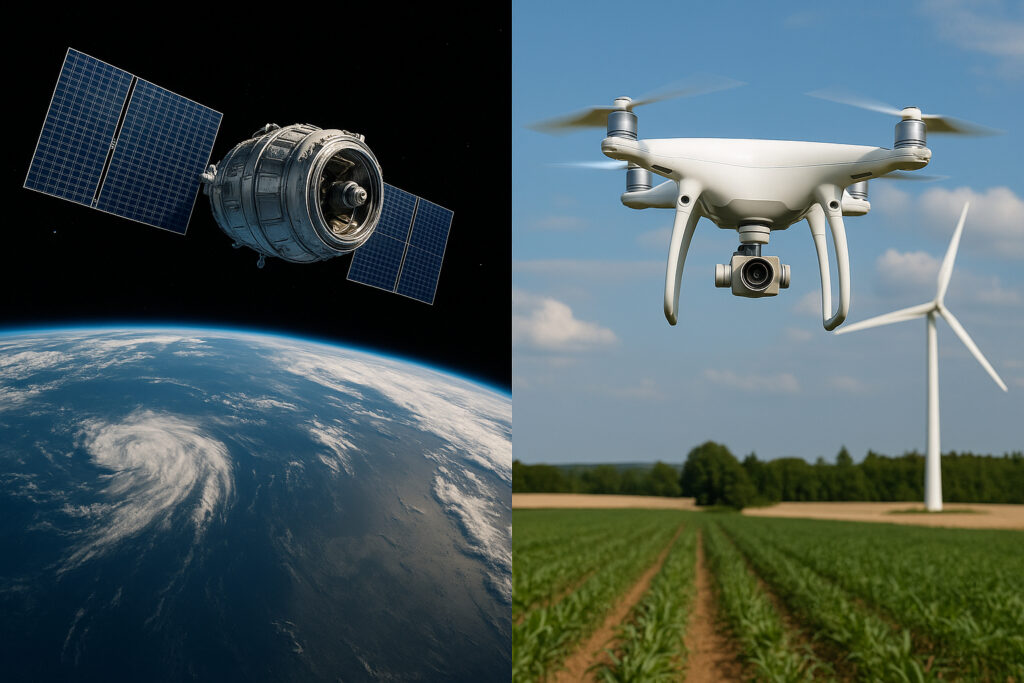
The space sector is no longer limited to government agencies—private companies now launch satellites, explore deep space, and invest in off-world infrastructure. With these advancements comes the need for highly specialized insurance. Space insurance covers launch failures, satellite malfunctions, orbital collisions, and mission interruptions. As space becomes more commercialized, insurers are using advanced risk modeling to support safer missions and more predictable outcomes.

Drone Insurance for Expanding Commercial Use

Drones are transforming industries such as logistics, agriculture, real estate, and emergency services. However, increased drone activity brings new risks, including property damage, privacy concerns, and airspace conflicts. Drone insurance provides protection for operators by covering liability, equipment damage, data loss, and operational errors. With stricter regulations and expanding commercial use, this type of insurance is quickly becoming essential for businesses that rely on drone technology.

Climate Risk Insurance for a Changing Planet

Climate change has led to more frequent and severe events—wildfires, floods, hurricanes, and heatwaves. Traditional insurance models struggle to account for these unpredictable patterns. Modern climate risk insurance blends historical data with real-time environmental monitoring and AI predictions to assess risk more accurately. These policies help businesses protect assets, respond quickly to disasters, and invest in resilient infrastructure.

Technology Driving New Insurance Solutions

The rise of digital sensors, satellite imagery, and predictive analytics is enabling insurers to evaluate risks with greater precision. For drones, sensors monitor flight paths and environmental conditions. For space missions, data from astronomic monitoring tools helps assess collision risks. For climate-related events, AI models analyze weather patterns to forecast potential losses. These technologies allow insurers to price policies more fairly and respond more proactively to emerging threats.

Conclusion

Space, drone, and climate risk insurance represent the next frontier in protecting people, businesses, and infrastructure in a rapidly evolving world. As technology continues to advance, insurers are adapting by offering specialized solutions that address complex and emerging challenges. These innovations ensure that organizations can pursue bold new opportunities while staying prepared for the risks of tomorrow.

Daily Risk Dashboards: Real-Time Updates on How Your Choices Affect Insurance Cost

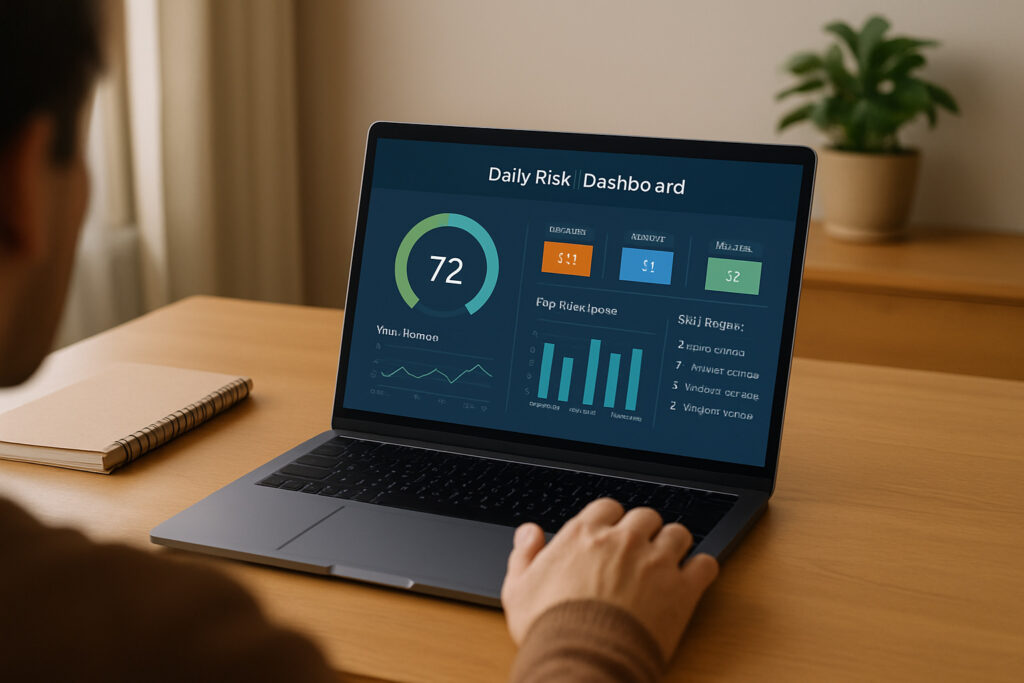
Insurance pricing is shifting toward a more transparent and personalized model—and daily risk dashboards are at the center of this evolution. Instead of waiting months to see how habits influence premiums, these dashboards give policyholders real-time insights into the choices that shape their insurance cost. By blending telematics, behavioral analytics, and AI-driven scoring, insurers offer users a clearer understanding of their risk patterns and practical ways to improve them. This innovation is turning insurance from a reactive system into a proactive partnership.

Real-Time Visibility into Your Daily Risk

Daily risk dashboards gather data from connected devices, telematics apps, and wearables to provide continuous updates on your insurance-related behaviors. Whether it’s driving speed, home security usage, health routines, or digital interactions, the dashboard breaks down how each action influences your overall risk score. Instead of hidden formulas, users see clear explanations that help them stay informed and make better decisions.

Encouraging Safer, More Mindful Behavior

One of the biggest advantages of daily dashboards is the way they reinforce positive habits. Drivers can see how hard braking affects their auto insurance score, homeowners can track safety compliance, and health policyholders can monitor activity patterns. These insights motivate people to adopt safer behaviors, which in turn may reduce claims and lead to long-term savings. It’s an empowering shift that puts users in control of their insurance future.

Personalized Tips Backed by Data

Daily dashboards don’t just report risks—they offer personalized recommendations. Users might receive tips to avoid high-risk driving times, improve home safety settings, or adjust routines that influence their health metrics. These suggestions are based on real data patterns, not general advice. Over time, policyholders become more aware of how small changes contribute to better protection and lower costs.

Better Communication Between Insurers and Policyholders

Instead of waiting for annual renewals or scattered notifications, daily dashboards maintain a constant line of communication. Users understand premium adjustments, risk warnings, and performance summaries without confusion. This level of transparency builds trust, reduces disputes, and helps customers feel more engaged with their insurance policies.

The Future of Personalized Insurance

As AI models and connected devices become more advanced, daily risk dashboards will continue shaping the future of insurance. Policies will adjust dynamically, rewarding users for consistent, low-risk behavior. This evolution benefits both insurers and policyholders—lower risk for companies, and fairer pricing for customers.

Conclusion

Daily risk dashboards transform insurance from a static product into a dynamic, data-driven experience. By offering real-time insights, personalized tips, and transparent scoring, these dashboards help users understand how their everyday choices impact insurance costs. As this technology becomes mainstream, policyholders will enjoy greater control, smarter pricing, and a more proactive path to risk management.

Health Behavior Credits: Earn Lower Premiums Through Daily Wellness Scores

Health insurance is undergoing a major shift toward personalization, and one of the most exciting developments is the rise of Health Behavior Credits—a system where daily wellness actions can directly reduce monthly premiums. Instead of treating everyone the same, insurers now reward individuals who consistently make healthier choices, creating a win-win model that improves well-being while lowering financial costs.

Daily Habits Turn into Real Savings

Wellness credits are based on measurable, everyday behaviors taken, hours slept, activity consistency, balanced routines, or even stress-reduction practices. Small habits such as taking regular walks, choosing healthier meals, or maintaining steady sleep patterns accumulate into a daily wellness score. Over time, these scores can translate into noticeable premium discounts.

Smart Devices Make Tracking Automatic

Wearables, fitness apps, smart scales, and activity trackers make this system effortless. Instead of filling out forms or self-reporting habits, data is collected automatically through devices people already use. This helps create accurate wellness profiles and eliminates guesswork or bias. The healthier someone’s patterns, the more they benefit.

Motivation Built into the Insurance Experience

Health Behavior Credits turn wellness into a rewarding routine. By showing people how their actions influence costs, insurers create motivation loops that encourage healthier choices. Customers begin to view insurance not just as protection, but as a supportive partner in their daily health goals.

Fairer Pricing for Individuals

Traditional insurance often groups people by broad demographics. Wellness-based pricing shifts the focus to what you do, not who you are. This makes premiums more personalized and fairer. Two people of the same age can now pay very different rates based on their actual health habits, not assumptions.

Conclusion

Health Behavior Credits are redefining insurance by making wellness measurable, meaningful, and financially rewarding. By turning everyday actions into discounts, insurers support healthier lives while giving customers direct control over their premiums. As this model expands, it promises a future where personal health habits drive both well-being and financial benefits.

Atmospheric Health Coverage: Insurance That Activates Based on Air-Quality Sensors

As air pollution becomes a growing concern in modern cities, a new form of protection is emerging atmospheric health coverage. Unlike traditional insurance, which responds only after a health issue occurs, this coverage activates instantly when air-quality sensors detect unsafe environmental conditions. By combining environmental technology with preventative health care, it creates a safety net designed for a world where poor air quality increasingly affects daily life.

Real-Time Protection Powered by Air-Quality Sensors

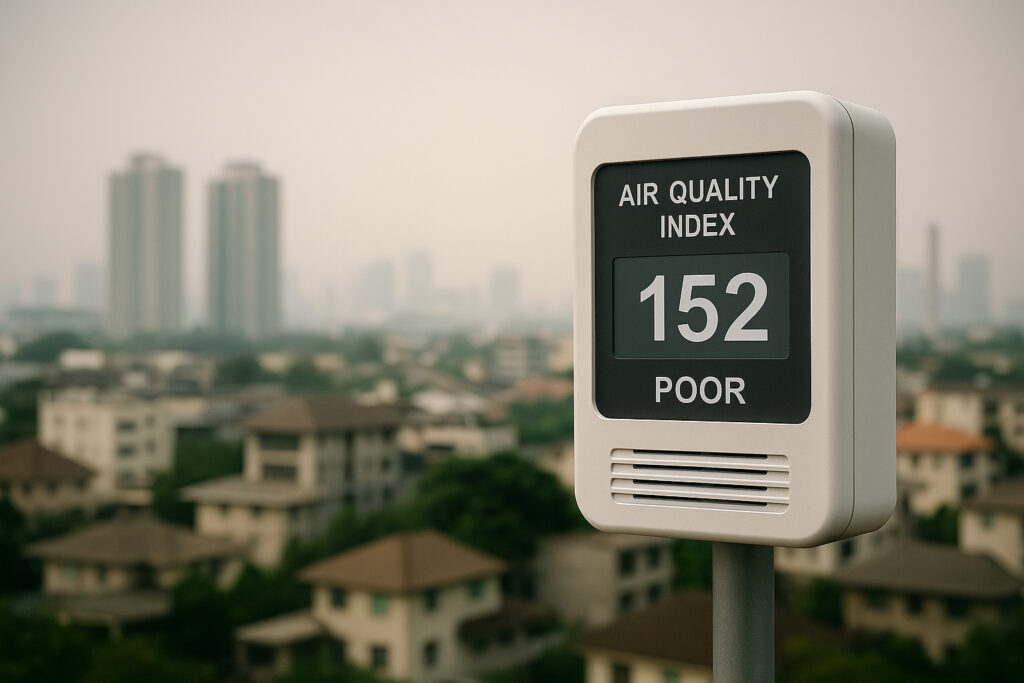
Atmospheric health coverage relies on networks of air-quality sensors—both public and personal—to track pollutants like PM2.5, ozone, and toxic chemicals. When readings cross a harmful threshold, insurance automatically triggers benefits. This may include coverage for medical consultations, medication, respiratory equipment, or even temporary relocation during high-risk periods. The result is a proactive system instead of a reactive one.

Reducing Health Risks Before They Become Emergencies

Poor air quality can exacerbate asthma, allergies, and cardiovascular conditions. Instead of waiting for symptoms to escalate, atmospheric insurance focuses on early support. Policyholders receive alerts and preventive care options as soon as local reading worsens. This approach reduces hospital visits, lowers long-term costs, and helps people with sensitive health conditions manage risks more effectively.

Built for Smart Homes and Connected Devices

Smart homes equipped with indoor air sensors, purifiers, and environmental smart monitors integrate seamlessly with this coverage. If indoor air quality drops due to smoke, mold, or chemical leaks, the system notifies the insurer automatically. This can prompt immediate assistance—such as scheduling home inspections, funding filtration upgrades, or covering related medical needs.

Encouraging Healthier, More Informed Living

Atmospheric health coverage helps people build better habits through real-time data. Policyholders become more aware of environmental triggers and can make informed choices about outdoor activity, travel, or home air management. Over time, this awareness leads to healthier behavior and reduced long-term health risks associated with pollution.

Conclusion

Atmospheric health coverage represents a major shift in how insurance supports well-being. By using real-time sensor data to activate protection, it moves beyond crisis response and into prevention. As environmental challenges continue to rise, this proactive model offers a smarter, safer way to live—empowering people to stay healthy even when the air around them isn’t.

Micro-Medical Riders: Coverage for Single Conditions Like Migraines or Allergies

Health insurance has traditionally focused on broad medical coverage, but many people struggle with specific recurring conditions that aren’t fully addressed by standard plans. Micro-medical riders are changing that. These add-on insurance options provide targeted coverage for single health issues such as migraines, allergies, sinusitis, or chronic skin conditions. By focusing on one condition at a time, they deliver affordable, efficient protection without requiring a full overhaul of an insurance plan.

Focused Protection for Recurring Conditions

Many individuals deal with a single recurring health problem that demands regular treatment. For conditions like migraines or seasonal allergies, the cost of routine care—doctor visits, tests, or medications—can add up quickly. Micro-medical riders step in by offering dedicated coverage for that one condition, reducing out-of-pocket expenses and creating a predictable and manageable approach to care.

Lower Costs Without Full Policy Upgrades

Instead of buying a more expensive comprehensive insurance plan, micro-medical riders allow people to enhance their existing coverage with focused benefits. This makes them ideal for families or individuals who have stable overall health but need help managing one persistent issue. It’s a cost-effective strategy for getting meaningful coverage without paying for services they don’t need.

Encouraging Early Treatment and Consistency

When people know their condition is covered affordably, they are more likely to seek early care rather than wait for symptoms to worsen. This proactive approach helps prevent escalated costs and complications. Whether it’s regular medication for allergies or periodic assessments for migraines, micro-medical riders support consistent treatment, which improves long-term health outcomes.

Designed for Today’s Personalized Healthcare

Micro-medical riders reflect a shift toward more personalized insurance solutions. People want coverage that aligns with their actual needs, not generic plans built for everyone. By allowing policyholders to choose riders for the conditions most relevant to them, insurers create flexible and responsive options that blend convenience with affordability.

Conclusion

Micro-medical riders offer a smart, targeted way to manage recurring health concerns without overspending on broad coverage. By focusing on single conditions—like migraines or allergies—these add-ons help individuals stay healthy, reduce unpredictable costs, and personalize their insurance experience. As healthcare becomes more individualized, micro-medical riders are emerging as an essential tool for efficient and practical protection.

Why Usage-Based Policies Are the Future of Auto Insurance

Auto insurance is undergoing a major shift, and usage-based policies are quickly becoming the future of the industry. Instead of relying on broad assumptions about drivers, vehicles, or demographics, insurers now use real driving data to personalize pricing. This modern approach rewards safer habits, gives drivers more control over their premiums, and builds a smarter, more transparent insurance experience. With technology playing a central role in mobility, usage-based coverage is transforming how people think about car insurance.

Paying Based on How You Drive

Traditional auto insurance calculates rates using factors like age, location, and historical claims. Usage-based insurance (UBI) changes the game by evaluating how a person actually drives. Small telematics devices or smartphone apps track behaviors such as speed, braking, cornering, and mileage. Safer driving leads to better pricing, making the system fairer and more personalized. Drivers who commute less or practice cautious habits benefit the most from these flexible models.

Saving Costs for Low-Mileage Drivers

Many drivers no longer travel long distances every day. Hybrid work schedules, remote jobs, and lifestyle changes have reduced annual mileage for millions of people. Usage-based policies are ideal for these situations because they adjust premiums based on actual travel. People who drive less pay less, making coverage more affordable for students, retirees, remote workers, and occasional drivers.

Increasing Transparency Through Real Data

Usage-based insurance brings greater transparency to the pricing process. Instead of wondering why premiums increased, drivers receive clear feedback based on their driving habits. Some apps even offer real-time scorecards, tips, and route insights to help drivers improve their behavior. This level of visibility builds trust and helps users feel more in control of their insurance experience.

Encouraging Safer Roads

Because UBI programs reward responsible driving, they create a natural motivation for drivers to adopt safer habits. Reduced speeding, smoother braking, and consistent focus behind the wheel can lower accident risks. As more people shift to usage-based policies, improved driving behaviors can lead to safer roads overall—benefiting both drivers and communities.

Supporting the Future of Mobility

As vehicles become more connected, the demand for smarter, data-driven insurance grows. Usage-based models align perfectly with electric vehicles, car-sharing platforms, and autonomous features. They provide insurers with deeper insights and help drivers stay informed in a rapidly evolving mobility ecosystem. This adaptability is one of the key reasons why UBI is becoming central to the insurance industry’s future.

Conclusion

Usage-based auto insurance offers fairness, flexibility, and transparency that traditional models can’t match. By rewarding safer habits, reducing costs for low-mileage drivers, and using real data to guide pricing, these policies represent the next generation of auto coverage. As technology advances, usage-based insurance will continue to reshape how drivers protect themselves on the road.

Cyber-Home Coverage: Protecting Smart Homes from Digital Attacks

Smart homes bring incredible convenience—voice-controlled lights, connected appliances, automated security systems, and intelligent climate control. But as homes become smarter, they also become more vulnerable to cyber threats. Cyber-home coverage is emerging as a modern layer of home insurance designed to protect homeowners from digital intrusions, data theft, and smart-device hijacking. This type of protection recognizes that today’s risks extend far beyond physical property.

Why Smart Homes Need Cyber Protection

Every connected device—from doorbell cameras to thermostats—creates a potential entry point for cyber attackers. Hackers can exploit weak passwords, outdated software, or unencrypted networks to access personal information or take control of home systems. Cyber-home coverage helps homeowners respond to these digital threats by offering financial protection, expert support, and preventative guidance.

What Cyber-Home Coverage Typically Includes

Cyber-home insurance often covers a wide range of digital risks. This can include protection against smart-device hacking, identity theft, ransomware attacks, and unauthorized access to home Wi-Fi networks. Some policies provide professional recovery assistance, helping restore compromised devices or secure breached accounts. This ensures homeowners are supported not just financially, but also with technical expertise during stressful incidents.

Strengthening Digital Defenses at Home

Insurance alone isn’t enough—smart homes require active prevention. Cyber-home coverage often pairs with security recommendations, including strong passwords, multi-factor authentication, updated software, and secure routers. These simple steps strengthen a home’s digital perimeter and minimize the chance of an attack. With so many devices constantly exchanging data, layered protection becomes essential.

Peace of Mind in a Connected World

As smart-home adoption grows, digital risks become a natural part of modern living. Cyber-home coverage provides reassurance that homeowners aren’t facing these threats alone. Whether recovering from a hacked camera, securing personal data, or restoring a compromised smart appliance, having coverage turns a complex digital emergency into a manageable situation.

Conclusion

Cyber-home coverage is an important evolution in home protection. As smart devices become central to daily life, insurance models must adapt to defend against digital attacks. By combining preventative measures with dedicated cyber support, homeowners can enjoy the benefits of a connected home with greater confidence and security.