Improving a credit score doesn’t require dramatic moves overnight.
Small, well-timed adjustments each quarter can add sustained improvements.
This approach focuses on measurable tasks and routine reviews.
The result is gradual but reliable progress toward stronger credit.
Assess Your Starting Point
Begin by pulling your credit reports and reviewing key metrics such as balances, recent inquiries, and open account ages. Look for anomalies, missed payments, or accounts you no longer use that may be dragging your profile down. Understanding where your score currently stands helps you prioritize actions that will have the biggest impact. Aim to document three to five areas to address over the next quarter.
- Track current utilization per card and overall.
- Note any late payments or collections.
- Record account ages and recent openings.
Having a clear snapshot makes quarterly planning practical and focused. Use this as your baseline for measuring progress at the end of the period.
Set Quarterly Targets and Routines
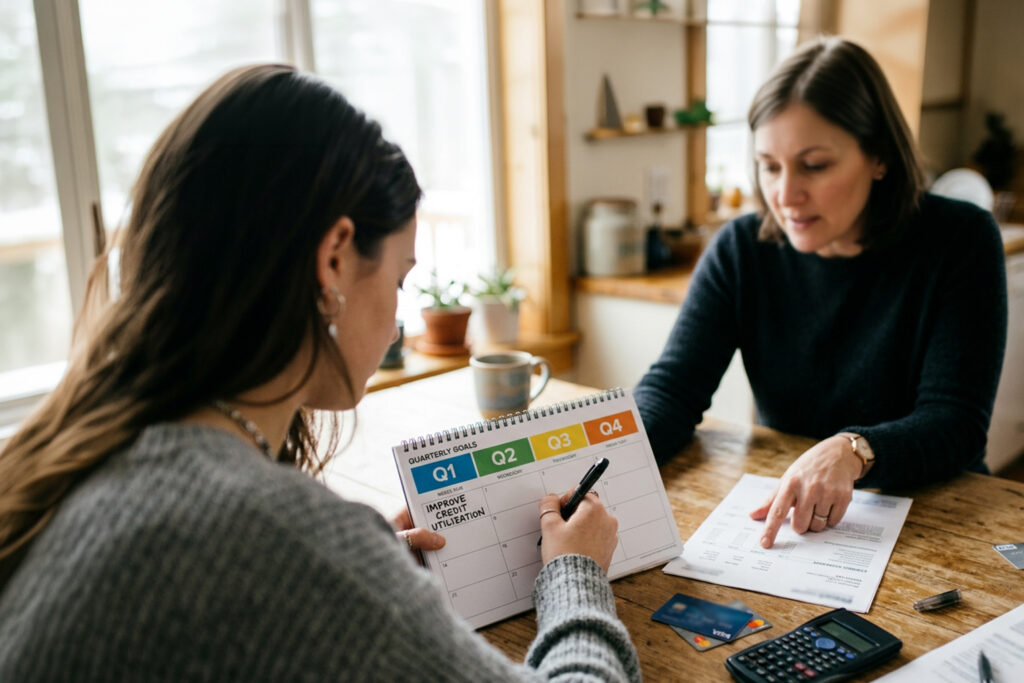
Create specific, achievable targets for a 90-day window instead of vague resolutions. Examples include reducing overall utilization by a set percentage, disputing errors, or bringing a delinquent account current. Schedule recurring reminders to check balances and due dates so small habits become consistent. Regular, modest wins compound and protect your score against setbacks.
- Target a utilization drop of 5–10% per quarter.
- Plan one dispute or verification task each month.
These routines help maintain momentum without overwhelming your schedule. Quarterly reviews let you adjust targets based on real results.
Reduce Balances and Optimize Utilization
Lowering credit utilization is one of the most effective short-term levers to improve scores. Focus payments on higher-rate or high-balance cards first while preserving on-time payments across all accounts. Consider small balance transfers only when fees and terms clearly support savings over time. Avoid opening new accounts solely to increase available credit without a repayment plan.
- Prioritize payments to reduce the highest utilization lines.
- Keep at least a couple of accounts with low balances to show responsible use.
Consistency matters: make steady payments each billing cycle and avoid maxing out cards. Over several quarters, utilization improvements can produce measurable score gains.
Monitor Reports and Manage Errors
Set a habit of reviewing one report per month so you cover all bureaus each quarter. Dispute inaccuracies promptly and follow up until they are resolved to prevent lingering negative effects. Also monitor for unauthorized activity and freeze or lock accounts when appropriate. Regular monitoring reduces surprises and supports sustained improvement.
Document each dispute and the outcomes to build a clear history. This record helps if issues reappear or require further escalation.
Conclusion
Quarterly planning turns abstract goals into manageable actions.
Small, consistent improvements compound into meaningful score changes over time.
Stay disciplined, track progress, and adjust targets each quarter.