Picking a credit card can feel like wading through fine print and glossy offers. You don’t need every perk on the market, but you do want a card that fits how you actually spend. This short guide lays out straightforward steps to make the choice predictable, not stressful. Read on to match fees, rewards, and features to your routine without getting lost in jargon.
Match the Card to Your Habits
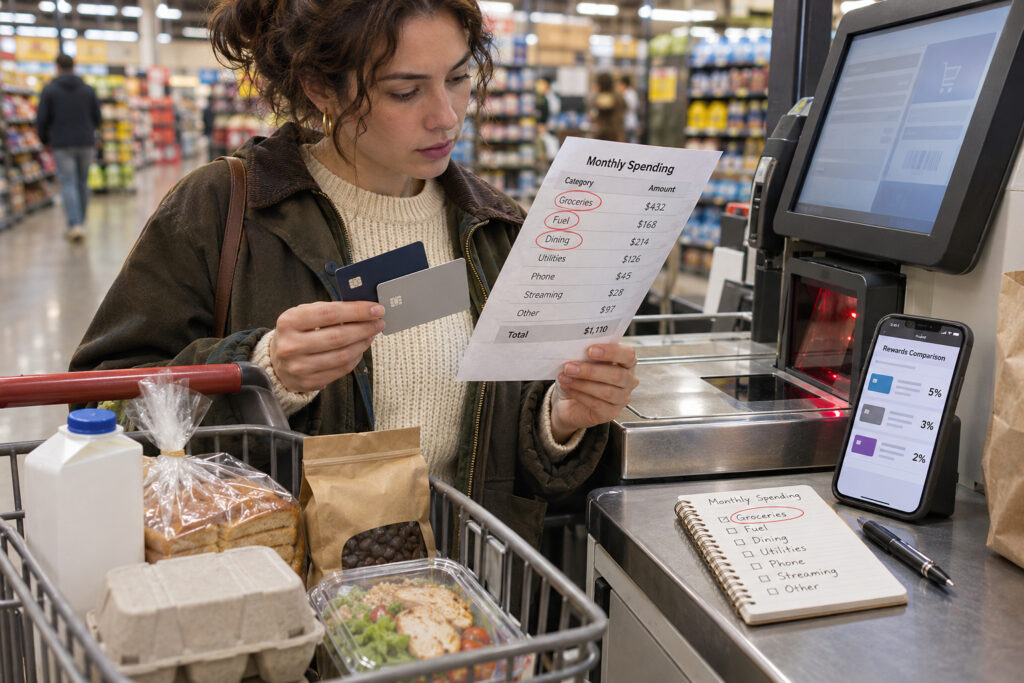
Start by tracking where you spend most: groceries, rides, fuel, dining, or travel. If a large share of your monthly bills goes to a few categories, a card that rewards those purchases will return more value than a general cash-back rate. Consider how often you travel or pay foreign transactions; cards that sound ideal for occasional trips can be costly if you rarely leave home. Also check whether you usually carry a balance, because interest charges can erase any reward gains.
Once you map spending, shortlist two or three cards and compare their benefits against your top categories. Look past the headline reward rate and imagine a typical month to see real value.
Understand Fees and Rewards
Rewards matter, but fees and redemption rules determine whether those points are worth collecting. Annual fees may be justified by benefits you will actually use, like travel credits or purchase protections, while foreign transaction fees and late payment penalties are common pitfalls that cut into returns. Redemption floors, minimums, and blackout dates can make points harder to use than advertised, so read the program rules before committing. Also note that higher reward rates sometimes apply only to rotating categories or require activation each quarter.
- Annual fee: weigh cost versus expected benefits.
- APR and late fees: affect value if you carry a balance.
- Redemption limits: points may have minimum thresholds or restrictions.
Factor all of these into a simple year-long calculation: expected rewards minus fees and realistic redemption value. That gives a clearer picture than an appealing headline rate.
How to Compare Offers
When comparing cards, create a spreadsheet or simple note listing rewards by category, fees, welcome offers, and protections such as extended warranty or purchase insurance. Treat sign-up bonuses as one-time gains—helpful but not a substitute for solid ongoing value—and check if the bonus conditions match your usual behavior. Pay attention to how rewards are earned and redeemed: a transferable points program can offer flexibility, while fixed cash-back is simpler to use. Finally, read the fine print on introductory APRs and balance transfer terms if those features matter to you.
Choose a primary card you will use every day and a secondary card for niche perks if needed. Reassess annually; your spending and priorities change, and the best card for you can change too.
Conclusion
Choosing the right card starts with honest tracking and a short list of must-have features. Think long term about fees and realistic reward value rather than chasing shiny offers. A clear head and a routine-centered comparison usually arrive at the smartest choice.