As health needs, routines, and finances shift in retirement, supplemental insurance that once fit your life can drift out of step. Small changes — a new medication, a recent hospital stay, or a tighter monthly budget — often reveal unexpected gaps or unnecessary costs. Rather than react under pressure, a brief, regular review makes it easier to spot mismatches and act deliberately. This piece explains common triggers for a review, the first things to compare, and practical steps to adjust coverage without confusion.
Periodic checks don’t mean constant upheaval; they mean smarter choices. A short checklist and a set schedule make updates manageable and less stressful.
When to Revisit Your Plan
Not every change requires an immediate switch, but several clear signals do. Significant health events, new prescriptions, a change in income, or moving to a different area all warrant a fresh look at coverage. Enrollment windows and plan cancellation rules also create deadlines you’ll want to respect. Pay attention to notices from insurers that outline benefit changes or rate hikes.
Mark these triggers on your calendar and treat them as prompts to gather recent medical bills and policy documents. Acting early often opens more options and avoids penalties.
What to Compare First
Start with the elements that affect your wallet and everyday access to care. Compare premiums, annual deductibles, copays, and prescription drug tiers to see where costs have climbed. Check whether your regular providers and preferred pharmacies remain in-network and review coverage limits for services you use frequently. Look for exclusions or waiting periods that might matter if you anticipate specific treatments.
- Premiums vs. expected usage
- Deductible and out-of-pocket maximums
- Provider networks and prescription tiers
Focus comparisons on the few items that would change your annual budget the most. That narrows choices and speeds decision-making.
Costs, Discounts, and Coordination
Beyond headline prices, see how plans work with other coverage you have. Some supplemental policies coordinate benefits with a primary plan; others pay first and leave gaps. Ask about available discounts for multi-policy holders, prompt renewals, or automatic payments. Also verify how switching plans impacts short-term coverage, especially for chronic conditions.
Understanding coordination helps avoid paying twice or losing a benefit when you change carriers. Small savings tactics add up over a year.
Practical Steps to Make Changes
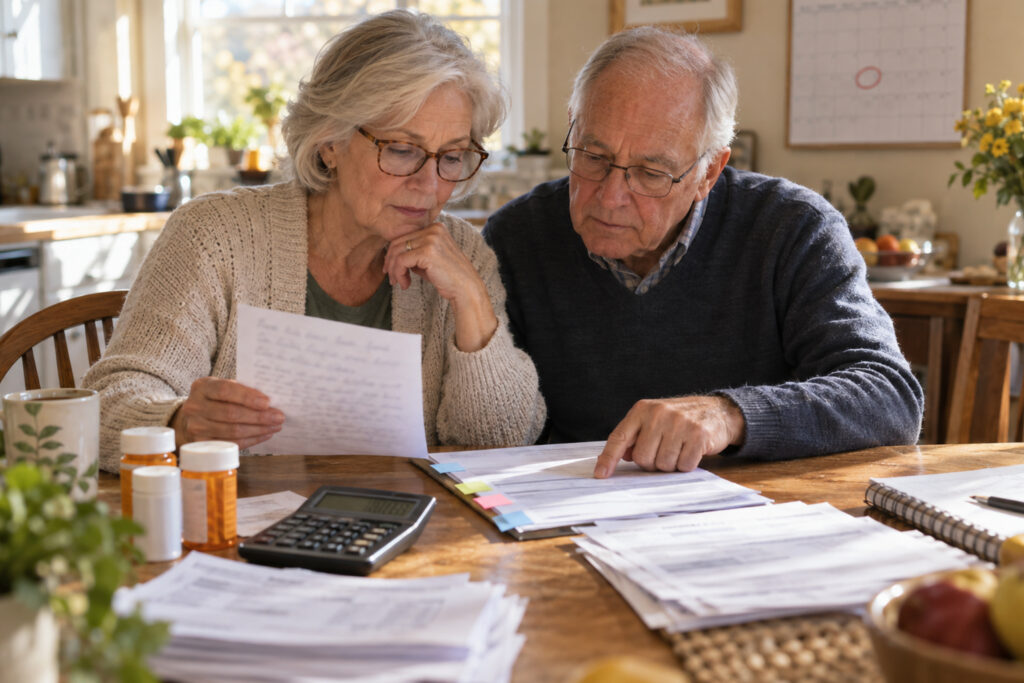
Gather the last year of medical bills, medication lists, and current policy summaries before you call insurers or brokers. Request written quotes showing total yearly costs, not just monthly premiums, and read exclusions closely. If you find better coverage, confirm effective dates, any waiting periods, and cancellation procedures for your current plan. Keep records of conversations and written offers to prevent surprises later.
Move deliberately: compare, confirm, and only then commit. A steady process reduces regret and keeps coverage aligned with real needs.
Conclusion
Regular, targeted reviews let you keep coverage that matches current health and budget realities. Start with clear triggers and compare the few items that affect your annual costs most. Small, informed changes usually deliver better protection and less financial strain.