Credit cards are useful tools but they can clutter your month if you treat them like random options.
A short, repeatable routine keeps rewards flowing and bills from surprising you.
You don’t need dozens of rules—just a clear primary plan and two supporting habits.
This article lays out three simple steps you can use every month to stay organized.
Pick One Primary Card and a Backup
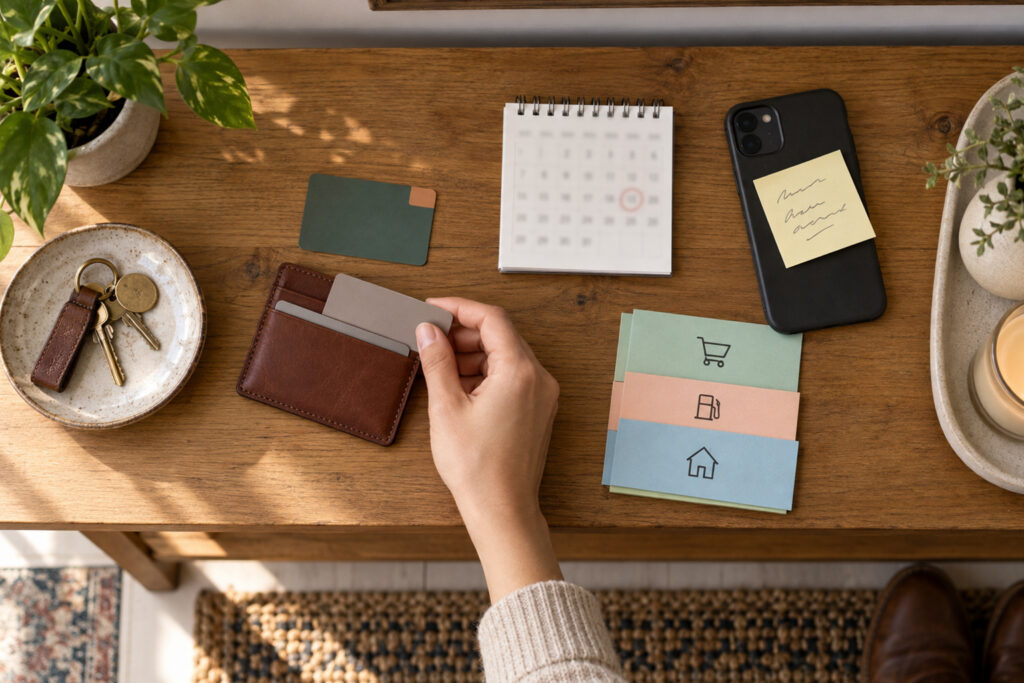
Choose a single card for most everyday purchases so you build predictable reward totals and simplify tracking. Let the primary card cover groceries, gas, and recurring subscriptions where it has the best return. Designate a backup for categories where the primary is weak or for emergency use, and store both in your wallet. Keep reward categories aligned with large planned purchases like annual insurance or holiday shopping.
Keep the backup seldom used so you preserve credit history and avoid unnecessary balances. Rotate cards only when a clear seasonal benefit appears. Keep a small note in your phone listing each card’s main benefit.
Match Cards to Monthly Spending Categories
Review your last two months of statements to spot where you actually spend money, not where you think you do. Assign one card for fixed monthly bills, another for variable categories like dining or travel, and use the primary for everything else. Use calendar reminders to switch cards on specific bill days rather than trying to remember mid-shopping. Reassess the assignments if your spending shifts seasonally or after big life changes.
This small mapping reduces missed reward opportunities and reduces impulse switching. It also helps you evaluate whether a card’s annual fee is justified. If you find overlaps, simplify by consolidating cards to reduce friction.
Lock Down Payment Dates and Watch Fees
Put payment dates a few days after payday to make on-time payments easier and reduce late fees. Set up autopay for at least the minimum and schedule a second reminder to pay the full statement balance. Check annual fees and balance transfer offers quarterly so you avoid surprises and keep costs low. Watch foreign transaction fees and merchant surcharges when traveling or shopping online.
If a card no longer earns rewards that match your habits, replace or close it thoughtfully. Small, regular reviews prevent small leaks from becoming big expenses. A modest routine saves interest and preserves the conveniences cards provide.
Conclusion
A three-step monthly routine takes minutes and prevents headaches.
Focus on one primary card, match cards to real spending, and lock payment timing.
Do a quick quarterly review and adjust as your life changes.