Aligning Credit Cards With Your Monthly Spending Goals
Introduction
Using multiple credit cards need not be confusing when you match each card to a clear purpose. Setting simple rules for which card to use for groceries, bills, or travel reduces decision fatigue and helps you capture rewards. A consistent approach also makes tracking spending and monitoring statements easier, lowering the risk of missed payments. This article outlines a practical framework to assign cards, prioritize payments, and keep accounts secure without overcomplicating your routine. With a few adjustments you can simplify choices and improve financial outcomes.
Map Your Cards to Spending Categories
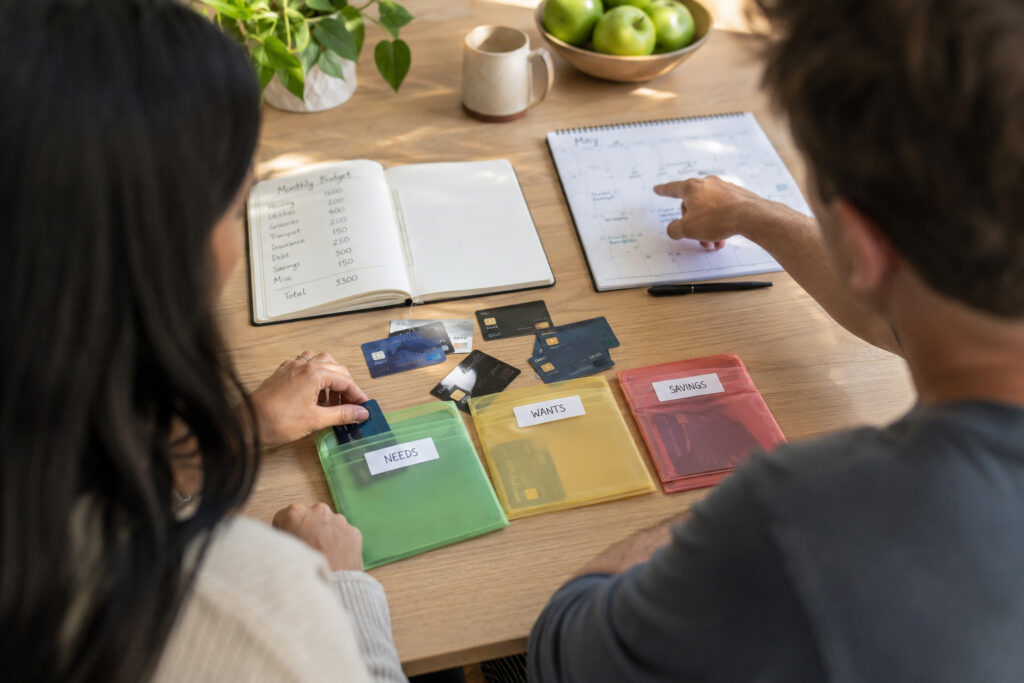
Start by listing each card and the categories where it earns the most value. Identify one primary card for everyday purchases, one for recurring bills, and a backup for large or unexpected expenses. If you have a travel or dining card, reserve it for those specific purchases to extract maximal rewards. Avoid juggling too many rotating categories to keep the system manageable.
Document the rules in a note on your phone or in your budget app so you can follow them easily. Regular use helps you remember which card to reach for and prevents scattered spending.
Manage Interest and Payment Priorities
Rewards are valuable only if you avoid paying interest that erases them. Prioritize paying off high-interest balances first, and consider keeping a low-interest or zero-interest transfer option for emergencies. Automate at least the minimum payments to prevent late fees, then schedule extra payments toward the highest-rate card. Reviewing due dates and aligning them with cash flow reduces stress and missed payments.
If you must carry a balance temporarily, be intentional about the timeline and the payoff plan. Small extra payments each month can significantly reduce interest over time.
Security, Maintenance, and Review
Periodically review statements to spot unfamiliar charges and to confirm you are still getting the anticipated rewards. Keep contact information current and enable notifications for transactions and card changes to catch issues early. Close or downgrade cards only when necessary, as account age and available credit affect your credit profile. A yearly check lets you reassess whether each card still earns worthwhile value versus the annual fee.
Consolidate statements and logins in a secure password manager to streamline oversight. Routine maintenance preserves benefits while keeping risk low.
Conclusion
A purposeful card strategy reduces friction and helps you earn more from ordinary spending. By assigning clear roles, prioritizing high-interest payoff, and maintaining regular reviews, you can simplify credit card management. Small, consistent habits deliver greater financial control over time.