Practical Choices for Smarter Supplemental Health Coverage

Choosing supplemental health coverage can feel like sorting through a maze of options, premiums, and fine print. Start by clarifying what your base plan already pays for and where it leaves you exposed. Think about the services you use regularly and the expenses that would hurt your budget if they weren’t covered. A clear list of those risks makes the rest of the process far more purposeful.

Begin with realistic expectations about what insurance will do and what it will not. Keep the focus on practical protection rather than trying to eliminate every possible cost.

Start with a clear inventory

Begin by listing the benefits your primary insurance covers and marking the gaps: deductibles, co-payments, long hospital stays, or outpatient services. Include likely near-term needs such as prescription medication, routine dental work, or planned procedures. Knowing the dollar amounts attached to those gaps helps you compare plans like-for-like. This step prevents buying redundant coverage that adds cost without meaningful extra protection.

Documenting recent medical bills and expected expenses makes choices concrete rather than abstract. Keep those notes handy when reviewing quotes or talking to an agent.

Match coverage to likely needs

Not every extra benefit is worth the same to every person; align options with your personal health picture. For example, if prescriptions are your main expense, a plan that offers lower drug co-pays may be more valuable than broader hospitalization benefits. If mobility or dental work looms ahead, prioritize those riders instead. Aim to cover the highest-probability, highest-cost items first.

  • Prescription cost-sharing for chronic meds
  • Hospital indemnity for occasional long stays
  • Dental and vision for planned maintenance

Focus on a small set of priorities to keep premiums reasonable and benefits targeted. That balance is the heart of smart supplemental planning.

Weigh cost against real benefits

Compare annual premiums against the out-of-pocket exposure each plan reduces. A lower premium can be tempting but might leave you facing large bills for a single event. Look at maximum out-of-pocket limits and what triggers full benefits, not just the headline premium. Also consider how a plan coordinates with other insurance rather than overlaps unnecessarily.

Run simple scenarios: what happens if you need a week-long hospital stay or several months of specialty medication. Those quick calculations reveal which plans truly protect your finances.

Watch for exclusions and timing

Read exclusions carefully and note waiting periods, pre-existing condition clauses, and enrollment windows. Some benefits only start after a waiting period or exclude certain services forever, which can make a policy less useful when you need it. Timing matters: missing an enrollment window can mean limited options or higher costs later. Ask clear questions and get answers in writing when a policy detail is important to you.

Keep renewal dates and annual review reminders on your calendar so coverage still fits your needs next year. A small review each season can save surprises down the road.

Conclusion

Practical supplemental coverage begins with a clear list of gaps and likely expenses. Match benefits to those needs, compare real costs against potential savings, and check exclusions and timing carefully. With focused choices and an annual review, you can secure useful protection without paying for what you don’t need.
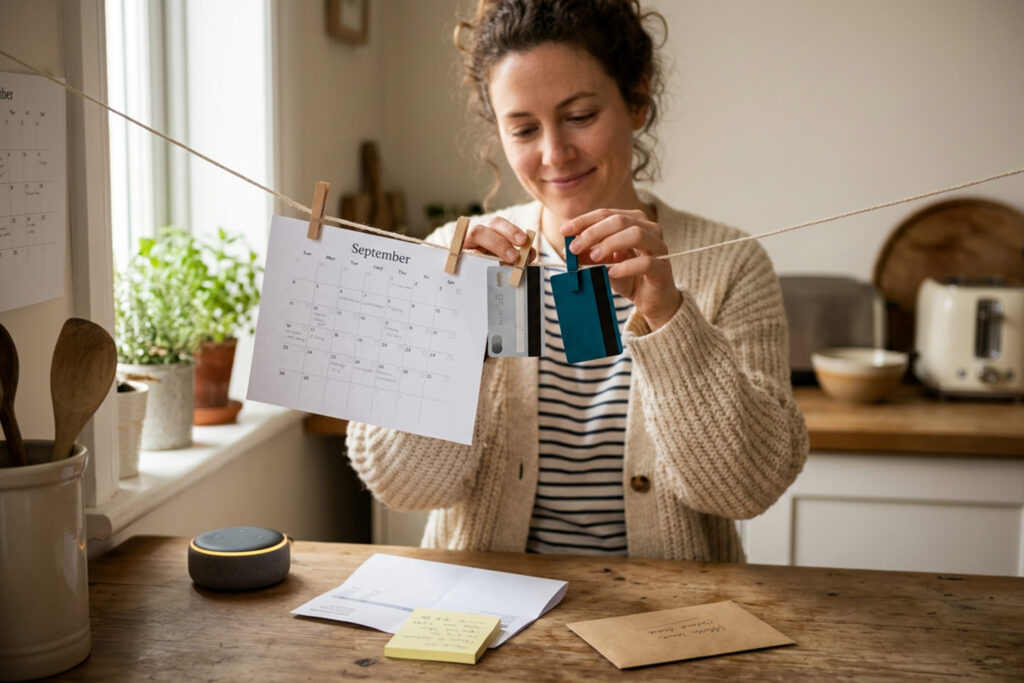
Pay Smarter, Not Harder: Building Better Credit Habits

Small, consistent choices about when and how you use credit shape the scores lenders see. This article focuses on practical moves you can adopt without overhauling your entire budget. Pick a couple of tactics and stick with them for a few months to see steady improvements. The goal is momentum: gradual progress that becomes routine.

Prioritize Payment Timing

Paying on time is the single most influential habit for most credit scores, and timing matters more than many people realize. Set payments a few days before the due date and align them with your pay schedule so you never miss a cycle. If you struggle with one account, move its due date or set an automated partial payment immediately after payday. Consistent punctual payments build a reliable history that lenders favor.

Automate where it helps and review statements monthly to catch stray charges. Even small late fees or a missed payment can slow progress, so make timing a simple protective routine.

Lower Utilization, Raise Scores

Credit utilization—the percent of available revolving credit you use—is a fast-moving factor you can influence. Try to keep utilization under roughly 30% on each card and overall, and aim lower if you want quicker gains. If a statement balance is high one month, make an extra payment before the statement closing date to reduce the reported balance. Increasing your credit limit can also help, but only if it doesn’t encourage more spending.

Watch each account’s reported balance rather than just your current balance. Small, repeated reductions will help the score reflect safer borrowing behavior.

Keep Accounts Active Strategically

The age and diversity of accounts contribute to credit profiles, so closing old cards can sometimes do more harm than good. Use older accounts occasionally for small purchases you pay off quickly to keep them active. For new accounts, resist opening several at once because multiple inquiries and a shortened average age can weigh on your score. Think of each account as a long-term piece of your credit history.

Maintain a balance between keeping older accounts open and avoiding unnecessary new ones. Strategic activity protects your credit age and mix over time.

Monitor and Correct Your Report

Regularly checking your credit report reveals mistakes and unexpected activity that could drag your score down. Dispute clear errors promptly and follow up until they’re corrected; even one erroneous late payment can have a large effect. Monitoring alerts also helps you spot identity issues early, letting you act before larger problems develop.

Use free annual reports and low-cost monitoring tools as suits your comfort level. Knowing what’s on your report gives you control to make informed, corrective decisions.

Conclusion

Small, repeatable payment and usage habits reliably change credit trends over months rather than overnight. Focus on timing, utilization, account management, and regular checking to build credit with confidence. Consistency matters more than perfection, and steady choices add up.

A Few Habits That Keep Credit Cards Simple

Credit cards don’t have to be a source of stress. With a handful of steady habits you can keep rewards, payment timing, and fees under control. This article focuses on small routines that prevent surprises and preserve your cashflow. Adopt one change at a time and you’ll see how little adjustments add up.

Start with clear purposes for each card, then move to practical payment habits that fit your calendar. Small, repeatable actions are easier to maintain than grand financial overhauls. The goal is predictability, not perfection.

Choose Two Primary Cards

Most people only need two main cards: one for everyday spending and one for larger purchases or rotating rewards. Keeping to two limits decision fatigue and makes monitoring balances simpler. Pick cards with complementary benefits so you’re not duplicating categories or annual fees. Avoid chasing every bonus; consistency wins.

Having a backup card for emergencies is fine, but keep it inactive for routine charges. That reduces fraud exposure and keeps your credit utilization clear.

Match Cards to Regular Spending

Identify three regular categories where you spend most: groceries, gas and utilities, for example. Assign each category to the card that offers the best return and habitually use that card for those purchases. If a card has rotating categories, note activation and start dates so you don’t miss higher rewards. A simple labeled wallet or app note can prevent slip-ups.

When rewards change, review and reassign categories quarterly. This keeps your setup aligned with real spending without constant overthinking.

Pay on a Rhythm That Fits Your Cashflow

Pick a payment rhythm tied to paydays: one principal payment right after you get paid, and a final statement payoff before the due date. That approach reduces interest risk and keeps balances predictable. If you can, set autopay for the minimum and manually clear the rest on payday to avoid overdrafts. Treat the card like a short-term loan, not free money.

Regular reviews of statements catch errors and subscription creep. A quick monthly check takes minutes and saves headaches later.

Protect Simple Rules With Automation

Use calendar alerts and bank rules to enforce your habits without relying on memory. Set alerts for statement closing dates, card activations, and reward category switches. If you carry a balance strategically for a large purchase, automate a plan to eliminate it within a set number of months. Automation reduces friction and keeps your plan honest.

Combine automation with one monthly habit: a five-minute review of charges and benefits. That small ritual preserves control and keeps complexity from creeping back in.

Conclusion

Keep your credit card routine small and consistent. Choose clear roles for each card, pay on a rhythm tied to your cashflow, and use automation to enforce rules. These tiny changes make credit cards predictable and useful without drama.

What Every Shopper Overlooks in Supplemental Insurance Policies

Supplemental insurance can feel like a tangle of fine print and benefit names that sound similar but behave differently.
Many buyers pick a plan because premiums look low or a familiar word appears in the title.
Those simple choices can leave gaps when a claim arrives or a preferred provider isn’t covered.
This piece points out the small items that change how a policy performs when you need it most.

Before you make any switch or add-on, take a moment to look past surface features and understand the mechanics behind them.

Why the fine print matters

Two policies with the same monthly cost can pay out very differently depending on limits, waiting periods, and exclusions. Read the clauses about preexisting conditions, lifetime caps, and what counts as a covered event; they often determine real value more than the headline benefit. Pay attention to how benefits are triggered — some plans require a hospital stay, others pay for outpatient procedures, and that affects whether you’ll see reimbursement. Also note whether inflation or annual adjustments are built in, since fixed-dollar benefits lose buying power over time.

  • Look for definitions of key terms like “disability” or “qualified provider.”
  • Check how long the insurer has to respond to claims and appeals.

Those items won’t be highlighted in marketing, but they control the speed and amount of any payout. A quick scan now saves frustration later.

Commonly overlooked policy items

People often skip details about network rules, coordination with other insurance, and rider exclusions. Network restrictions can force you to use providers who accept the plan, or leave you paying much more out of pocket for out-of-network care. Coordination clauses explain whether the supplemental plan pays before or after your primary coverage, which affects your immediate bills. Riders and add-ons may seem inexpensive until you realize they duplicate benefits you already have elsewhere.

  • Out-of-network penalties and referral requirements.
  • How the policy interacts with employer or government benefits.
  • Whether certain treatments require prior authorization.

Spotting these items ensures the policy fills genuine gaps instead of offering redundant or unusable coverage. It also helps you compare apples to apples.

Checklist to review before you commit

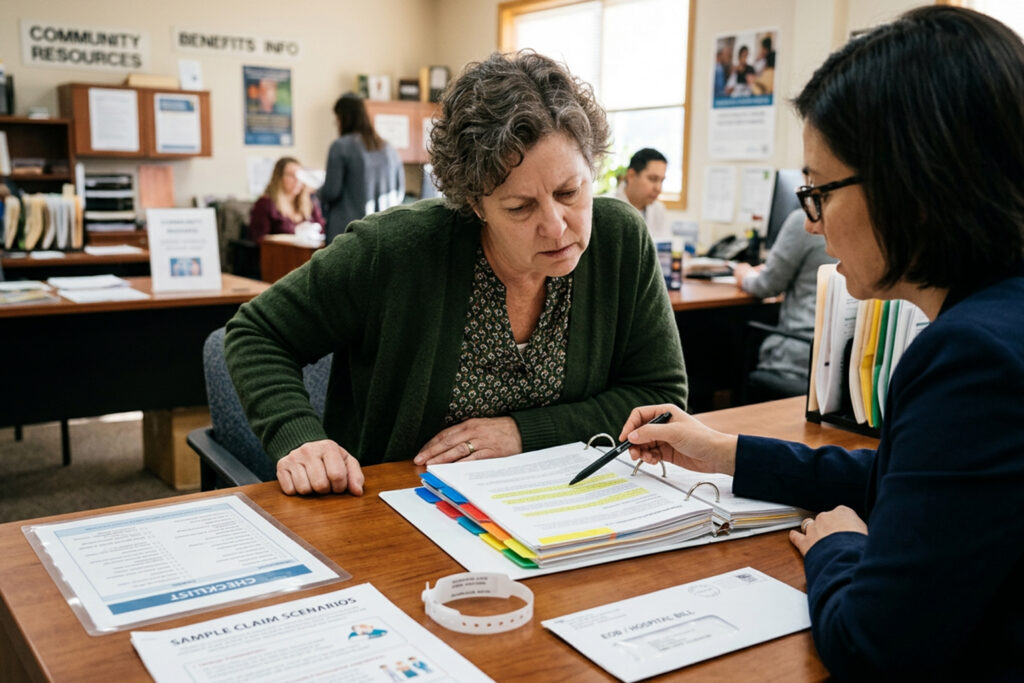
Put a short checklist together: definitions, limits, waiting periods, network rules, coordination, and appeals procedures. Ask for sample claim scenarios from the insurer so you can see how benefits would apply in practice. Confirm any verbal assurances in writing and note the effective date for coverage changes. Finally, compare the total expected annual cost — premiums plus likely out-of-pocket expenses — not just the monthly price.

  • Request a copy of the policy and read highlighted clauses.
  • Call customer service with specific hypothetical claims to test responses.
  • Check review periods and cancellation terms.
  • Make sure any agent promises are included in the contract.

These steps help you choose a plan that behaves as you expect when you claim. They also reduce surprises and make comparisons clearer.

Conclusion

Small policy details often determine whether supplemental coverage actually helps when you need it.
Spend time on definitions, limits, and how the plan works with other coverage before you buy.
A focused review now will protect your finances and give you clearer peace of mind later.

Timing, Limits, and Checks: A Quiet Plan for Better Credit

Small, consistent choices have more impact on credit than dramatic one-off moves.
If you focus on when you pay, how much credit you use, and whether your reports are accurate, scores tend to improve steadily.
This piece lays out a few practical adjustments you can make without adding stress to your day.
Read on for specific, repeatable steps that fit into ordinary routines.

Set clear payment priorities

Start by identifying the bills that matter most to scoring: on-time payments for loans and revolving accounts. Use calendar alerts or automatic payments to avoid missed due dates, but keep enough control to adjust amounts when cash is tight. If you must choose what to pay first, prioritize accounts that have recently fallen behind and those with the largest balances relative to their limits. These focused moves protect score factors that weigh most heavily in most scoring models.

Make a weekly review part of your routine so payments stay on track. A short check-in helps catch anomalies before they become delinquencies.

Manage balances and credit limits

Credit utilization—the ratio of your balances to available limits—affects scores quickly. Aim to keep utilization well below the apparent maximum by paying down cards during the billing cycle, not just at statement due date. If you can, request higher limits on stable accounts; that reduces utilization without increasing debt. Avoid opening multiple new accounts at once, as new inquiries and new limits can temporarily lower a score.

Small reductions in utilization often produce visible score improvement. Treat limits like a tool rather than extra spending room.

Use tools that reduce friction

Technology makes staying on top of credit simpler than ever. Set up autopay for fixed amounts, enable text or app alerts for high balances, and schedule monthly time to reconcile statements. For unpredictable months, lower an autopay temporarily and plan a catch-up when cash is steadier. These modest systems stop reactive scrambling and reduce the chance of errors or missed payments.

  • Autopay for minimums, manual top-ups for extra reductions.
  • Alerts for balances above chosen thresholds.

Build these protections gradually so they become habits, not chores. Consistency matters more than perfection.

Monitor reports and fix mistakes

Errors on credit reports are common and removable, but they won’t correct themselves. Check reports at least once a year and dispute any inaccuracies promptly. If identity theft or a billing mistake shows up, act quickly with the creditor and the reporting agency to file disputes and document responses. Even small, corrected errors can lift a score faster than months of careful payments.

Keep a simple folder or digital record of disputes and outcomes. That documentation speeds follow-ups if issues reappear.

Conclusion

Small timing adjustments, disciplined balance management, and routine checks add up over months.
They reduce risk of setbacks while nudging scores upward in measurable ways.
Stick to practical systems and review results periodically to stay on course.

A Calm, Practical Plan to Manage Credit Cards

Credit cards can be useful tools without feeling like a burden if you adopt a few steady routines. This piece lays out a short, practical approach you can start today to reduce stress and keep benefits. No jargon, no gimmicks—just clear steps that fit regular life. Read on for straightforward ways to bring order to your wallet and monthly calendar.

Choose a primary card and a backup

Most people do best when they limit daily use to one primary card and keep a second card for emergencies or niche perks. The primary card should cover your core benefits: good rewards on the purchases you make most and a manageable interest rate if you ever carry a balance. A backup card can handle situations like a declined charge, a merchant-specific discount, or travel where the primary isn’t accepted. Having two cards keeps things simple and reduces the temptation to juggle many accounts every month.

  • Pick a rewards card that matches your regular spending categories.
  • Keep a no-annual-fee card as a reliable secondary option.
  • Store both cards with clear notes about when to use each.

With the hierarchy in place, tracking and paying bills becomes easier. You’ll stop hunting for the “best” card for every purchase, and your statement review will take minutes instead of hours.

Match cards to recurring spending

Assign cards to cover predictable, recurring charges like utilities, subscriptions, or groceries. That consistency maximizes rewards and reduces the mental load of deciding which card to use at checkout. Put recurring charges on a card with category bonuses or the most relevant protection benefits. If a subscription moves or a rate changes, update which card handles it rather than letting multiple small charges scatter across accounts.

Automation helps: set automatic payments from a checking account you review monthly. That way you preserve rewards while avoiding late fees or interest surprises.

Use billing cycles and payment timing

Understanding billing cycles gives you a small cash-flow advantage without borrowing. If you time large planned purchases right after your statement closes, you effectively get an extra few weeks before payment is due. Mark the statement close date and due date in your calendar to plan spending and transfers. Pay at least the statement balance by the due date to avoid interest, and consider splitting payments if a single large charge would strain your budget.

  • Set one recurring payment date that aligns with your paycheck schedule.
  • Enable payment reminders a few days before due dates.
  • Use autopay for the statement balance, not the minimum.

Small timing habits like these reduce stress and protect your credit score while letting you continue to earn rewards.

Conclusion

Pick one primary card and a backup, match cards to regular spending, and plan around billing cycles. These three habits make cards predictable and useful without extra effort. Start with one change and build the routine from there.

Practical Choices for Smarter Supplemental Health Coverage

Choosing supplemental health coverage can feel like sorting through a maze of options, premiums, and fine print. Start by clarifying what your base plan already pays for and where it leaves you exposed. Think about the services you use regularly and the expenses that would hurt your budget if they weren’t covered. A clear list of those risks makes the rest of the process far more purposeful.

Begin with realistic expectations about what insurance will do and what it will not. Keep the focus on practical protection rather than trying to eliminate every possible cost.

Start with a clear inventory

Begin by listing the benefits your primary insurance covers and marking the gaps: deductibles, co-payments, long hospital stays, or outpatient services. Include likely near-term needs such as prescription medication, routine dental work, or planned procedures. Knowing the dollar amounts attached to those gaps helps you compare plans like-for-like. This step prevents buying redundant coverage that adds cost without meaningful extra protection.

Documenting recent medical bills and expected expenses makes choices concrete rather than abstract. Keep those notes handy when reviewing quotes or talking to an agent.

Match coverage to likely needs

Not every extra benefit is worth the same to every person; align options with your personal health picture. For example, if prescriptions are your main expense, a plan that offers lower drug co-pays may be more valuable than broader hospitalization benefits. If mobility or dental work looms ahead, prioritize those riders instead. Aim to cover the highest-probability, highest-cost items first.

  • Prescription cost-sharing for chronic meds
  • Hospital indemnity for occasional long stays
  • Dental and vision for planned maintenance

Focus on a small set of priorities to keep premiums reasonable and benefits targeted. That balance is the heart of smart supplemental planning.

Weigh cost against real benefits

Compare annual premiums against the out-of-pocket exposure each plan reduces. A lower premium can be tempting but might leave you facing large bills for a single event. Look at maximum out-of-pocket limits and what triggers full benefits, not just the headline premium. Also consider how a plan coordinates with other insurance rather than overlaps unnecessarily.

Run simple scenarios: what happens if you need a week-long hospital stay or several months of specialty medication. Those quick calculations reveal which plans truly protect your finances.

Watch for exclusions and timing

Read exclusions carefully and note waiting periods, pre-existing condition clauses, and enrollment windows. Some benefits only start after a waiting period or exclude certain services forever, which can make a policy less useful when you need it. Timing matters: missing an enrollment window can mean limited options or higher costs later. Ask clear questions and get answers in writing when a policy detail is important to you.

Keep renewal dates and annual review reminders on your calendar so coverage still fits your needs next year. A small review each season can save surprises down the road.

Conclusion

Practical supplemental coverage begins with a clear list of gaps and likely expenses. Match benefits to those needs, compare real costs against potential savings, and check exclusions and timing carefully. With focused choices and an annual review, you can secure useful protection without paying for what you don’t need.
Pay Smarter, Not Harder: Building Better Credit Habits

Small, consistent choices about when and how you use credit shape the scores lenders see. This article focuses on practical moves you can adopt without overhauling your entire budget. Pick a couple of tactics and stick with them for a few months to see steady improvements. The goal is momentum: gradual progress that becomes routine.

Prioritize Payment Timing

Paying on time is the single most influential habit for most credit scores, and timing matters more than many people realize. Set payments a few days before the due date and align them with your pay schedule so you never miss a cycle. If you struggle with one account, move its due date or set an automated partial payment immediately after payday. Consistent punctual payments build a reliable history that lenders favor.

Automate where it helps and review statements monthly to catch stray charges. Even small late fees or a missed payment can slow progress, so make timing a simple protective routine.

Lower Utilization, Raise Scores

Credit utilization—the percent of available revolving credit you use—is a fast-moving factor you can influence. Try to keep utilization under roughly 30% on each card and overall, and aim lower if you want quicker gains. If a statement balance is high one month, make an extra payment before the statement closing date to reduce the reported balance. Increasing your credit limit can also help, but only if it doesn’t encourage more spending.

Watch each account’s reported balance rather than just your current balance. Small, repeated reductions will help the score reflect safer borrowing behavior.

Keep Accounts Active Strategically

The age and diversity of accounts contribute to credit profiles, so closing old cards can sometimes do more harm than good. Use older accounts occasionally for small purchases you pay off quickly to keep them active. For new accounts, resist opening several at once because multiple inquiries and a shortened average age can weigh on your score. Think of each account as a long-term piece of your credit history.

Maintain a balance between keeping older accounts open and avoiding unnecessary new ones. Strategic activity protects your credit age and mix over time.

Monitor and Correct Your Report

Regularly checking your credit report reveals mistakes and unexpected activity that could drag your score down. Dispute clear errors promptly and follow up until they’re corrected; even one erroneous late payment can have a large effect. Monitoring alerts also helps you spot identity issues early, letting you act before larger problems develop.

Use free annual reports and low-cost monitoring tools as suits your comfort level. Knowing what’s on your report gives you control to make informed, corrective decisions.

Conclusion

Small, repeatable payment and usage habits reliably change credit trends over months rather than overnight. Focus on timing, utilization, account management, and regular checking to build credit with confidence. Consistency matters more than perfection, and steady choices add up.

A Few Habits That Keep Credit Cards Simple

Credit cards don’t have to be a source of stress. With a handful of steady habits you can keep rewards, payment timing, and fees under control. This article focuses on small routines that prevent surprises and preserve your cashflow. Adopt one change at a time and you’ll see how little adjustments add up.

Start with clear purposes for each card, then move to practical payment habits that fit your calendar. Small, repeatable actions are easier to maintain than grand financial overhauls. The goal is predictability, not perfection.

Choose Two Primary Cards

Most people only need two main cards: one for everyday spending and one for larger purchases or rotating rewards. Keeping to two limits decision fatigue and makes monitoring balances simpler. Pick cards with complementary benefits so you’re not duplicating categories or annual fees. Avoid chasing every bonus; consistency wins.

Having a backup card for emergencies is fine, but keep it inactive for routine charges. That reduces fraud exposure and keeps your credit utilization clear.

Match Cards to Regular Spending

Identify three regular categories where you spend most: groceries, gas and utilities, for example. Assign each category to the card that offers the best return and habitually use that card for those purchases. If a card has rotating categories, note activation and start dates so you don’t miss higher rewards. A simple labeled wallet or app note can prevent slip-ups.

When rewards change, review and reassign categories quarterly. This keeps your setup aligned with real spending without constant overthinking.

Pay on a Rhythm That Fits Your Cashflow

Pick a payment rhythm tied to paydays: one principal payment right after you get paid, and a final statement payoff before the due date. That approach reduces interest risk and keeps balances predictable. If you can, set autopay for the minimum and manually clear the rest on payday to avoid overdrafts. Treat the card like a short-term loan, not free money.

Regular reviews of statements catch errors and subscription creep. A quick monthly check takes minutes and saves headaches later.

Protect Simple Rules With Automation

Use calendar alerts and bank rules to enforce your habits without relying on memory. Set alerts for statement closing dates, card activations, and reward category switches. If you carry a balance strategically for a large purchase, automate a plan to eliminate it within a set number of months. Automation reduces friction and keeps your plan honest.

Combine automation with one monthly habit: a five-minute review of charges and benefits. That small ritual preserves control and keeps complexity from creeping back in.

Conclusion

Keep your credit card routine small and consistent. Choose clear roles for each card, pay on a rhythm tied to your cashflow, and use automation to enforce rules. These tiny changes make credit cards predictable and useful without drama.

When to Update Supplemental Insurance and What to Change

As health needs, routines, and finances shift in retirement, supplemental insurance that once fit your life can drift out of step. Small changes — a new medication, a recent hospital stay, or a tighter monthly budget — often reveal unexpected gaps or unnecessary costs. Rather than react under pressure, a brief, regular review makes it easier to spot mismatches and act deliberately. This piece explains common triggers for a review, the first things to compare, and practical steps to adjust coverage without confusion.

Periodic checks don’t mean constant upheaval; they mean smarter choices. A short checklist and a set schedule make updates manageable and less stressful.

When to Revisit Your Plan

Not every change requires an immediate switch, but several clear signals do. Significant health events, new prescriptions, a change in income, or moving to a different area all warrant a fresh look at coverage. Enrollment windows and plan cancellation rules also create deadlines you’ll want to respect. Pay attention to notices from insurers that outline benefit changes or rate hikes.

Mark these triggers on your calendar and treat them as prompts to gather recent medical bills and policy documents. Acting early often opens more options and avoids penalties.

What to Compare First

Start with the elements that affect your wallet and everyday access to care. Compare premiums, annual deductibles, copays, and prescription drug tiers to see where costs have climbed. Check whether your regular providers and preferred pharmacies remain in-network and review coverage limits for services you use frequently. Look for exclusions or waiting periods that might matter if you anticipate specific treatments.

  • Premiums vs. expected usage
  • Deductible and out-of-pocket maximums
  • Provider networks and prescription tiers

Focus comparisons on the few items that would change your annual budget the most. That narrows choices and speeds decision-making.

Costs, Discounts, and Coordination

Beyond headline prices, see how plans work with other coverage you have. Some supplemental policies coordinate benefits with a primary plan; others pay first and leave gaps. Ask about available discounts for multi-policy holders, prompt renewals, or automatic payments. Also verify how switching plans impacts short-term coverage, especially for chronic conditions.

Understanding coordination helps avoid paying twice or losing a benefit when you change carriers. Small savings tactics add up over a year.

Practical Steps to Make Changes

Gather the last year of medical bills, medication lists, and current policy summaries before you call insurers or brokers. Request written quotes showing total yearly costs, not just monthly premiums, and read exclusions closely. If you find better coverage, confirm effective dates, any waiting periods, and cancellation procedures for your current plan. Keep records of conversations and written offers to prevent surprises later.

Move deliberately: compare, confirm, and only then commit. A steady process reduces regret and keeps coverage aligned with real needs.

Conclusion

Regular, targeted reviews let you keep coverage that matches current health and budget realities. Start with clear triggers and compare the few items that affect your annual costs most. Small, informed changes usually deliver better protection and less financial strain.