A higher credit score rarely appears overnight; it grows when small behaviors become routine. Paying attention to a few everyday actions can produce steady, measurable gains over months. This article outlines straightforward, practical habits that fit into busy schedules without complicated tools. Use these steps to influence payment history, credit utilization, and account longevity in sensible ways.
These tips emphasize consistency over big moves. They aim to reduce stress while improving credit outcomes. Expect gradual change rather than instant jumps.
Why daily habits matter
Your credit score is a reflection of repeated behaviors, not single events. Payment history counts for the largest portion, so making on-time payments habitually is the most reliable lever. Credit utilization — the amount of available credit you use — responds quickly to small changes in spending and repayment patterns. Lenders and scoring models reward predictability: consistent, responsible use of credit beats erratic, high-risk activity.
Habits shape those metrics. When you automate payments, monitor balances weekly, and keep older accounts open, the combined effect nudges your score upward over time. Think of the process as steady momentum rather than a sprint.
Actions that move the needle
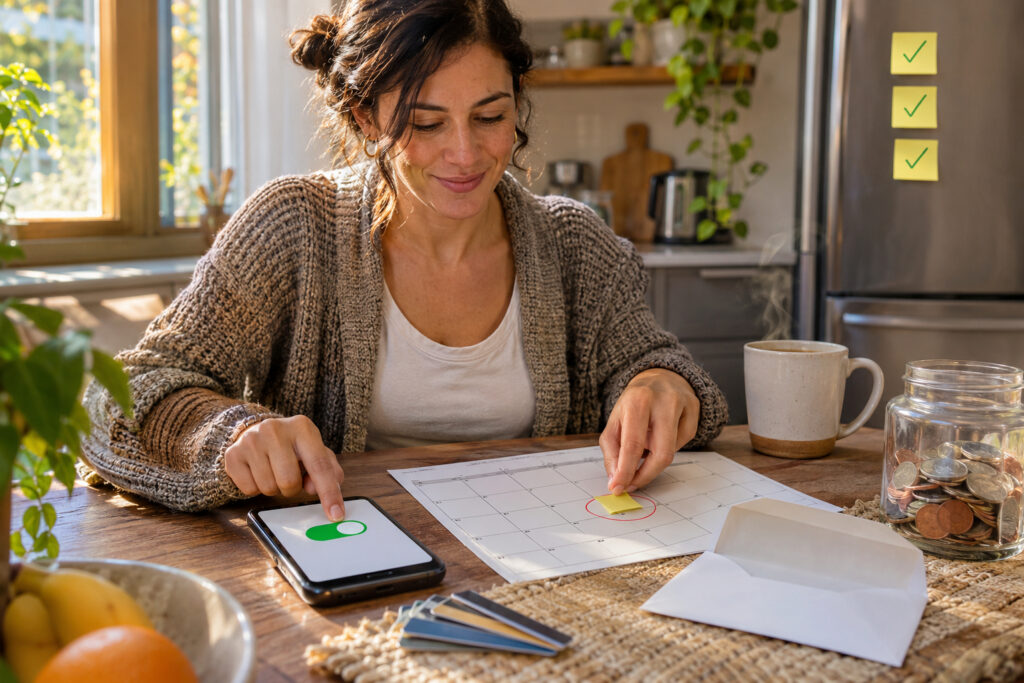
Start with the basics: set autopay for at least the minimum amount and schedule a manual check a few days before billing closes. Lowering your reported balance by even 10 percentage points of your credit limit can lift a score meaningfully. Diversifying types of credit responsibly and avoiding new, unnecessary accounts stabilizes long-term credit age. Small, repeatable steps create a track record that scoring models recognize.
- Pay on time every month, even if it’s the minimum.
- Keep card balances under about 30% of limits; lower is better.
- Hold older accounts open unless there’s a strong reason to close them.
Combine these actions gradually so they become automatic. The goal is consistent improvement with little friction.
Avoiding common setbacks
Late payments, maxed-out cards, and frequent hard inquiries are the usual suspects that undo progress. A single 30-day late payment can have an outsized negative effect compared with months of steady on-time payments. Churning through new credit applications in search of better offers can produce multiple hard pulls that temporarily suppress scores.
Guard against surprises by reviewing statements, setting alerts, and keeping an emergency buffer to avoid relying on credit for unexpected expenses. If a misstep happens, focus on returning to good habits quickly; recovery is possible with disciplined follow-through.
Conclusion
Small, consistent habits—automating payments, managing utilization, and protecting account age—add up to meaningful score improvements. Avoiding late payments and unnecessary applications helps preserve gains. Start with one manageable change and build from there.