Managing Credit Like a Long-Term Project for Growth

Credit improvement rarely follows a single dramatic move; it resembles a steady project that unfolds over months and years. Building reliable habits and tracking measurable progress turns vague goals into concrete outcomes. This article outlines practical routines and decision rules that reduce risk and support gradual score gains. The emphasis is on sustainable changes you can maintain without dramatic lifestyle shifts.

Set Clear Goals and Measure Progress

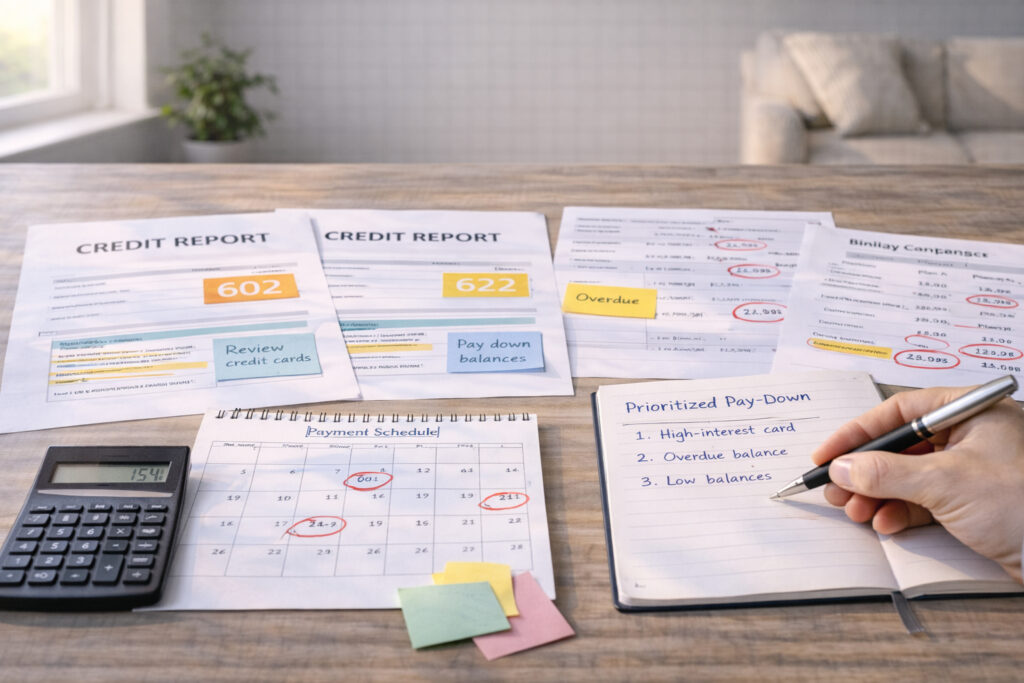
Begin by defining what a better credit profile means for you: lower interest rates, approval for a specific loan, or increased credit limits. Obtain your credit reports and identify the main drivers of your score, such as payment history, credit utilization, and account age. Track a few metrics monthly so small improvements become visible and actionable. Regular measurement reduces anxiety and helps prioritize the changes that matter most.

Establishing concrete benchmarks makes it easier to celebrate milestones and adjust strategies. Treat the process like a project plan with simple monitoring routines and periodic reviews.

Adopt Habitual Payment and Balance Rules

Consistent on-time payments are the single most important factor for many scoring models, so automate what you can to avoid lapses. Aim to keep revolving balances well under available limits; a general target is to use less than 30% of each credit line and ideally below 10% for faster gains. When possible, pay down high-interest balances first while maintaining minimum payments elsewhere. Small, repeated behaviors—like checking balances weekly—prevent surprises and reinforce control.

  • Set automatic payments for at least the minimum.
  • Make one mid-cycle payment to lower reported utilization.
  • Avoid opening new accounts just to chase offers.

Simple allocation rules and automation remove decision friction and reduce the chance of setbacks. Over time, these choices compound into measurable score improvements.

Maintain Responsible Account Mix and Age

Credit age and the diversity of account types influence long-term stability, so weigh the benefits of new accounts against the cost to average age. Keep older, healthy accounts open unless there is a compelling reason to close them. If you need new credit, consider a targeted, infrequent application strategy rather than multiple simultaneous inquiries. Thoughtful account management preserves a strong foundation while allowing targeted growth.

Long-term planning around account use helps maintain positive history and supports consistent upward movement. Regular reviews of account status prevent surprises and keep your plan on track.

Conclusion

View credit as a steady project rather than a quick fix, and prioritize predictable, repeatable behaviors. Small, consistent actions—timely payments, low utilization, and selective account management—produce reliable progress over time. Regular measurement and modest automation make the process manageable and sustainable.

Building Consistent Credit Habits for Lasting Score Gains

Improving a credit score is less about quick fixes and more about steady, intentional choices. Small changes in billing habits, account management, and credit use compound over months and years. Understanding how credit factors interact helps direct where to focus time and attention. This guide outlines practical, repeatable steps that support long-term score improvement.

Understand the Components

Credit scores are calculated from several factors that carry different weights, so it helps to know which areas matter most. Payment history and amounts owed typically dominate the score, while length of credit history, mix of credit, and recent inquiries also contribute. Reviewing a credit report regularly reveals errors, outdated information, or accounts that may be dragging the score down. Taking time to parse these elements allows for targeted, efficient improvements.

Start by obtaining your reports and checking for inaccuracies or unfamiliar accounts. Address mistakes quickly and document any disputes for future reference.

Manage Balances and Payments

Keeping balances low relative to credit limits is a straightforward way to improve the utilization component of your score. Aim to pay down high balances first and consider making multiple payments within a billing cycle to lower reported utilization. Consistently paying at least the minimum by the due date preserves payment history and prevents late-payment damage. Small, repeatable routines around payment timing can yield measurable improvements.

  • Set calendar reminders or automated payments for due dates.
  • Prioritize cards with the highest utilization percentages.
  • Use balance alerts from your bank or credit monitoring service.

These practical steps reduce risk and establish common-sense discipline. Over time, lower utilization and on-time payments work together to lift the overall score.

Use Credit Strategically Over Time

A long-term perspective helps you avoid reactive decisions that can harm credit. Avoid opening multiple new accounts at once and be cautious about closing older accounts, since account age influences length of history. When adding credit, choose options that diversify your credit mix without exceeding comfortable repayment capacity. Responsible, gradual use of credit builds a stronger profile than frequent, large changes.

Plan major credit moves—like a new loan or added card—around your broader goals. Stay patient and track progress to reinforce positive habits.

Conclusion

Consistent, small improvements compound into meaningful score gains over time. Focus on accurate reporting, timely payments, and sensible use of available credit. With patience and simple routines, anyone can strengthen their credit profile.

Building Credit Confidence: Practical Steps for Consistent Improvement

Understanding and improving your credit score is a long-term process that benefits from clear habits, accurate information, and deliberate planning. Whether you are building credit for the first time or rebuilding after setbacks, practical, measurable steps can move your score upward and expand future financing options. This article outlines strategies focused on report accuracy, credit utilization management, payment consistency, and informed account decisions. By implementing these tactics steadily you can strengthen your profile and position yourself for better borrowing terms when the need arises.

Check Your Reports and Correct Errors

Start by pulling your credit reports from available sources and reading each entry carefully to spot inaccuracies, duplicate accounts, or outdated personal information that might be misreported. Common mistakes such as wrong balances, misattributed payments, or unfamiliar accounts can unfairly lower your score and are often resolvable through formal dispute processes with the reporting agencies. Use official reporting channels to file disputes, include supporting documentation, and follow up in writing while you retain all correspondence until items are corrected. Regular checks reduce surprises, help you identify potential identity theft early, and give you a clearer baseline for tracking real progress.

Addressing errors promptly prevents them from dragging your score down over time and frees you to focus on legitimate credit-building activities. Set a schedule to make report reviews and documentation a routine part of your financial maintenance.

Control Utilization and Manage Payments

Credit utilization — the percentage of available credit you are using at any time — is a major scoring factor and keeping it low consistently helps your overall rating. Aim to keep balances well below limits, spread out spending across accounts where sensible, and consider making multiple small payments through the month so lower amounts are reported. On-time payments are equally critical; even a single missed or late payment can have a lasting negative impact that takes years to diminish. Automated payments, calendar reminders, and modest budget adjustments reduce the chance of missed due dates and improve consistency across billing cycles.

Small changes in payment timing and balance management can create measurable improvements over several billing cycles. Track utilization trends rather than fixating on daily fluctuations to see meaningful patterns.

Use Credit Strategically and Monitor Progress

Avoid opening many new accounts at once, since multiple hard inquiries and a quickly changing account mix can temporarily lower your score and shorten average account age. When possible maintain older accounts in good standing, close only those that are unnecessary, and consider adding a responsible mix of installment and revolving credit gradually if it meets your needs. For those with limited history, authorized user arrangements, secured cards, or small installment loans can help establish positive history when managed responsibly. Regularly track your score and key metrics, set realistic milestones, and measure the impact of each strategy to make informed adjustments over time.

Patience and consistency are central because meaningful gains often appear over several months rather than overnight. Combine disciplined habits with periodic reassessment to sustain long-term improvement and avoid short-term setbacks.

Conclusion

Improving credit takes deliberate actions: correct errors, manage utilization, and pay reliably. Adopt these practices consistently and monitor progress to protect and strengthen your financial profile. Over time, small, steady changes create greater borrowing options and better terms.

How to Use Timing and Balances to Boost Credit

Improving your credit score is often the result of steady, practical habits rather than dramatic one-off moves.
Two of the most effective levers are when you make payments and how you manage account balances.
Small adjustments to payment timing and reported balances can produce measurable changes over a few billing cycles.
This article breaks down simple actions you can adopt to influence those factors and build upward momentum.

Timing Matters: How Payment Dates Affect Scores

Payment history is the dominant factor in most scoring systems, so avoiding late payments is paramount and timing plays an underappreciated role.
Many creditors report the balance on your statement closing date, so a payment made after that date may still show a high balance even if you pay the bill on time.
Scheduling payments to post before the statement closes can lower reported balances and reduce utilization, which supports score improvement.
Set calendar reminders or automatic transfers tied to your billing cycle to create reliable timing that fits your cash flow.

Start by identifying each account’s statement closing date and plan payments accordingly.
Small changes to payment dates require little effort but can adjust the information that lenders see most often.

Balances and Utilization: Keep Ratios Healthy

Credit utilization — the percentage of available credit you use — is a clear, measurable indicator of credit behavior and has a strong influence on scores.
High utilization at reporting time can pull down scores even when payments are current, so spreading balances across cards or paying down high balances before statements post helps.
Regularly review both card-level and total utilization and aim for consistent, modest usage rather than large, erratic swings.
Remember that lowering reported balances is often more impactful than reducing the balance after reporting, so timing those reductions matters.

Prioritize accounts with the highest utilization or interest rates when allocating extra payments.
Using small, frequent payments can smooth spikes and demonstrate steady management to scoring algorithms.

Practical Routines and Tools to Apply

Make routines simple and repeatable: set up autopay for a safe minimum, add a scheduled mid-cycle transfer for additional reduction, and check statements weekly for surprises.
Some banks let you customize payment dates or split payments across multiple dates to ensure lower reported balances without strain.
Track your reported balances on a monthly basis so you can see the effect of timing changes and adjust if needed.
Avoid opening or closing accounts purely to tweak utilization unless you understand the long-term effects on account age and mix.

  • Identify statement closing dates for each account.
  • Schedule at least one payment to post before each closing date.
  • Monitor reported balances on your credit reports monthly.

Choose one routine to implement this month and measure its impact over two to three billing cycles.
Consistency will compound into clearer trends and give you actionable data to refine your approach.

Conclusion

Timing payments and managing balances are accessible ways to influence your credit score.
Small, repeated habits typically outperform occasional large actions when it comes to credit health.
Start with one timing or balance change and track the results over the next few cycles.

Using Credit Reports to Guide Measured Score Growth

Understanding how to use credit reports is a practical step toward steady credit score growth. A report shows payment history, balances, account types, and recent inquiries that influence scoring models. Learning to read these details reveals targeted opportunities to improve instead of making unfocused changes. Treating reports as a diagnostic tool helps prioritize actions that deliver measurable results.

Read Your Reports Carefully

Start by obtaining free credit reports from the authorized sources and review each section methodically. Look for inaccuracies in personal information, duplicated accounts, incorrect balances, or unfamiliar inquiries that could drag a score down. Disputing errors promptly with the reporting agency and the creditor can clear mistaken negatives that otherwise linger. Regular reviews also make fraud or identity theft easier to detect early.

Make a habit of checking reports on a schedule that fits your needs, such as quarterly or after major financial events. Consistent review maintains clarity about what drives your score and reduces surprises when applying for credit.

Prioritize High-Impact Actions

Not every item on a report affects your score equally, so focus on high-impact areas first. Payment history and credit utilization are among the most influential factors, so catching missed payments and lowering balances should be top priorities. Also consider the age and mix of accounts; opening too many new accounts at once can temporarily suppress a score. Addressing the few items that matter most produces the largest, fastest improvements.

Create a short list of one to three priority actions after each review and tackle them systematically. This disciplined approach prevents scattering effort across low-impact items.

Track Progress With a Simple Plan

Use the report snapshot as a baseline and record changes monthly to see trends rather than day-to-day noise. A simple spreadsheet or a trusted app can show declines in utilization, removal of errors, and the effect of on-time payments over time. Set realistic milestones and celebrate incremental wins to stay motivated through the slower phases of improvement. Tracking turns abstract scores into actionable metrics.

Review and adjust your plan periodically based on observed results and evolving priorities. Small, consistent adjustments compound into meaningful score growth.

Avoid Common Pitfalls

Avoid overreacting to short-term drops or chasing quick fixes that carry long-term costs, such as taking on expensive secured loans purely to boost score. Likewise, spreading credit applications across many lenders in a short window can create multiple hard inquiries and harm momentum. Be cautious with debt-settlement approaches that may leave lasting negative entries without guaranteed benefit. Thoughtful, patient actions typically outperform aggressive tactics.

When in doubt, rely on the report data to guide cost-benefit decisions about any credit move. Conserving discipline and patience is often the most effective path to steady improvement.

Conclusion

Credit reports are practical tools for identifying specific, high-impact improvements that raise scores over time. Regular reviews, prioritized actions, and simple tracking create a repeatable process that yields steady progress. Staying patient and avoiding quick fixes makes the gains durable and sustainable.

Understanding Credit Scores: Strategies to Strengthen Your Rating

Credit scores influence access to credit and the cost of borrowing for a wide range of financial goals, yet they are often misunderstood. This article explains how scores are built and offers clear, research-backed strategies to improve them over time. Whether you are starting to build credit or repairing a low score, practical steps, applied with consistent effort, can make a measurable difference. Read on for actionable advice, monitoring tips, and common pitfalls to avoid.

How Credit Scores Are Calculated

Credit scoring models evaluate several types of information from your credit reports to produce a numeric score that lenders use to assess risk. Payment history typically carries the most weight, followed by amounts owed, length of credit history, new credit inquiries, and mix of account types; public records and collections can also influence outcomes. Each factor interacts differently depending on the model, so two people with similar histories can receive different scores. Understanding these components helps prioritize improvements where they matter most.

  • Payment history — timeliness of payments.
  • Amounts owed — utilization rates on revolving accounts.
  • Length of history — age of accounts matters.
  • New credit — recent inquiries and accounts.
  • Credit mix — loans and credit cards combined.

Keeping these factors in mind frames effective repair strategies. Focus on the areas that have the largest impact for your situation and set realistic timelines for progress.

Practical Steps to Improve Your Score

Start by ensuring all bills are paid on time, as punctual payments build the strongest foundation for a healthy score and demonstrate reliability to future lenders. Lowering outstanding balances and targeting high utilization accounts can produce quick improvements, especially on revolving credit. Avoid opening multiple new accounts in a short period and remove inaccuracies by regularly reviewing your credit reports. Small, consistent actions compound into meaningful score gains over several months.

Consider setting up automatic payments and reminders to protect your payment history. If errors appear, dispute them promptly with the reporting agencies and keep records of communications.

Monitoring and Avoiding Common Pitfalls

Regular monitoring helps you spot identity errors, fraudulent activity, and overdue accounts before they harm your score, and it lets you track the impact of recent changes. Be cautious with credit-boosting services and understand how they affect lenders’ views of your credit profile. Relying solely on a single score snapshot can be misleading since scores change based on recent activity. A broader view, including reports from multiple bureaus, gives a clearer picture of credit health.

Use free reports and alerts to stay informed without incurring fees. Maintaining steady habits is the best defense against sudden score declines and unexpected surprises on your report.

Conclusion

Improving a credit score is a gradual process built on consistent behavior and informed choices. By prioritizing timely payments, reducing utilization, and monitoring your reports, you can strengthen your financial footing over time. Patience and persistence deliver the most reliable results.

Simple Habits That Build a Strong Credit Profile

Maintaining a healthy credit score is less about one dramatic move and more about consistent, practical habits. Small, deliberate actions over time can shift a score upward and keep it steady through life changes. This article outlines accessible steps that anyone can adopt to strengthen their credit profile. The guidance focuses on understanding reports, managing balances, using credit strategically, and ongoing protection.

Understand Your Credit Report

Begin by reviewing your credit report thoroughly to identify any errors or unfamiliar accounts. Look for incorrect balances, duplicated listings, or outdated personal information that could unfairly lower your score. Disputing inaccuracies promptly can remove negative marks and prevent future issues. Regular reviews also reveal patterns in payment history that you can improve.

  • Check account status and payment history.
  • Note hard inquiries and their timing.
  • Verify personal information for consistency.

Knowing what appears on your report gives you control and clear action steps. Make it a habit to check reports periodically to catch problems early.

Manage Balances and Payments

Payment history and utilization are two of the most influential factors in most scoring models. Aim to pay bills on time and, when possible, pay more than the minimum to reduce principal and interest. Keep credit utilization low by spreading balances across cards or requesting higher limits when appropriate. Even modest reductions in utilization can produce measurable improvements over months.

Set up reminders or automatic payments to avoid late payments, and prioritize high-interest debt to reduce costs. These behaviors create a reliable payment record that supports long-term credit health.

Strategic Use of Different Credit Types

Having a mix of credit types—such as installment loans and revolving accounts—can benefit your profile when managed responsibly. Opening new accounts strategically and maintaining older accounts can both play a role in length-of-history considerations. Avoid opening multiple accounts in a short period, which can signal risk. Choose products that match your financial plan and ability to make timely payments.

  • Installment loans: steady monthly payments.
  • Revolving credit: manage utilization carefully.

Balance diversification with simplicity to keep accounts manageable and predictable. The goal is steady, dependable credit behavior rather than complexity.

Monitor and Protect Your Score

Vigilant monitoring helps you detect fraud, identity theft, or sudden changes that require action. Use alerts, regular report checks, and secure account practices to minimize risk. If you spot suspicious activity, act quickly to dispute charges and secure accounts. Proactive steps preserve both your score and your financial peace of mind.

Keeping records of disputes and communications can streamline recovery if issues arise. Consistent oversight is a small time investment with big potential returns.

Conclusion

Building a strong credit profile is achieved through steady, manageable habits that accumulate over time. Regularly reviewing reports, paying on time, using credit thoughtfully, and monitoring activity create durable improvements. Commit to these practices and your credit health will reflect that consistency.

Daily Financial Habits That Stabilize and Protect Your Credit

Maintaining a healthy credit score starts with consistent daily habits rather than dramatic one-time changes. Small, repeatable practices influence the factors lenders and scoring models consider most. This article outlines practical behaviors you can adopt immediately to stabilize and protect your credit over time. Adoptable routines help avoid common pitfalls and build resilience in your financial profile.

What Influences Your Credit

Several components determine credit scores, including payment history, amounts owed, length of credit history, new credit inquiries, and credit mix. Payment punctuality and the percentage of available credit you use tend to have the greatest impact. Understanding these drivers helps you prioritize simple, everyday actions that move the needle. Knowing which elements matter most makes it easier to focus energy where it counts.

Keep in mind that changes appear gradually, so patience is necessary. Track one or two priorities rather than trying to fix everything at once.

Daily Habits That Support Credit Health

Make on-time payments a daily priority by automating bills or setting reminders to avoid late marks. Monitor your account balances regularly to prevent accidental overspending and reduce utilization proactively. Use notifications for due dates and low balances to catch issues before they become problems. Small behaviors like checking balances each morning create awareness and reduce surprises.

Consistency beats sporadic intensity when improving credit. These small, repeatable steps help maintain stability.

Smart Credit Use and Payment Strategies

Aim to keep credit utilization low across all revolving accounts by paying down balances or moving charges to cards with lower utilization. When possible, make multiple small payments through the month rather than one large payment to keep reported balances lower. Avoid opening several new accounts at once, which can temporarily lower your score through hard inquiries and shorten average account age. If you carry a balance, prioritize highest-interest accounts while maintaining minimum payments on others.

  • Pay more than the minimum when possible to reduce principal faster.
  • Request higher credit limits rather than closing accounts to improve utilization.
  • Space new credit applications and review prequalification options.

Adopt strategies that fit your cash flow to avoid stress. Small adjustments in payment timing can produce measurable improvements.

Monitoring and Fixing Errors

Regularly review your credit reports to catch errors or unauthorized activity promptly. Dispute inaccuracies with the reporting agency and follow up with your creditors for documentation and correction. Monitoring also helps you spot identity theft early and take action before it damages your score. Free reports and alerts make this an easy habit to incorporate.

Set a schedule to review reports quarterly or when you notice unusual activity. Timely disputes often resolve quickly and restore accuracy.

Conclusion

Stable credit comes from steady, deliberate habits rather than quick fixes. Focus on on-time payments, low utilization, and regular monitoring to protect your score. Start with one small change today and build from there.

Routine Credit Checks and Actions for Long Term Stability

Routine attention to your credit profile is one of the simplest ways to strengthen financial options over time. A monthly check-in creates habit and makes small corrective actions easier to take. Small, consistent steps reduce the chance of surprises and help maintain favorable account behavior. This article outlines a practical monthly routine and clear actions to support long-term credit stability.

Why monthly checks matter

Errors, identity issues, and unexpected balance increases can appear quickly and affect score components. Checking reports monthly lets you spot anomalies while they are still easy to resolve. It also reveals trends in utilization, payment timing, and new inquiries that signal future movement. Taken together, those observations guide timely decisions and prevent small issues from becoming larger problems.

Making checks a regular habit reduces stress and the need for expensive remedies. Early detection preserves options and keeps your profile working for you.

Practical monthly actions

Start with a soft check of your credit report and score to establish a baseline each month. Review account balances and payment due dates, and set alerts where possible to avoid late marks. Dispute inaccuracies promptly using the reporting agency processes and document your steps for follow up. If utilization creeps up, plan targeted payments or transfer strategies that prioritize lowering revolving ratios quickly.

  • Set a calendar reminder for report review and bill payments.
  • Keep credit card balances under 30% of limits where feasible.
  • Limit new applications to essential needs and space them out.

These actions are simple to adopt and compound with time. Small, consistent behaviors produce the most reliable improvement in profile health.

Tracking progress and adjustments

Track changes month to month and create a simple spreadsheet or use a secure tool to log key figures. Monitor trends in utilization, age of accounts, and the frequency of hard inquiries to understand trajectory. Adjust your approach if payments slip, balances rise, or if new credit inflates risk; revisit goals quarterly. When necessary, seek basic guidance from credible educational resources rather than making reactive, high-cost choices.

Consistent tracking lets you celebrate small wins and correct course quickly. Over time, these adjustments combine to strengthen your overall credit standing.

Healthy credit habits

Prioritize on-time payments as the foundation of a healthy credit profile; consistency matters more than occasional large reductions. Keep older, well-managed accounts open when they serve your goals to preserve account age benefits. Use credit sparingly and deliberately, treating cards as tools rather than surplus spending capacity. Regularly reassess limits and automatic payments to make sure they align with your cash flow and objectives.

These habits keep pressure off your score and simplify monthly monitoring. Over time, they become the backbone of reliable credit health.

Conclusion

A modest monthly routine protects you from surprises and supports long-term goals. Small actions repeated reliably are the most effective route to steady improvement. Start with one trusted check each month and build from there.

A Stepwise Plan to Rebuild and Improve Your Credit Score

Credit scores feel abstract, but a clear plan can move them steadily in the right direction. This article outlines practical, realistic steps you can take whether you are starting from a poor score or recovering after a financial setback. With consistent actions and small changes in behavior, the impact compounds over months and years. The goal here is to create reliable habits that support long-term credit health without drastic sacrifices.

Assess Your Credit Baseline

Start by obtaining your credit reports and a current score to understand where you stand and what items are affecting your results. Look for errors, late payments, collections, and high balances relative to limits; each has a different weight in scoring models. Organize findings into categories: disputes, payments to catch up, account closures to avoid, and balances to reduce. Prioritize items that offer the most immediate score improvement and can be resolved quickly.

  • Dispute inaccuracies and request corrections where appropriate.
  • List accounts with highest utilization and prioritize payments.
  • Note any aged derogatory items that may still be negotiated.

Address disputes promptly and document communications with creditors to speed resolutions. Even small corrections can produce meaningful movement in weeks.

Take Focused Short-Term Actions

Lowering your credit utilization is one of the fastest ways to see a score increase, so focus payments on high-ratio accounts first. If you have missed payments, catch up as soon as possible and consider asking for a goodwill adjustment after a period of on-time payments. Avoid opening multiple new accounts at once, since hard inquiries and new credit lines can temporarily lower your score. Small actions like becoming an authorized user on a seasoned account or requesting higher limits can also help.

  • Pay down balances on cards near their limits.
  • Set up autopay for minimums and schedule extra payments weekly.
  • Negotiate with lenders for payment plans before accounts go to collections.

Track the effect of each action over a few billing cycles so you can adjust priorities. Short-term gains compound when paired with the sustainable habits that follow.

Build Sustainable Habits

Long-term credit improvement depends on reliable behaviors you can maintain, not one-off fixes. Keep older accounts open when possible, because account age and payment history length contribute positively to scores. Use a budget to prevent balances from creeping up, and set a target utilization rate well below available limits. Monitor reports regularly to catch issues early and to celebrate progress as scores improve, which reinforces the habit loop.

Automate payments and review statements monthly to stay in control without constant effort. Over time these practices increase stability and lower the risk of setbacks from unexpected expenses.

Conclusion

Improving your credit score is a process of small, intentional choices executed consistently over time. Begin with an honest assessment, prioritize actions that move the needle quickly, and commit to sustainable habits. With patience and discipline you can rebuild credit resilience and open more financial opportunities.