Quiet Ways to Improve Your Credit Without Stress

Improving your credit doesn’t require dramatic moves or risky shortcuts.
Small consistent choices — a few smart payments, a little attention to balances, and a simple plan — can change how lenders view you.
This article lays out clear, manageable steps you can take on a regular basis to nudge your score upward.
No jargon, no pressure; just practical actions you can start this week.

Understand the Pieces That Move Your Score

Your credit score is a composite of several factors: payment history, the amount you owe relative to limits, the length of your accounts, new credit activity, and the mix of accounts you hold.
Payment history typically carries the most weight, so a single missed payment can have an outsized effect.
Credit utilization — how much of your available credit you use — often responds quickly to changes and is something you can influence within a month or two.
Knowing which pieces matter most helps you prioritize actions that produce the biggest benefits.

Start by pulling a free credit report or checking a score dashboard so you know where you stand.
That snapshot tells you whether to focus on on-time payments, lowering balances, or correcting inaccuracies.

Practical Payment Habits That Add Up

Paying on time is the single simplest habit to form: set reminders, use autopay, or schedule payments right after payday.
If you struggle with large monthly minimums, make multiple smaller payments across the month to keep balances and utilization lower.
When possible, pay more than the minimum — reducing principal faster lowers interest costs and shortens the time you carry debt.
Regularly review due dates and consider aligning them with income cycles so missed payments become less likely.

Even modest extra payments can make a measurable difference over time.
Consistency beats perfection: steady on-time payments rebuild confidence in your credit profile.

Manage Credit Use and Accounts Wisely

Keep older accounts open when it makes sense; the age of accounts contributes positively to your score.
Avoid opening multiple new accounts in a short period — each application can cause a small, temporary dip.
If your utilization is high, ask for a credit limit increase or pay down balances focused on cards with the highest percentage used.
If you find errors on your report, dispute them promptly: correcting mistakes can restore points you didn’t even know you lost.

  • Target utilization below roughly 30% overall and lower on individual cards.
  • Request limit increases only when your financial behavior supports it.
  • Dispute inaccuracies with documentation for faster resolution.

Small account-management decisions compound over months.
Handle accounts thoughtfully and your score will reflect that steadiness.

Conclusion

Improving credit is more about steady habits than dramatic fixes.
Focus on timely payments, sensible use of available credit, and correcting errors.
Those quiet, consistent moves will yield clearer options and better terms over time.
One-Page Rules for Everyday Credit Card Use

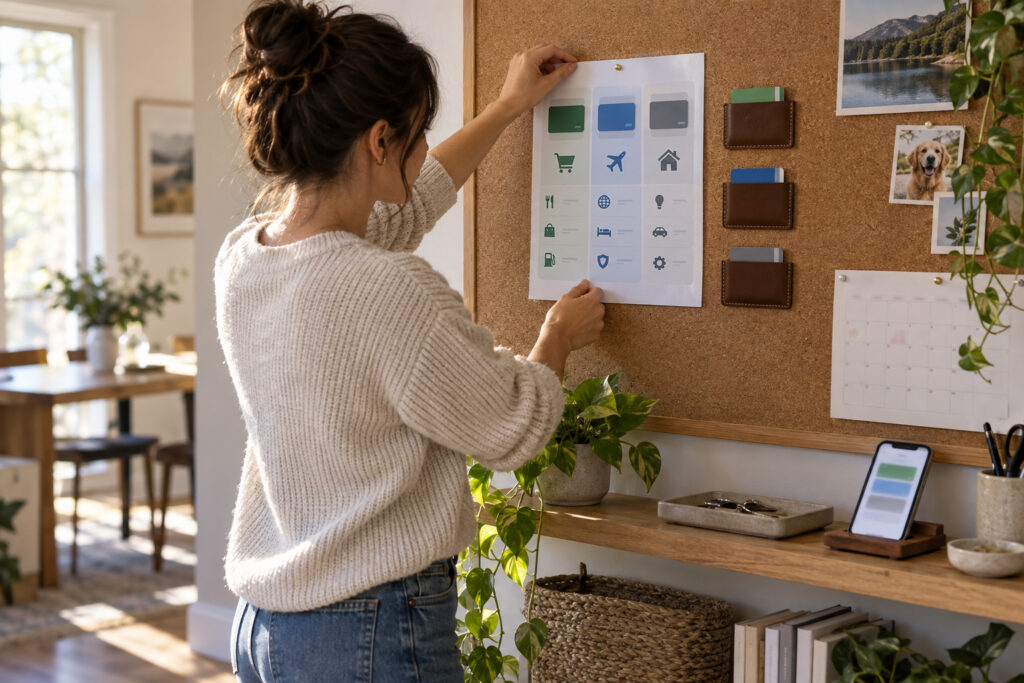
Credit cards don’t need to be complicated to be useful. A short set of clear rules can keep rewards, payments, and balances predictable without constant effort. This article lays out a compact approach you can follow month after month. Read it once, print it if you like, and use it as your quick reference.

Set a Practical Card Hierarchy

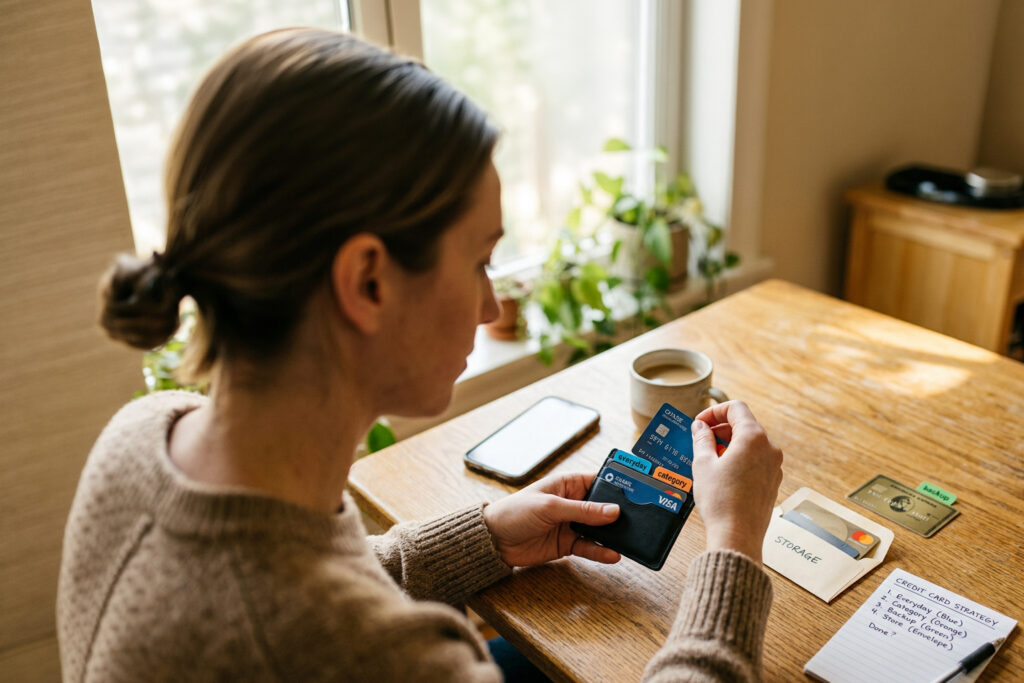
Start by assigning roles to each card so you don’t think about them every time you pay. Pick one card for everyday purchases, one for travel or big-ticket rewards, and one as backup or for specific categories like groceries or gas. Keep the number low enough that you remember which card does what, but high enough to capture meaningful benefits.

Write these roles down where you can see them — a note in your wallet app or a tiny card in your phone. When a new offer arrives, ask how it fits into these roles before applying. This keeps accounts purposeful rather than scattered.

Match Cards to Real Monthly Habits

Look at three months of statements and map spending categories to the cards in your hierarchy. Use the card that gives the best return for a given habit: put groceries on the grocery card, recurring subscriptions on the card with the best protection, and general spending on your primary card. Avoid switching for tiny gains; stability preserves rewards and tracking simplicity.

Set a calendar reminder once per quarter to reassess if your habits change. Small adjustments replace big, confusing overhauls and keep your system efficient. Consistency earns more than chasing every new bonus.

Use Billing Cycles to Your Advantage

Align large purchases with the billing cycle that gives you the longest interest-free float while still paying in full each month. Knowing statement close and due dates for each card reduces overdraft risk and keeps cash flow smoother. For recurring bills, set autopay for the minimum and add a manual payment reminder a few days before the due date to avoid mistakes.

Paying in full is the simplest path to avoid interest and preserve the value of rewards. If you carry a balance, prioritize reducing that amount before optimizing perks. Small timing changes can save real dollars over a year.

Monitor, Prune, and Protect

Review accounts every six months: cancel cards that cost more than they deliver, freeze ones you don’t use, and keep active the ones that match your goals. Check for unexpected fees and duplicate benefits, and consolidate where it reduces complexity without losing value. Protect your cards with alerts and secure passwords on linked accounts.

Regular, light maintenance beats occasional heavy scrambles. Treat cleanup as routine housework, not a crisis task, and your credit toolbox will stay lean and useful.

Conclusion

Pick a few clear roles, align cards with real habits, and time payments around billing cycles.
Keep changes small and review periodically to stay efficient.
A short rule set like this makes credit cards predictable and useful without stress.

Checklist for Building Confident Personal Insurance Coverage

Choosing the right insurance mix can feel overwhelming, but a structured checklist makes decisions clearer and faster. Start by listing what you own, who depends on you, and what risks could interrupt everyday life. Prioritize protections that would cause the most financial strain if something happened. This introduction frames a practical approach to review, compare, and maintain the coverages that matter most.

Assess Your Risks

Begin by inventorying your assets, income sources, and potential liabilities to understand where protection is necessary. Consider scenarios like property damage, disability, liability claims, and loss of income to gauge potential financial impact. Assessing both the likelihood and the severity of events helps you prioritize coverages and limits. Use this risk profile as the baseline for selecting policy types and limits.

After identifying exposures, match each to available policy types such as property, auto, life, and umbrella liability. This mapping highlights gaps and overlaps so you avoid unnecessary duplication. Keep the checklist updated as assets and responsibilities change.

Understand Policy Basics

Knowing the common elements of policies—coverage limits, deductibles, exclusions, and endorsements—prevents surprises at claim time. Limits determine maximum payouts, while deductibles affect your out-of-pocket cost and premiums. Exclusions identify what won’t be covered, so read policy language or ask an agent for plain-language explanations. Endorsements or riders can customize standard policies to fit unique needs.

Ask targeted questions about depreciation, replacement cost versus actual cash value, and coverage triggers. Clear answers let you compare policies on equal terms and avoid coverage gaps.

Compare Cost and Value

Premium is not the only metric; evaluate total value by weighing coverage breadth, customer service, and claims experience. A lower premium may mean higher deductibles or narrower limits that increase potential financial exposure. Look for discounts tied to bundling, safety features, or loss prevention measures to reduce cost without sacrificing protection. Use consistent scenarios when comparing quotes to ensure meaningful comparisons.

Document quote details in your checklist—include insurers, policy numbers, effective dates, and renewal terms. This makes it easier to decide and revisit choices later.

Review and Adjust Regularly

Life changes such as marriage, home improvements, new vehicles, or career shifts should prompt an insurance review. Annual checkups or post-event reviews ensure coverages and beneficiaries remain aligned with your situation. Track claims history and policy renewals to identify trends that could affect costs or coverage needs. Regular maintenance reduces the chance of being underinsured when it matters most.

Set calendar reminders for policy reviews and keep a concise record of decisions and documents in one place. Proactive adjustments keep your coverage both current and cost-effective.

Conclusion

Using a simple checklist turns insurance from a confusing purchase into a manageable plan. Focus on risk assessment, policy understanding, comparative value, and regular reviews to stay protected. Small, regular steps create long-term confidence in your coverage choices.

Smart Steps For Gradual, Sustainable Credit Improvement

Improving a credit score rarely happens overnight.
Small, consistent actions compound into meaningful change.
This article outlines practical steps you can use each month to make steady progress.
The focus is on sustainable habits that protect your financial reputation while avoiding risky shortcuts.

Why your credit score changes matter

Your credit score affects more than loan rates; it influences rental approvals, insurance premiums, and sometimes job screening processes. Small point gains can translate into significant savings over time, so incremental improvement is worth pursuing. Understanding the components of your score—payment history, utilization, length of history, new credit, and account mix—helps you target the most effective actions. Prioritizing the areas with the biggest impact will accelerate progress without unnecessary complexity.

Start by reviewing your credit report for errors and unfamiliar accounts, as inaccuracies can drag your score down. Regular monitoring helps you catch identity issues and verify that improvements are reflected in your profile.

Concrete actions to raise your score

Focus on three to five repeatable behaviors that fit your budget and schedule so improvement becomes automatic. Pay on time every month and set reminders or autopay for at least the minimum due to avoid late payments that harm your score. Lower your credit utilization by paying down balances and keeping card usage well below available limits. Avoid opening multiple new accounts in a short span, which can temporarily reduce your average account age and trigger inquiries.

  • Pay bills by or before the due date to protect payment history.
  • Target utilization under 30 percent, and ideally under 10 percent for faster gains.
  • Keep older accounts open to maintain length of history when it makes sense.

Combine these actions into a simple monthly routine: check balances, schedule payments, and review one line item on your credit report. Over time this disciplined approach builds a stronger, more resilient score.

Staying on track and avoiding setbacks

Set realistic milestones and celebrate small wins to maintain motivation during a multi-month process. If you face a financial setback, communicate with lenders—many offer hardship plans that prevent late payments from being reported. Re-evaluate your budget periodically to ensure you can sustain the behaviors that drive improvement. Use alerts and automatic transfers to reduce the chance of human error undermining progress.

Persistence matters more than perfection; a short misstep can be corrected with consistent follow-up. Keep learning and adjust strategies as your credit situation evolves.

Conclusion

Gradual credit improvement relies on repeatable, manageable habits.
Focus on timely payments, sensible utilization, and regular monitoring.
With a consistent approach, your score will reflect steady, lasting gains.

Prioritizing Card Features That Match Your Spending Habits

Choosing the right credit card can simplify daily finances and help you reach short-term goals. Rather than chasing the flashiest rewards, aligning card benefits with actual spending makes rewards meaningful. This article outlines practical steps to evaluate card features, reduce costs, and build consistent habits. Use these tips to pick cards that fit routines, not temptations.

When you base selection on real spending patterns you increase the chance rewards offset costs. The aim is steady, sustainable value instead of occasional windfalls. Read on for concrete ways to assess and compare card options. These guidelines work whether you carry one card or a small set of complementary cards.

Evaluate Your Monthly Spending First

Start by tracking typical monthly expenses across categories such as groceries, transport, dining, and utilities. Look at three months of statements to smooth irregularities and spot true habits. This snapshot reveals where a card’s bonus categories or statement credits would be most useful. Solid data prevents choosing cards that reward rare purchases instead of everyday ones.

With a clear spending profile you can shortlist cards that benefit your top categories. Avoid cards with high fees unless the value clearly exceeds those costs. The goal is a simple match between where you spend and what you earn back.

Match Rewards to Regular Purchases

Opt for cards that offer elevated rewards in places you already spend, not where you might spend more because of a perk. If groceries and gas make up most of your spending, a card with those bonus categories will outperform a travel-focused card. Consider rotating-category cards only if you reliably use the bonus categories each quarter. Also evaluate non-reward features like purchase protections and extended warranties that support frequent purchases.

  • Choose steady bonus rates for groceries or gas if those are major expenses.
  • Prefer flat-rate cash back for mixed spending patterns to avoid complexity.
  • Use travel or dining cards only if you already spend in those categories regularly.

Prioritizing consistency reduces effort and increases realized value over time. Simpler reward structures are easier to manage and less likely to be wasted.

Watch Fees and Interest, Not Just Rates

Annual fees can be worthwhile if their benefits exceed their cost, but many consumers benefit most from no-fee cards. Pay attention to APR and avoid carrying balances that negate rewards through interest charges. Also factor in foreign transaction fees, late fees, and balance transfer terms when comparing options. Small costs add up and can turn a lucrative rewards program into a poor choice.

Regularly reassess whether a paid card still justifies its fee based on how your spending changes. Make fee decisions based on net value rather than headline benefits.

Create Clear Usage Rules

Set simple rules that protect credit health and maximize rewards, such as keeping one card for everyday purchases and another for specific categories. Automate payments and track statement due dates to avoid late fees and interest. Limit applications for new cards to avoid unnecessary hard inquiries and monitor utilization to maintain a healthy credit profile.

  • Use one primary card for recurring bills and everyday buys.
  • Reserve specialty cards for the categories where they earn most.
  • Review card performance annually and close or replace cards thoughtfully.

Rules reduce decision fatigue and make rewards reliable rather than sporadic. Consistent habits ensure that chosen features continue to serve your goals.

Conclusion

Choosing cards that match real spending helps you earn meaningful value without extra expense. Focus on categories, fees, and simple usage rules to keep benefits practical and sustainable. Regularly review your setup to ensure it continues to align with changing habits.

Organizing Personal Insurance: Steps to Focus on What Matters

Organizing your insurance can reduce stress and ensure your protection matches real priorities.
Before making changes, pause to map living costs, assets, and likely risks.
A clear, repeatable approach helps compare policies and avoid unnecessary overlaps.
This article outlines practical steps to focus coverage where it matters most.

Identify Core Risks

Start by listing the risks that would cause financial strain if they happened, and be specific about potential dollar impacts and timelines.

  • Property loss and repair costs
  • Liability claims and legal expenses
  • Health or disability-related income interruptions
  • Auto, travel, and transportation exposures

Consider both likelihood and potential cost when you rank those risks, and include intermittent hazards such as seasonal exposures or travel-related incidents. A prioritized list guides which policies deserve more attention and budget, and it helps prevent paying for overlapping protections that add little incremental value.

Align Coverage with Priorities

Match coverages to the top risks on your list by reviewing what each policy actually covers and what it excludes.

For each priority, review policy limits, exclusions, and endorsements to ensure gaps aren’t hiding in fine print. Think about whether higher deductibles, umbrella policies or riders better address those risks, and weigh trade-offs between premium savings and potential out-of-pocket exposure. Document how each coverage responds to likely scenarios so you can spot gaps quickly and explain needs to an advisor or agent.

Aim for proportional protection: higher exposure equals broader limits and clearer claim pathways. Document decisions in a summary for easy reviews and future adjustments.

Review Cost and Policy Details

Cost matters but should be balanced with the quality of the protection and the insurer’s performance.

Compare premiums alongside out-of-pocket expenses, claims experience, and insurer reputation, and review how rates are likely to change on renewal. Look at deductibles, coverage caps, replacement versus actual cash value, and how premiums change after a claim. Check insurer financial strength and claims responsiveness as part of the value assessment to avoid surprises when you need to file.

  • Deductible levels
  • Policy limits and caps
  • Common exclusions
  • Endorsements and riders

When possible, get written comparisons and note renewal increases. Small policy differences can have large impacts at claim time, so document trade-offs clearly.

Work with Advisors and Schedule Regular Reviews

Bring this organized information to any advisor, broker, or agent so conversations focus on solutions rather than hunting for basics. A good advisor will help translate ranked risks into specific coverages and show how different options protect against high-priority scenarios. Schedule regular reviews—annually or after life changes—to reassess exposures and update limits, endorsements, or carriers as needed. Keep a concise summary of decisions and policy dates so renewals are easier to evaluate.

Involve trusted professionals when policies interact, such as bundling home and auto or adding umbrella protection. Regular reviews preserve alignment between changing priorities and your protection strategy.

Conclusion

A structured review keeps protection aligned with real needs.
Revisit priorities annually or after significant life events.
Clear choices will help you spend wisely and feel secure.

Quarterly Actions to Strengthen Your Credit Profile

Improving a credit score doesn’t require dramatic moves overnight.
Small, well-timed adjustments each quarter can add sustained improvements.
This approach focuses on measurable tasks and routine reviews.
The result is gradual but reliable progress toward stronger credit.

Assess Your Starting Point

Begin by pulling your credit reports and reviewing key metrics such as balances, recent inquiries, and open account ages. Look for anomalies, missed payments, or accounts you no longer use that may be dragging your profile down. Understanding where your score currently stands helps you prioritize actions that will have the biggest impact. Aim to document three to five areas to address over the next quarter.

  • Track current utilization per card and overall.
  • Note any late payments or collections.
  • Record account ages and recent openings.

Having a clear snapshot makes quarterly planning practical and focused. Use this as your baseline for measuring progress at the end of the period.

Set Quarterly Targets and Routines

Create specific, achievable targets for a 90-day window instead of vague resolutions. Examples include reducing overall utilization by a set percentage, disputing errors, or bringing a delinquent account current. Schedule recurring reminders to check balances and due dates so small habits become consistent. Regular, modest wins compound and protect your score against setbacks.

  • Target a utilization drop of 5–10% per quarter.
  • Plan one dispute or verification task each month.

These routines help maintain momentum without overwhelming your schedule. Quarterly reviews let you adjust targets based on real results.

Reduce Balances and Optimize Utilization

Lowering credit utilization is one of the most effective short-term levers to improve scores. Focus payments on higher-rate or high-balance cards first while preserving on-time payments across all accounts. Consider small balance transfers only when fees and terms clearly support savings over time. Avoid opening new accounts solely to increase available credit without a repayment plan.

  • Prioritize payments to reduce the highest utilization lines.
  • Keep at least a couple of accounts with low balances to show responsible use.

Consistency matters: make steady payments each billing cycle and avoid maxing out cards. Over several quarters, utilization improvements can produce measurable score gains.

Monitor Reports and Manage Errors

Set a habit of reviewing one report per month so you cover all bureaus each quarter. Dispute inaccuracies promptly and follow up until they are resolved to prevent lingering negative effects. Also monitor for unauthorized activity and freeze or lock accounts when appropriate. Regular monitoring reduces surprises and supports sustained improvement.

Document each dispute and the outcomes to build a clear history. This record helps if issues reappear or require further escalation.

Conclusion

Quarterly planning turns abstract goals into manageable actions.
Small, consistent improvements compound into meaningful score changes over time.
Stay disciplined, track progress, and adjust targets each quarter.

Building a Minimal Credit Card Setup for Clear Finances

Keeping a small, well-chosen set of credit cards can simplify finances and help you extract rewards without added complexity. Rather than chasing every promotion, a minimal setup focuses on coverage for regular spending categories and emergency backup. This approach reduces tracking, lowers the chance of missed payments, and supports healthier credit management. The following guide outlines practical steps to design and maintain a lean credit card setup that aligns with personal priorities.

Assess Your Spending Patterns

Start by reviewing recent statements to identify where most of your spending falls: groceries, fuel, dining, travel, or subscriptions. Understanding category concentration helps you decide which card benefits matter most and whether you need a specialty card. Also check recurring charges and seasonal variations to avoid gaps in coverage. A clear picture of spending informs both selection and how you rotate card use.

Document these patterns in a simple spreadsheet or budgeting app so decisions are evidence-based. This reduces impulse sign-ups and keeps the setup intentional.

Choose a Minimal Mix of Cards

A minimal setup typically includes one rewards card for everyday purchases, a second card for high-value categories, and a no-annual-fee backup for emergencies. Prioritize cards that offer broad benefits and avoid overlapping premium features you won’t use. Consider interest rates, grace periods, and introductory offers, but don’t let temporary promotions dictate long-term choices. Simplicity and usefulness should be the guiding criteria.

  • Everyday rewards card for groceries and bills.
  • Category-specific card for travel or dining bonuses.
  • No-fee backup for emergencies and balance flexibility.

Aim to keep the number of active cards low while preserving available credit for scores. Closing unnecessary accounts can hurt history, so prefer dormancy over closure if possible.

Set Simple Usage Rules

Create a short, personal rule set: which card for which category, a monthly payment checklist, and a limit on new applications per year. Automate payments to avoid late fees and set calendar reminders for rewards activations or annual fee reviews. Keep a visible note (digital or physical) listing the primary use for each card to reduce accidental switchover. Rules reduce cognitive load and make consistent payoff behavior more likely.

Treat the setup as a living system—small discipline yields big benefits. Regular habits keep the minimal setup working efficiently.

Monitor and Adjust Regularly

Review card performance quarterly to confirm that rewards and perks still match your spending. Watch for fee increases, changing category bonuses, or declining value in benefits. If a card no longer justifies its cost or complexity, consider product changes, downgrades, or strategic closure. Maintain a simple scorecard to compare total value against effort.

Adjustments should be deliberate and infrequent, not reactionary to every promotion. This preserves stability while allowing upgrades when clear value appears.

Conclusion

Keeping a minimal credit card setup helps you focus on value, reduce administrative friction, and protect credit health. By assessing spending, choosing complementary cards, enforcing simple rules, and reviewing periodically, you can sustain a streamlined system. Small, consistent choices deliver clearer finances and better long-term outcomes.

How to Tune Up Your Personal Insurance Coverage

Regularly tuning your personal insurance coverage helps close gaps, remove redundancies, and keep costs aligned with your priorities. A focused review reduces surprises when you need to file a claim and ensures limits mirror your current lifestyle and assets. This article outlines practical checkpoints you can use during an annual or life-event driven review cycle. Apply these steps to create a clearer, more efficient set of policies.

Assess Your Current Policies

Start by gathering every policy document: home, auto, umbrella, renters, and any specialty coverage you hold. Compare declarations pages to confirm named insureds, covered property, policy limits, and deductible amounts. Note exclusions, endorsements, and any recent claims history that might affect future premiums or coverage availability. Look for overlaps where two policies cover the same exposure and for gaps where no policy applies.

Organizing this information in a single spreadsheet or folder makes the rest of the review faster. Keep digital copies for easy reference during conversations with an advisor or carrier.

Prioritize Gaps and Overlaps

Once you know what you have, identify the most significant risks that remain uncovered or are underinsured. For example, high-value personal property, liability exposures, or flood risks often need separate coverage or endorsements. Conversely, overlapping protections may allow you to consolidate or remove redundant options. Prioritize fixes based on potential financial impact and likelihood of occurrence.

Address high-risk gaps first, then refine optional coverages to balance cost and protection.

Adjust Deductibles, Limits, and Endorsements

Evaluate whether current deductibles and limits reflect your budget and risk tolerance. Raising a deductible can lower premiums but increases out-of-pocket exposure; lowering a limit may expose you to recovery shortfalls. Consider endorsements that add targeted protections without a full policy upgrade, such as identity theft coverage or equipment breakdown add-ons. Revisit vehicle and property values to ensure replacement cost versus actual cash value choices remain appropriate.

Small changes can produce meaningful premium savings while maintaining the coverage you truly need.

Document Decisions and Schedule Reviews

Record any mid-year changes, communications with agents, and reasons for coverage adjustments. Establish a recurring reminder to review policies annually and after major life events like moving, marriage, or business changes. Clear documentation speeds renewals and supports claims by showing intent and coverage history. Maintain a concise summary page with key policy numbers and contact details for quick access.

Regular reviews reduce surprises and make insurance a proactive part of your financial plan.

Conclusion

Scheduling a regular tune-up empowers you to control cost and protection without overpaying. A structured approach — assess, prioritize, adjust, and document — keeps your portfolio aligned with changing needs. Treat this review as part of routine financial maintenance to preserve peace of mind.

Timing and Organization Habits That Boost Credit Scores

Small changes in how you schedule payments and organize accounts can have a meaningful impact on your credit score. Reviewing reports regularly and aligning due dates with pay cycles reduces the risk of late payments and high utilization. This article focuses on practical timing and organization habits that drive steady improvement. Implementing these habits consistently creates measurable momentum over months.

Check Your Reports and Prioritize Corrections

Start by obtaining your credit reports and reviewing them for inaccuracies, outdated items, or unfamiliar accounts. Look for errors in balances, payment histories, and personal details, and file disputes promptly when you find mistakes. Correcting inaccuracies can remove unjust negative items and sometimes boost your score quickly. Keep a log of disputes and responses so you can follow up without losing track.

Prioritizing corrections also helps you target the most impactful problems first, such as late payments and high balances. Regular maintenance prevents small issues from becoming long-term blemishes on your file. Treat report review as a monthly habit to stay ahead.

Adjust Payment Timing and Reduce Balances

Payment timing affects both on-time status and reported utilization, so align due dates with your cash flow when possible. Paying before the statement closing date lowers the balance that is reported to creditors, which can improve utilization ratios. Even modest reductions in reported balances often translate into visible score changes. Automating payments or setting reminders reduces the chance of missed due dates.

  • Set payments a few days before the statement closing date to lower reported balances.
  • Make multiple smaller payments throughout the month to keep utilization low.

These adjustments are simple to implement and compound over time, making credit healthier without major lifestyle changes. They also reduce stress by keeping accounts in better standing.

Manage New Accounts, Credit Mix, and Monitoring

Opening new accounts can help diversify your mix but may temporarily lower your score due to inquiries, so plan additions strategically. Focus on maintaining older accounts in good standing and avoid unnecessary applications. Use credit monitoring tools to track changes and receive alerts for unusual activity or balance spikes. Monitoring gives you time to respond before issues escalate.

Balance new account benefits with the short-term impact of inquiries, and opt for secured or low-limit additions if you need to build history. A thoughtful approach to account management supports steady score growth.

Conclusion

Organize payments, review reports, and monitor activity regularly to influence your score in measurable ways.
Make small timing adjustments and automate where possible to reduce errors and reported balances.
Consistent habits create steady improvements that compound into long-term credit health.