Practical Choices for Smarter Supplemental Health Coverage

Choosing supplemental health coverage can feel like sorting through a maze of options, premiums, and fine print. Start by clarifying what your base plan already pays for and where it leaves you exposed. Think about the services you use regularly and the expenses that would hurt your budget if they weren’t covered. A clear list of those risks makes the rest of the process far more purposeful.

Begin with realistic expectations about what insurance will do and what it will not. Keep the focus on practical protection rather than trying to eliminate every possible cost.

Start with a clear inventory

Begin by listing the benefits your primary insurance covers and marking the gaps: deductibles, co-payments, long hospital stays, or outpatient services. Include likely near-term needs such as prescription medication, routine dental work, or planned procedures. Knowing the dollar amounts attached to those gaps helps you compare plans like-for-like. This step prevents buying redundant coverage that adds cost without meaningful extra protection.

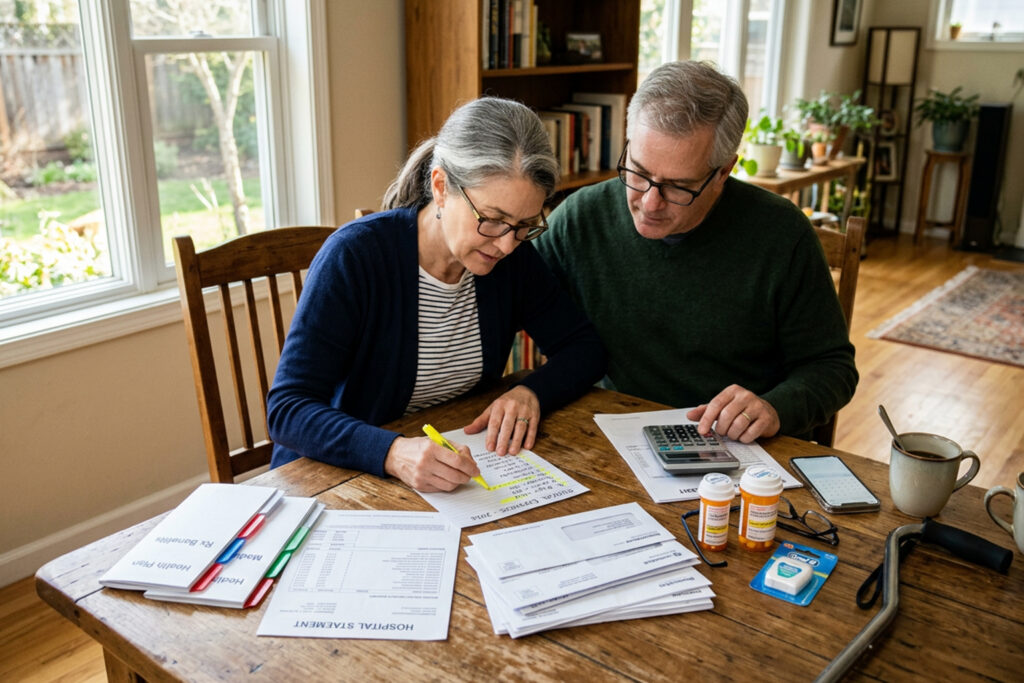
Documenting recent medical bills and expected expenses makes choices concrete rather than abstract. Keep those notes handy when reviewing quotes or talking to an agent.

Match coverage to likely needs

Not every extra benefit is worth the same to every person; align options with your personal health picture. For example, if prescriptions are your main expense, a plan that offers lower drug co-pays may be more valuable than broader hospitalization benefits. If mobility or dental work looms ahead, prioritize those riders instead. Aim to cover the highest-probability, highest-cost items first.

  • Prescription cost-sharing for chronic meds
  • Hospital indemnity for occasional long stays
  • Dental and vision for planned maintenance

Focus on a small set of priorities to keep premiums reasonable and benefits targeted. That balance is the heart of smart supplemental planning.

Weigh cost against real benefits

Compare annual premiums against the out-of-pocket exposure each plan reduces. A lower premium can be tempting but might leave you facing large bills for a single event. Look at maximum out-of-pocket limits and what triggers full benefits, not just the headline premium. Also consider how a plan coordinates with other insurance rather than overlaps unnecessarily.

Run simple scenarios: what happens if you need a week-long hospital stay or several months of specialty medication. Those quick calculations reveal which plans truly protect your finances.

Watch for exclusions and timing

Read exclusions carefully and note waiting periods, pre-existing condition clauses, and enrollment windows. Some benefits only start after a waiting period or exclude certain services forever, which can make a policy less useful when you need it. Timing matters: missing an enrollment window can mean limited options or higher costs later. Ask clear questions and get answers in writing when a policy detail is important to you.

Keep renewal dates and annual review reminders on your calendar so coverage still fits your needs next year. A small review each season can save surprises down the road.

Conclusion

Practical supplemental coverage begins with a clear list of gaps and likely expenses. Match benefits to those needs, compare real costs against potential savings, and check exclusions and timing carefully. With focused choices and an annual review, you can secure useful protection without paying for what you don’t need.
Pay Smarter, Not Harder: Building Better Credit Habits

Small, consistent choices about when and how you use credit shape the scores lenders see. This article focuses on practical moves you can adopt without overhauling your entire budget. Pick a couple of tactics and stick with them for a few months to see steady improvements. The goal is momentum: gradual progress that becomes routine.

Prioritize Payment Timing

Paying on time is the single most influential habit for most credit scores, and timing matters more than many people realize. Set payments a few days before the due date and align them with your pay schedule so you never miss a cycle. If you struggle with one account, move its due date or set an automated partial payment immediately after payday. Consistent punctual payments build a reliable history that lenders favor.

Automate where it helps and review statements monthly to catch stray charges. Even small late fees or a missed payment can slow progress, so make timing a simple protective routine.

Lower Utilization, Raise Scores

Credit utilization—the percent of available revolving credit you use—is a fast-moving factor you can influence. Try to keep utilization under roughly 30% on each card and overall, and aim lower if you want quicker gains. If a statement balance is high one month, make an extra payment before the statement closing date to reduce the reported balance. Increasing your credit limit can also help, but only if it doesn’t encourage more spending.

Watch each account’s reported balance rather than just your current balance. Small, repeated reductions will help the score reflect safer borrowing behavior.

Keep Accounts Active Strategically

The age and diversity of accounts contribute to credit profiles, so closing old cards can sometimes do more harm than good. Use older accounts occasionally for small purchases you pay off quickly to keep them active. For new accounts, resist opening several at once because multiple inquiries and a shortened average age can weigh on your score. Think of each account as a long-term piece of your credit history.

Maintain a balance between keeping older accounts open and avoiding unnecessary new ones. Strategic activity protects your credit age and mix over time.

Monitor and Correct Your Report

Regularly checking your credit report reveals mistakes and unexpected activity that could drag your score down. Dispute clear errors promptly and follow up until they’re corrected; even one erroneous late payment can have a large effect. Monitoring alerts also helps you spot identity issues early, letting you act before larger problems develop.

Use free annual reports and low-cost monitoring tools as suits your comfort level. Knowing what’s on your report gives you control to make informed, corrective decisions.

Conclusion

Small, repeatable payment and usage habits reliably change credit trends over months rather than overnight. Focus on timing, utilization, account management, and regular checking to build credit with confidence. Consistency matters more than perfection, and steady choices add up.

A Few Habits That Keep Credit Cards Simple

Credit cards don’t have to be a source of stress. With a handful of steady habits you can keep rewards, payment timing, and fees under control. This article focuses on small routines that prevent surprises and preserve your cashflow. Adopt one change at a time and you’ll see how little adjustments add up.

Start with clear purposes for each card, then move to practical payment habits that fit your calendar. Small, repeatable actions are easier to maintain than grand financial overhauls. The goal is predictability, not perfection.

Choose Two Primary Cards

Most people only need two main cards: one for everyday spending and one for larger purchases or rotating rewards. Keeping to two limits decision fatigue and makes monitoring balances simpler. Pick cards with complementary benefits so you’re not duplicating categories or annual fees. Avoid chasing every bonus; consistency wins.

Having a backup card for emergencies is fine, but keep it inactive for routine charges. That reduces fraud exposure and keeps your credit utilization clear.

Match Cards to Regular Spending

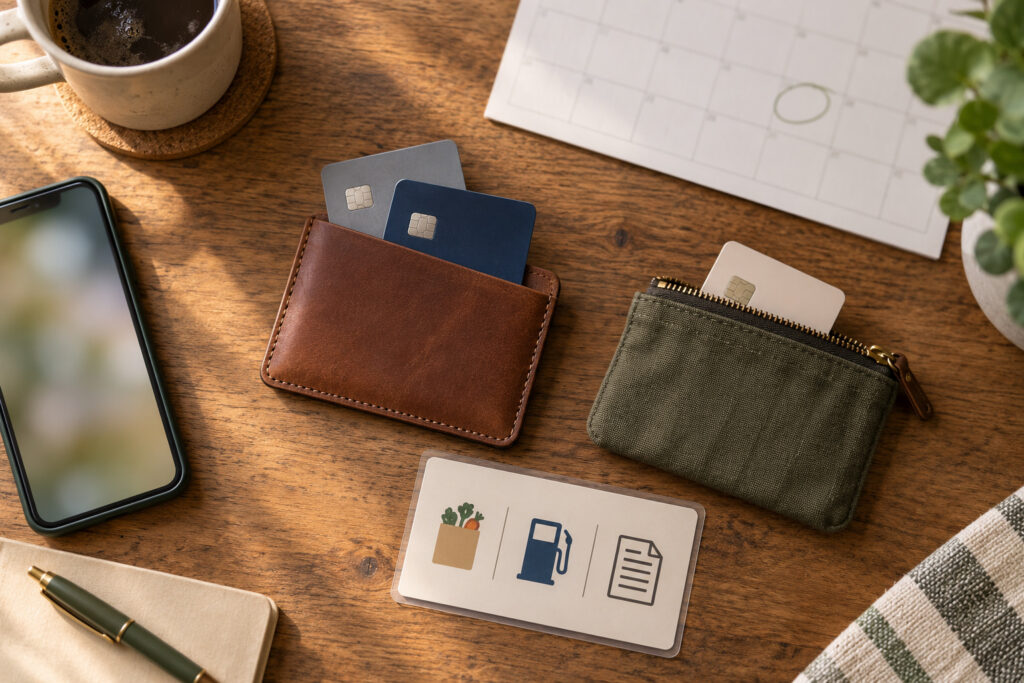
Identify three regular categories where you spend most: groceries, gas and utilities, for example. Assign each category to the card that offers the best return and habitually use that card for those purchases. If a card has rotating categories, note activation and start dates so you don’t miss higher rewards. A simple labeled wallet or app note can prevent slip-ups.

When rewards change, review and reassign categories quarterly. This keeps your setup aligned with real spending without constant overthinking.

Pay on a Rhythm That Fits Your Cashflow

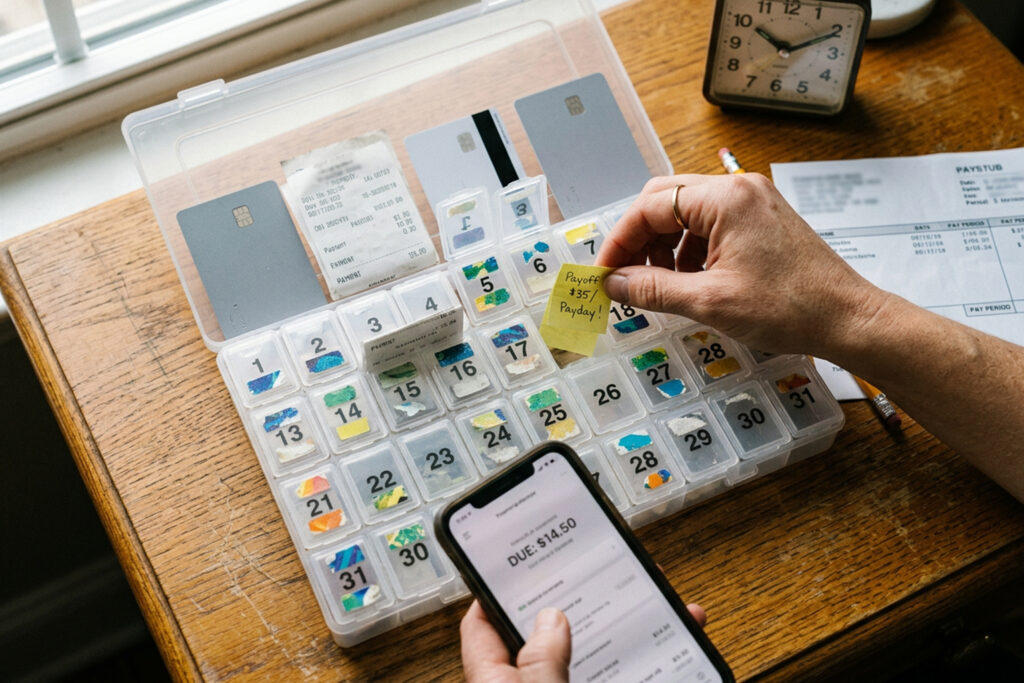
Pick a payment rhythm tied to paydays: one principal payment right after you get paid, and a final statement payoff before the due date. That approach reduces interest risk and keeps balances predictable. If you can, set autopay for the minimum and manually clear the rest on payday to avoid overdrafts. Treat the card like a short-term loan, not free money.

Regular reviews of statements catch errors and subscription creep. A quick monthly check takes minutes and saves headaches later.

Protect Simple Rules With Automation

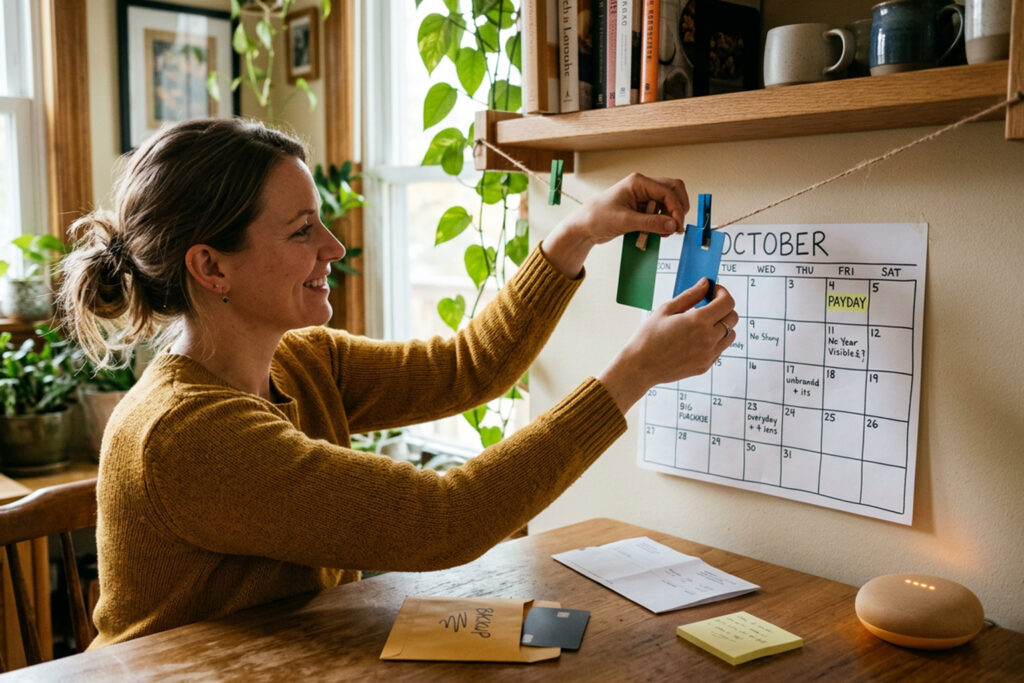
Use calendar alerts and bank rules to enforce your habits without relying on memory. Set alerts for statement closing dates, card activations, and reward category switches. If you carry a balance strategically for a large purchase, automate a plan to eliminate it within a set number of months. Automation reduces friction and keeps your plan honest.

Combine automation with one monthly habit: a five-minute review of charges and benefits. That small ritual preserves control and keeps complexity from creeping back in.

Conclusion

Keep your credit card routine small and consistent. Choose clear roles for each card, pay on a rhythm tied to your cashflow, and use automation to enforce rules. These tiny changes make credit cards predictable and useful without drama.

When to Update Supplemental Insurance and What to Change

As health needs, routines, and finances shift in retirement, supplemental insurance that once fit your life can drift out of step. Small changes — a new medication, a recent hospital stay, or a tighter monthly budget — often reveal unexpected gaps or unnecessary costs. Rather than react under pressure, a brief, regular review makes it easier to spot mismatches and act deliberately. This piece explains common triggers for a review, the first things to compare, and practical steps to adjust coverage without confusion.

Periodic checks don’t mean constant upheaval; they mean smarter choices. A short checklist and a set schedule make updates manageable and less stressful.

When to Revisit Your Plan

Not every change requires an immediate switch, but several clear signals do. Significant health events, new prescriptions, a change in income, or moving to a different area all warrant a fresh look at coverage. Enrollment windows and plan cancellation rules also create deadlines you’ll want to respect. Pay attention to notices from insurers that outline benefit changes or rate hikes.

Mark these triggers on your calendar and treat them as prompts to gather recent medical bills and policy documents. Acting early often opens more options and avoids penalties.

What to Compare First

Start with the elements that affect your wallet and everyday access to care. Compare premiums, annual deductibles, copays, and prescription drug tiers to see where costs have climbed. Check whether your regular providers and preferred pharmacies remain in-network and review coverage limits for services you use frequently. Look for exclusions or waiting periods that might matter if you anticipate specific treatments.

  • Premiums vs. expected usage
  • Deductible and out-of-pocket maximums
  • Provider networks and prescription tiers

Focus comparisons on the few items that would change your annual budget the most. That narrows choices and speeds decision-making.

Costs, Discounts, and Coordination

Beyond headline prices, see how plans work with other coverage you have. Some supplemental policies coordinate benefits with a primary plan; others pay first and leave gaps. Ask about available discounts for multi-policy holders, prompt renewals, or automatic payments. Also verify how switching plans impacts short-term coverage, especially for chronic conditions.

Understanding coordination helps avoid paying twice or losing a benefit when you change carriers. Small savings tactics add up over a year.

Practical Steps to Make Changes

Gather the last year of medical bills, medication lists, and current policy summaries before you call insurers or brokers. Request written quotes showing total yearly costs, not just monthly premiums, and read exclusions closely. If you find better coverage, confirm effective dates, any waiting periods, and cancellation procedures for your current plan. Keep records of conversations and written offers to prevent surprises later.

Move deliberately: compare, confirm, and only then commit. A steady process reduces regret and keeps coverage aligned with real needs.

Conclusion

Regular, targeted reviews let you keep coverage that matches current health and budget realities. Start with clear triggers and compare the few items that affect your annual costs most. Small, informed changes usually deliver better protection and less financial strain.

Small Predictable Steps to Reduce Credit Risk and Improve Scores

Improving your credit score doesn’t require a big reset or complicated tricks. Small, repeatable actions often move the needle more reliably than dramatic one-off efforts. This piece breaks down practical steps you can add to your routine that lower risk and help scores recover. Read on for clear tactics that fit into an ordinary month.

Prioritize on-time payments

Payment history is the backbone of most scoring models, so a single habit change—paying on time—has outsized benefits. Automate at least the minimum payment on each account and set calendar reminders a few days before due dates to avoid accidental late posts. If a payment will be late, contact your lender; some will agree to a one-time grace or waive a fee and not report a late payment. Repeated punctuality builds a clean record that signals low credit risk.

Consistency beats perfection here: missing one payment is forgivable, but habits shape how accounts are viewed. Make punctuality part of a broader money routine and keep momentum by reviewing upcoming bills weekly.

Trim your credit utilization

High balances relative to limits can weigh down a score even when payments are timely. Aim to keep revolving utilization under roughly 30%, and lower if you can—single-digit utilization helps more. If balances spike occasionally, ask for a credit limit increase or move purchases to a card with more available space. Small transfers or shifting recurring charges between cards can also balance utilization without new credit.

  • Set a reminder to check card balances mid-cycle.
  • Make a small extra payment before the statement closes.

These minor scheduling tweaks keep reported balances lower and show lenders you manage available credit responsibly.

Keep accounts open and check your reports

Length of credit history and account mix matter, so closing oldest cards can unintentionally hurt scores. Keep accounts you use occasionally active by running a small automated charge and paying it off. Regularly review your credit reports to spot errors like incorrect balances or unfamiliar accounts that could damage your profile.

Disputing mistakes promptly often leads to quick fixes, and maintaining a long, active record supports long-term score improvement. Small, routine checks prevent surprises when you need credit.

Use small wins to rebuild trust

If your score has setbacks, start with achievable actions: on-time payments, reduced utilization, and correcting report errors. Consider a secured card or a credit-builder loan if access is limited—these products can create positive entries when managed responsibly. The goal is steady, verifiable improvements rather than rapid fixes that might carry risk.

Track progress monthly and celebrate milestones like a single clean year of payments. Over time, those small wins add up into meaningful credit repair.

Conclusion

Small, predictable steps compound into measurable credit improvement over months. Commit to on-time payments, lower utilization, and routine report checks. These modest habits reduce risk and help scores rise steadily.

Three Steps to a Calm Credit Card Routine

Credit cards are useful tools but they can clutter your month if you treat them like random options.
A short, repeatable routine keeps rewards flowing and bills from surprising you.
You don’t need dozens of rules—just a clear primary plan and two supporting habits.
This article lays out three simple steps you can use every month to stay organized.

Pick One Primary Card and a Backup

Choose a single card for most everyday purchases so you build predictable reward totals and simplify tracking. Let the primary card cover groceries, gas, and recurring subscriptions where it has the best return. Designate a backup for categories where the primary is weak or for emergency use, and store both in your wallet. Keep reward categories aligned with large planned purchases like annual insurance or holiday shopping.

Keep the backup seldom used so you preserve credit history and avoid unnecessary balances. Rotate cards only when a clear seasonal benefit appears. Keep a small note in your phone listing each card’s main benefit.

Match Cards to Monthly Spending Categories

Review your last two months of statements to spot where you actually spend money, not where you think you do. Assign one card for fixed monthly bills, another for variable categories like dining or travel, and use the primary for everything else. Use calendar reminders to switch cards on specific bill days rather than trying to remember mid-shopping. Reassess the assignments if your spending shifts seasonally or after big life changes.

This small mapping reduces missed reward opportunities and reduces impulse switching. It also helps you evaluate whether a card’s annual fee is justified. If you find overlaps, simplify by consolidating cards to reduce friction.

Lock Down Payment Dates and Watch Fees

Put payment dates a few days after payday to make on-time payments easier and reduce late fees. Set up autopay for at least the minimum and schedule a second reminder to pay the full statement balance. Check annual fees and balance transfer offers quarterly so you avoid surprises and keep costs low. Watch foreign transaction fees and merchant surcharges when traveling or shopping online.

If a card no longer earns rewards that match your habits, replace or close it thoughtfully. Small, regular reviews prevent small leaks from becoming big expenses. A modest routine saves interest and preserves the conveniences cards provide.

Conclusion

A three-step monthly routine takes minutes and prevents headaches.
Focus on one primary card, match cards to real spending, and lock payment timing.
Do a quick quarterly review and adjust as your life changes.

How to Trim Costs Without Sacrificing Senior Coverage

Insurance for later life can be costly, but trimming unnecessary spending doesn’t have to mean losing important protections. A few focused choices—about deductibles, riders, and timing—often produce the biggest savings without leaving gaps. This piece outlines practical ways to reduce premiums while keeping the benefits you rely on for routine care and unexpected events. Read through the trade-offs so you can make clear decisions instead of impulse cuts.

Where costs hide

Start by locating where premiums are driven: high-cost riders, duplicate coverage, and steep copay or deductible structures are common culprits. Riders that promise extra services can be useful, but many are underused; list each rider, note its cost, and consider dropping ones you rarely use. Also check whether you are insured twice for the same benefit—for example, a secondary plan that pays what a primary already covers—and cancel redundancies. Small changes such as increasing your deductible or switching to a plan with a different coinsurance split can lower monthly bills substantially.

Document the savings each change would produce before acting. That way you balance monthly relief against long-term exposure.

Match coverage to real needs

Next, match coverage to likely needs rather than theoretical worst-case scenarios. If your typical expenses are routine prescriptions and doctor visits, emphasize plans with low outpatient costs rather than one with extensive hospital perks you may never use. Consider carving out niche protections—dental, vision, or home health—only if your history suggests they will be used enough to justify the premium. A benefits checklist based on recent claims can expose which categories matter and which are candidates for trimming.

Focus resources on high-probability needs and accept modest cost-sharing for rare events. This creates a safer financial cushion while keeping premiums sustainable.

Shop smart and schedule reviews

Shopping wisely matters: compare total annual cost, not just monthly premium, and read sample bills to imagine out-of-pocket exposure. Timing changes can lower penalties; open enrollment windows and small life changes often allow adjustments without medical underwriting. Use a spreadsheet to compare scenarios and ask insurers for written examples of claims handling and billing practices. Finally, schedule an annual review; needs evolve, and what was excessive last year might be essential now, or vice versa.

Periodic reviews prevent surprise bills and let you seize better rates as they appear. Treat insurance as something to manage, not forget.

Conclusion

Trimming senior insurance costs is an exercise in clarity: know what you have, what you actually use, and what you can afford to risk. Thoughtful adjustments and regular reviews can reduce premiums while keeping core protections intact. Make changes deliberately, keep documentation, and revisit your plan at least once a year.

Smart Payment Rhythms to Strengthen Your Credit Score

Credit scores move slowly, but deliberate payment habits make a measurable difference. Small shifts in when and how you pay can cut utilization, prevent late marks, and show steady responsibility. You don’t need a dramatic overhaul—consistency and clarity in payment timing often do the heavy lifting. This piece lays out clear, practical timing strategies you can adopt without stress.

Start with predictable actions and watch modest gains stack up over months rather than overnight. The rest of the article breaks the approach into focused steps you can try immediately.

Set payment dates that suit your cash flow

Aligning card due dates with payday removes friction and reduces missed payments. Call your card issuer or use the online settings to shift due dates to a few days after you get paid. That small calendar change lowers the odds of carrying unexpected balances and helps keep each account current. It also makes it easier to automate payments without worrying about overdrafts.

Once dates match your schedule, automate at least the minimum payment. Automation preserves the rhythm and protects your score from accidental slips.

Lower utilization by splitting payments

High utilization can dent your score even when you pay in full each month. Paying in two smaller chunks—mid-cycle and before the statement closing date—keeps reported balances low. This tactic reduces the percentage of available credit you’re using when issuers report to bureaus. It’s especially useful on cards with large limits or seasonal spending spikes.

  • Make a mid-cycle payment to cut the balance before it’s reported.
  • Clear remaining charges before the statement closes to show a low balance.

These moves take a few extra minutes monthly but can improve the utilization slice of your score fairly quickly. Consider calendar alerts to keep the rhythm consistent.

Use automation smartly and review regularly

Automatic payments reduce human error but aren’t a set-and-forget cure. Schedule automatic payments for fixed amounts and check statements monthly for surprise charges or billing errors. Review your autopay settings after any change in income or card activity so you don’t overdraw your bank. Regular checks keep automation working in your favor rather than creating new problems.

Combine automation with spot checks to catch anomalies early. That balance preserves convenience while guarding your credit health.

Conclusion

Consistent timing choices—matching due dates to paydays, splitting payments, and smart automation—build a positive credit narrative. These habits reduce late payments and lower reported balances, two factors that improve scoring behavior. Start with one change this month and add another next month to maintain momentum.

How to Use Fewer Cards Without Losing Benefits

Juggling a wallet full of plastic can feel like extra work for very little payoff.
Cutting down to a smaller set of cards doesn’t mean you have to give up rewards or protection.
This piece shows a practical way to pick a compact set that covers everyday needs and occasional perks.
Follow a few simple habits and you’ll spend less time managing accounts and more time enjoying the benefits.

Pick Two Primary Cards

Choose one card for everyday purchases and one for larger recurring expenses or travel.
The everyday card should offer consistent cash back or a flat-rate reward that applies to most purchases.
Use the second card for bills, subscriptions, and travel where benefits like warranties or insurance matter more.
Limiting to two primary cards forces discipline and makes it easier to monitor spending and due dates.

Keeping this small core reduces the chance of missed payments and lowers the cognitive load of optimization.
You can still keep a third backup for specialty needs if desired.

Map Cards to Spending Categories

List your biggest monthly categories—groceries, fuel, utilities, dining—and assign the card that rewards each category best.
If one card covers 80 percent of your purchases, make it your primary and lean on others only where they clearly win.
This mapping prevents switching cards at the checkout and ensures you collect predictable value over time.
Review the assignments quarterly since merchant categories and bonus offers change throughout the year.

  • Groceries — card A
  • Subscriptions and bills — card B
  • Gas and transit — card A or specialized card

Once mapped, set that assignment into your budget habits so reaching for the right card becomes automatic.
A simple cheat sheet in your phone or wallet helps at busy registers.

Keep Track of Billing Cycles

Align statement dates and due dates with your cash flow so payments fall after payday when possible.
If moving dates isn’t feasible, use autopay for at least the minimum to avoid late fees, and manually pay the remainder.
Small timing changes can free up short-term cash without carrying balances and interest.
Understanding the cycle also reveals when to make big purchases to maximize interest-free days.

Use calendar reminders or a finance app to watch for upcoming payments and statements.
That little bit of scheduling prevents surprises at the end of the month.

Manage Infrequent Cards and Benefits

Keep cards with annual benefits only if those perks outweigh fees and you will actually use them.
If a card sits unused, consider reassigning its benefit to a card you carry, downgrading the account, or closing it carefully.
Store credentials for occasional cards in a secure place and remove them from autopay if they aren’t active.
That approach preserves perks without bloating your monthly routine.

Regularly audit fees and benefits so you aren’t paying for unused services.
A brief yearly review keeps the small collection focused and valuable.

Conclusion

Fewer cards mean less hassle and clearer earning opportunities.
Keep two primary cards, map spending, and time your payments to suit cash flow.
A short annual audit will protect value and keep your setup tidy.

Rethink Senior Supplemental Coverage Before Open Enrollment

Open enrollment is the annual moment to stop and reassess supplemental insurance rather than letting the same plan roll forward by default. Small changes in benefits, premiums, or your health needs can leave you paying for options you no longer use or missing coverage you will need. Take time this season to gather plan documents, recent medical bills, and a list of providers you prefer. A focused review now can reduce unexpected costs and improve your care access next year.

Assess what your primary plan already covers

Start by listing services your core plan pays for and where limits or copays appear. Check hospitalization, outpatient procedures, prescription drug tiers, and any limits on therapy or durable medical equipment. Look for gaps such as dental, vision, hearing, or extra home health support that often fall outside a primary policy. Knowing those holes gives you a precise starting point for choosing supplemental benefits.

Gather recent statements and a short summary you can compare across options. That paperwork makes trade-offs between premium increases and out-of-pocket risk much clearer.

Match supplemental benefits to realistic needs

Prioritize benefits you are likely to use rather than every available rider or add-on. If you rarely use specialty care but expect higher prescription costs, a plan with drug coverage or lower drug copays may offer better value. Consider your family medical history and any scheduled procedures when weighing chronic care or skilled nursing benefits. Coverage that seems generous on paper can become costly if it duplicates services already provided.

Keep a simple checklist of must-haves and nice-to-haves to guide decisions during enrollment windows. That keeps choices practical and focused on likely expenses.

Check provider networks and paperwork requirements

A supplemental plan is only useful if it lets you see clinicians you trust at reasonable cost. Confirm preferred doctors and pharmacies are in-network, and read prior authorization rules that could delay care. Some plans require specific referrals or documentation for benefits to apply, and missing a step can mean denied claims. Time spent clarifying these administrative rules prevents surprises when care is needed.

If switching plans, contact a few of your main providers to confirm acceptance before finalizing enrollment. A quick phone call can save a lot of hassle later.

Watch premiums, limits, and enrollment rules

Compare total annual cost, not just monthly premiums: add deductibles, copays, and the maximum out-of-pocket to see real exposure. Note deadlines and rules for changing or canceling supplemental coverage; outside qualifying events, you may be locked in until the next enrollment period. Also check whether benefits change with age or include step-downs that affect later years.

Balance short-term savings against potential long-term bills so your choice protects both budget and access to care.

Conclusion

Spend an hour this enrollment season assembling documents, comparing real costs, and confirming provider networks. A clear, prioritized checklist helps you pick supplemental benefits that match likely needs without unnecessary extras. Small effort now can prevent expensive surprises and improve care access all year.