A Practical Routine to Grow Your Credit Health

Improving your credit score doesn’t require drastic measures; small, consistent actions add up over months. A clear routine helps you prioritize payments, manage balances, and spot errors early. This article outlines a practical monthly framework that fits busy schedules and supports steady progress. Follow manageable steps and adjust them as your financial situation changes.

Understand Your Starting Point

Begin by reviewing your credit reports and the numeric score from a reputable source to establish a baseline. Look for negative items, late payments, or identity errors that might be corrected or disputed. Note your current credit utilization and the age of accounts; both factors influence scoring models. Having specific metrics lets you set realistic monthly goals.

Record progress each month and revisit the baseline to measure improvement. Early wins build momentum and inform the next steps.

Monthly Actions That Move the Needle

Create a short list of recurring tasks to complete every month, such as paying bills on time, reducing revolving balances, and avoiding new hard inquiries. Prioritize paying at least the minimum due and schedule additional payments toward cards with the highest utilization. Consider setting up balance alerts and automatic payments to prevent accidental late fees. Small reductions in utilization and perfecting on-time payments significantly affect score calculations over time. Limiting new credit inquiries also helps maintain a stable profile.

  • Pay on time and keep balances low.
  • Lower credit utilization below 30% when possible.
  • Review reports and dispute errors promptly.

Keep the monthly routine simple so it’s sustainable. Consistency is more valuable than occasional large payments.

Monitoring, Patience, and Adjustments

Expect change to happen gradually; scoring models weigh long-term patterns more heavily than isolated actions. Review your strategy quarterly to decide if you should shift targets, such as focusing on older accounts or addressing collection items. Use free monitoring tools to receive alerts and verify that positive actions are reflected on your reports. Staying patient avoids impulsive moves that can set back progress.

If you encounter setbacks, prioritize rebuilding habits rather than quick fixes. Over time, steady improvements compound into meaningful score gains.

Conclusion

Building stronger credit is a process anchored in regular, measurable behaviors and careful monitoring. By setting a realistic monthly routine and adjusting as needed, most people can improve their profile without dramatic changes. Start with clear metrics today and let consistent action drive lasting results.
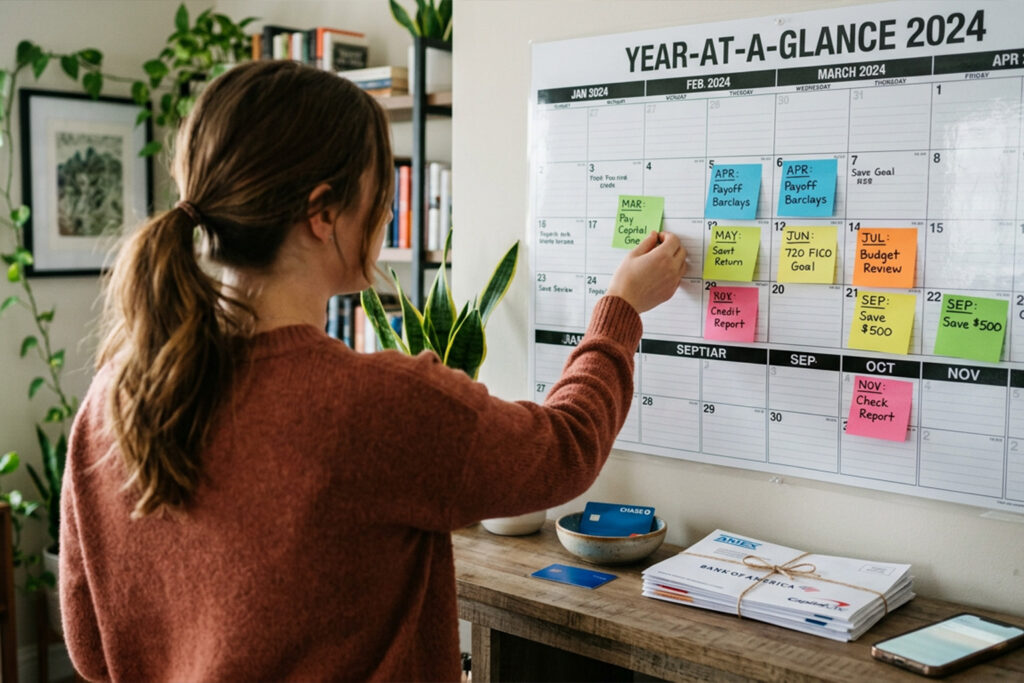
Habit-Based Steps to Build a Stronger Credit Record

Improving a credit record is less about dramatic moves and more about steady habits that add up over time. Small, repeatable actions — like paying on time, keeping balances modest, and watching your credit file — create reliable momentum. This article outlines practical, habit-focused steps you can adopt and maintain without stress. The goal is sustainable improvement rather than quick fixes.

Understand Your Credit Report

Start by obtaining and reviewing your credit report to know exactly what lenders see. Look for errors, unfamiliar accounts, or outdated information that could be dragging your score down. Understanding the factors that matter—payment history, utilization, age of accounts, and inquiries—helps you prioritize actions. Knowledge reduces guesswork and gives you a roadmap for targeted improvement.

Make a habit of checking your report at least annually and after major life changes. Correcting mistakes promptly can restore points you never knew you lost.

Build Predictable Payment Habits

Consistently paying bills on time is the single most influential habit for a stronger credit record. Automate payments or set calendar reminders to avoid missed due dates, even for small accounts. If cash flow varies, prioritize minimum payments to keep accounts current while chipping away at principal. Over time, punctual payments accumulate into a positive payment history that lenders value highly.

Create a simple monthly checklist that tracks due dates and balances. Reinforcing this routine reduces stress and keeps your accounts in good standing.

Manage Balances and Credit Mix

Keeping revolving balances low relative to limits—credit utilization—is a practical lever you can control. Aim to use a modest portion of available credit and pay down cards before statement closing dates when possible. Avoid opening multiple new accounts at once, but consider a small, well-managed installment or revolving account to demonstrate responsible variety. Lenders prefer a mix that shows consistent, low-risk borrowing behavior.

Regularly transfer surplus funds toward high-utilization cards and maintain older accounts when they help your average account age. These small adjustments add up.

Monitor, Adjust, and Protect

Monitoring your credit allows you to spot trends and react before small issues become large problems. Use alerts for new accounts or significant changes, and periodically reassess goals as your circumstances evolve. If you encounter setbacks, focus on steady recovery steps—timely payments, reduced utilization, and dispute resolution. Preventative measures like identity protection can also safeguard progress.

Be patient and treat improvement as a long-term process. Consistency and small course corrections typically produce the most durable results.

Conclusion

Strong credit grows from simple, repeatable habits that prioritize on-time payments and sensible use of credit. Monitor your report, manage balances, and adjust routines as needed to maintain momentum. Over months and years, these steady practices build a more resilient financial profile.

A Practical Yearlong Plan to Restore Credit Health

Restoring credit takes time, clear priorities, and steady habits.
This yearlong plan breaks the process into manageable monthly milestones you can follow.
It focuses on stability, positive reporting, and responsible borrowing to rebuild your profile.
Follow practical steps, adjust as needed, and track progress to stay motivated.

Why a Yearlong Approach Works

A year gives enough time for payment history and credit utilization improvements to reflect on reports. Short bursts of effort help, but sustained behaviour creates meaningful change in scoring models. Small, repeatable actions compound, especially when you prioritize on-time payments and lower revolving balances. This approach reduces rushed decisions and the risk of repeating mistakes.

Start by setting realistic monthly targets and tracking them. Regular reviews keep you accountable and reveal adjustments early.

Months 1–3: Stabilize Your Accounts

Begin by checking your credit reports and correcting any errors that harm your score. Bring past-due accounts current and establish automatic payments to avoid missed due dates. Prioritize high-impact actions like reducing credit card balances to under recommended utilization levels. These early corrections set the foundation for steady improvement.

  • Check reports for inaccuracies and fraud.
  • Enrol in automatic payments where possible.
  • Pay down the highest-rate or highest-balance card first.

Be conservative with new credit during this period. Conserving available credit and stabilizing balances makes later gains more reliable.

Months 4–8: Build Positive Patterns

Focus now on consistent positive reporting: on-time payments, modest use of credit, and keeping older accounts open when appropriate. Consider a secured card or a credit-builder loan if you need safe ways to add positive entries. Keep balances steady and resist closing accounts solely to ‘simplify’ unless there is a compelling fee reason. This stage is about demonstrating responsible credit over several months.

Document improvements and celebrate small wins to stay motivated. Small, repeated successes influence scoring models and lender perceptions.

Months 9–12: Optimize and Monitor

As you approach a year, fine-tune your approach: shop for better rates, request higher credit limits cautiously, and avoid hard inquiries that aren’t necessary. Use monitoring tools to watch for identity issues and to track score movements. If errors remain, dispute them again with clear documentation. At this stage you can also plan larger steps like refinancing or applying for new credit with improved terms.

Assess whether your goals have been met and set new targets for the next year. Continued vigilance prevents setbacks from erasing gains.

Handling Common Setbacks

Missed payments, collection notices, or identity fraud can reverse progress but are often manageable with prompt action. Communicate with creditors to negotiate plans, request goodwill adjustments after one-time mistakes, and freeze accounts compromised by fraud. If collections are present, explore pay-for-delete or validation strategies while keeping records of all communications. Rebuilding after setbacks may lengthen the timeline but still benefits from the same steady practices.

Be patient and prioritize rebuilding trust with lenders through consistent behavior. Professional counseling can help if debt feels overwhelming.

Conclusion

A year of focused steps can materially improve your credit health.
Consistency and monitoring are the most powerful tools you have.
Keep goals realistic and focus on steady progress.

Practical Credit Score Habits for Everyday Stability

Building reliable credit is less about dramatic moves and more about steady habits practiced over time. Small, consistent actions reduce risk and gradually improve the numbers lenders use. Many people see improvement simply by monitoring accounts and paying attention to timing. This piece outlines manageable steps that fit into a daily financial routine.

Start Small and Track Progress

Begin by pulling a copy of your credit report and checking it for errors, duplicate accounts, or old collections that should no longer appear. Set a simple tracking system—monthly or quarterly—to note changes in balances, inquiries, and overall score trends. Regular tracking highlights patterns, such as recurring late payments or increasing utilization, so you can intervene sooner. Consistent review reduces surprises and makes goal-setting more realistic.

  • Order a report from each bureau once a year on a rotating schedule.
  • Use a spreadsheet or an app to chart balances and due dates.

Small wins, like correcting a reporting error or reducing a single card balance, compound over time. Celebrate progress and adjust goals as your situation changes.

Use Credit Strategically

How you use credit influences scores more than how much credit you have. Keep utilization low by spreading balances across cards or paying down high balances before statement closing dates. Avoid opening multiple new accounts at once; each hard inquiry can temporarily lower scores and new accounts reduce average age of credit. Maintain a mix of installment and revolving accounts when it makes sense, but don’t add accounts solely for scoring reasons.

  • Pay at least the minimum on time every month and prioritize larger payments when possible.
  • Consider automatic payments for recurring bills to prevent missed due dates.

Strategic use emphasizes consistency and timing rather than quick fixes. Thoughtful choices today create a stronger profile for borrowing tomorrow.

Protect Your Credit File

Identity theft and errors can undo months of careful work, so protect access to your credit file. Place fraud alerts or freezes if you suspect compromise, and enable two-factor authentication on financial accounts. Monitor statements for unfamiliar activity and report suspicious items quickly to the creditor and the reporting bureau. Prevention and swift response limit damage and reduce long-term score harm.

Timely action after spotting issues matters as much as preventive steps. Keep contact information current with creditors so alerts reach you promptly.

Conclusion

Improving credit is a steady process built on consistent habits and regular monitoring.
Focus on timely payments, responsible utilization, and protecting your file from fraud.
Small, repeatable actions deliver measurable improvement over months and years.

Practical Habits to Build a Reliable Credit Foundation

Building and maintaining a strong credit profile is a gradual process that rewards consistent, well-informed habits. Small adjustments to how you use and manage credit can have a meaningful impact on your score over months and years. Focus on predictable behaviors like timely payments, sensible utilization, and regular monitoring rather than one-off fixes. This article outlines practical daily and monthly routines to help you strengthen credit fundamentals without dramatic changes to your lifestyle.

Know the Key Factors That Influence Scores

Your credit profile is shaped by several core elements including payment history, amounts owed, length of credit history, recent inquiries, and account diversity. Understanding which factors carry the most weight helps you prioritize actions that offer the greatest improvement. For many people, addressing late payments and reducing utilization produces faster gains than opening new accounts. Keep a snapshot of these priorities so you can align short-term choices with long-term goals.

Regularly reviewing these factors makes it easier to spot where gains are possible. Simple awareness can shift behavior toward healthier credit patterns.

Make Timely Payments a Nonnegotiable Routine

Payment history typically has the largest influence on credit assessments, so committing to on-time payments is essential. Automate minimum payments where possible and schedule reminders for larger balances to avoid missed due dates. If cash flow fluctuates, prioritize obligations that impact credit and communicate proactively with lenders when hardship occurs. Treating payments as a fixed monthly item helps protect long-term credibility.

Consistent on-time payments build positive records that compound over time. Small failures are costly, so prevention is more effective than recovery.

Manage Credit Utilization and Account Balances

Credit utilization—the ratio of balances to available limits—affects scores in the short term and can be managed monthly. Aim to keep utilization low across individual accounts and overall; paying down revolving balances before statement closing dates can lower reported utilization. Where feasible, request modest limit increases rather than opening new accounts, since new accounts can reduce average account age. Regularly reviewing balances and limits helps you make tactical decisions that improve utilization.

  • Target utilization below 30%, and lower for faster gains.
  • Pay down high-balance accounts first to reduce concentrated risk.

Small, repeated reductions in utilization often yield more reliable improvements than sporadic large payments. Discipline in this area supports both score and financial flexibility.

Monitor, Correct Errors, and Grow Credit Responsibly

Errors on credit reports are common and can drag scores down if left unaddressed, so routine monitoring is vital. Check your reports periodically, dispute inaccuracies, and document communications to resolve issues efficiently. Build credit responsibly through a mix of installment and revolving accounts, but avoid opening multiple accounts in a short window. Responsible growth paired with vigilance gives you a healthier profile over time.

Ongoing monitoring prevents surprises and helps you measure progress. Pair vigilance with steady habits for the best results.

Conclusion

Improving credit is less about quick fixes and more about consistent, measurable habits. Focus on timely payments, sensible utilization, accurate reporting, and steady account management. Over time, those practical routines form a reliable credit foundation.

Routine Money Moves That Grow Your Credit Score

Improving a credit score is rarely instantaneous; it responds to steady, intentional habits. Small routine decisions around payment timing, balances, and account use can compound into meaningful gains. This article outlines practical money moves you can adopt and sustain without drastic lifestyle changes. Follow these ideas consistently and you should see gradual, durable improvement in your credit profile.

These suggestions focus on behaviors consumers control and track. They complement formal advice like checking reports and disputing errors. Think of them as an operational playbook to repeat each month. Consistency matters more than perfect execution.

Focus on Payment Consistency

On-time payments are the single most influential habit for credit performance. Set up automatic payments or calendar reminders to avoid missed due dates and late reports. If cash flow is tight some months, prioritize required minimums to keep accounts current. Over time, a clean payment record builds momentum and credibility with lenders.

Start by reviewing due dates across accounts and aligning them to your pay schedule. Even small shifts can reduce accidental lapses. A reliable payment history is foundational and simple to maintain.

Keep Balances Low Relative to Limits

Credit utilization — the ratio of balances to limits — plays a major role in scoring models. Aim to use only a modest portion of available credit, ideally well under half and preferably below a third. Paying down balances before statement dates can lower reported utilization and improve monthly results. Consistently low utilization signals responsible account management to creditors.

  • Check statement dates and plan payments accordingly.
  • Target rotating payments to high-balance accounts first.
  • Consider small limit increases only if you won’t increase spending.

Regular attention to utilization keeps your profile efficient without changing spending habits drastically. Small reductions add up over a few reporting cycles. Combine this with on-time payments for best effect.

Use Accounts Strategically and Sparingly

Maintaining older accounts and using them occasionally helps age and activity metrics. Avoid closing long-established accounts unless there’s a compelling reason. When opening new credit, do so thoughtfully because multiple inquiries can temporarily affect scores. Use credit cards for routine, budgeted purchases and repay them promptly to show responsible usage.

Balance the benefits of available credit and account age with the need for flexibility. A small number of well-managed accounts often outperforms many neglected ones. Adopt a simple rule for any new application: will it help within the next year?

Monitor Progress and Adjust

Regularly review your credit reports and free score snapshots to understand how actions translate into results. Look for errors, unexpected inquiries, or accounts that need attention and address them promptly. Small course corrections—like shifting payment timing or trimming a balance—can change trends within a few months. Treat monitoring as an ongoing part of your routine, not a one-time task.

Set monthly checkpoints and note changes to prioritize next steps. Over time this habit turns reactive fixes into proactive improvements. Clear visibility reduces surprises and supports steady growth.

Conclusion

Improving credit is a process of repeated, sensible choices that compound over time. Keep payments consistent, manage utilization, and use accounts with intention. With steady monitoring and small monthly adjustments, your credit score can steadily improve.

A Clear Plan for Improving and Maintaining Credit

Improving your credit is a process that combines assessment, routine choices, and patience to produce measurable results over time. A clear, manageable plan reduces stress and creates steady progress across months rather than days, helping you prioritize the most effective moves. This article outlines practical and sustainable steps to help you repair, strengthen, and maintain a healthy credit profile while avoiding common missteps. Use these strategies to set priorities, build confidence, and prepare for future borrowing or major purchases with improved options and lower costs.

Assess Your Current Credit Standing

Start by requesting your credit reports and reviewing each account for accuracy, balances, payment history, and any unfamiliar items that may signal identity errors. Pay attention to accounts with high utilization, recent late payments, or those in collections, since these typically have the largest negative effect. Understanding the specific issues gives you a focused, prioritized plan and helps you estimate how long improvements might take under different strategies. Establish realistic target milestones, such as reducing utilization below 30 percent or removing specific inaccuracies through disputes.

With clear data, you can prioritize which actions will move your score most effectively and budget the time and resources needed. Regularly updating your assessment keeps goals relevant and prevents surprises when you apply for credit or insurance.

Create and Follow Predictable Credit Habits

Consistency in on-time payments and deliberate management of credit utilization are two of the most influential habits for long-term credit health, and small adjustments here can yield substantial benefits over time. Aim to pay at least the minimum on time every month, reduce revolving balances toward 30 percent of limits or lower, and consider targeting one high-balance account for accelerated repayment. Automating payments, setting calendar reminders, and tracking due dates help prevent accidental late payments that can linger on reports. Avoid opening multiple new accounts in a short period, since frequent inquiries and recently opened accounts can temporarily suppress scores while offering little immediate benefit.

Building predictable behaviors turns credit management into routine rather than a source of anxiety, and consistent progress reinforces those habits. Celebrate small wins like lowering a single high balance or maintaining a streak of timely payments to stay motivated.

  • Pay on time every month.
  • Keep balances low relative to limits.
  • Review reports at least annually for errors.

Monitor Progress and Adjust Strategies

Track your credit score and report changes so you can see which actions are effective and when to shift tactics; many online tools and services can provide monthly updates and trend visuals for free. If you identify errors that harm your score, dispute them promptly with documentation and follow up until they are resolved or explained. When deeper issues exist, such as significant debt or multiple collections, consider consulting a nonprofit credit counselor to develop a sustainable repayment plan and negotiate with creditors if appropriate.

Periodic review and small adjustments prevent minor problems from becoming major setbacks, and routine monitoring helps you maintain control of your progress. Treat monitoring as an ongoing part of your financial routine rather than a one-time task.

Conclusion

Improving credit is a gradual process built on clear assessment, disciplined habits, and ongoing monitoring. Set achievable targets, automate payments where possible, and celebrate milestones along the way to stay motivated. Over time these steady choices will translate into a stronger, more stable credit profile.

A Sustainable Plan for Gradual Credit Score Growth

Improving your credit score is rarely a sprint; steady, repeatable actions yield the best results.
This article outlines an achievable monthly routine you can adapt to your budget and goals.
Small adjustments to spending, payments, and monitoring habits compound over time.
The guidance here focuses on practical steps that reduce risk and build reliable history.
Use these suggestions to create clarity and momentum without extreme measures.

Why steady credit improvement matters

Lenders and service providers rely on credit history to assess risk, so consistent behavior matters more than isolated fixes. A steady improvement approach avoids the volatility that can come from chasing quick score gains. It also protects you from repeating costly mistakes by emphasizing habits over hacks. By focusing on sustainability, you create a stronger record of timely payments and responsible balances. Gradual improvements also reduce the temptation to rely on risky credit maneuvers.

This perspective shifts the goal from immediate numbers to lasting financial credibility. Over time, that credibility opens better borrowing options and lower costs. Treat the plan as iterative and adapt as your goals change.

Practical monthly habits to adopt

Start each month by reviewing upcoming bills and scheduling payments to clear before due dates. Keep credit utilization low by targeting balances under 30 percent of available limits and paying down high-interest accounts first. Automate recurring payments where possible to avoid late fees and preserve payment history. Limit new credit applications and assess whether inquiries are worth the potential short-term dip in scores. Reassess recurring subscriptions and trim costs that unnecessarily increase balances.

  • Set calendar reminders for key due dates.
  • Pay more than the minimum when possible to reduce principal faster.
  • Check credit reports for errors monthly or quarterly.

Simple, repeatable actions reduce cognitive load and make steady progress realistic. Small consistent payments and fewer surprises are the backbone of lasting improvement. Document progress in a simple spreadsheet or app to stay accountable.

Monitoring progress and adjusting course

Track your score and report snapshots monthly so you notice trends and identify mistakes quickly. When you see plateaus, examine specific drivers like utilization spikes, missed payments, or new inquiries. Adjust the plan by reallocating payments, pausing new spending, or disputing inaccuracies on your reports. Regular reviews help you celebrate small wins and recalibrate before minor setbacks become larger problems. Set realistic milestones like a utilization target or a streak of on-time payments to motivate persistence.

Be patient — meaningful score changes can take several months. Stay focused on the process and the results will follow. If needed, consult free educational resources to refine advanced strategies.

Conclusion

Consistent monthly habits build durable credit strength.
Measure progress and refine your approach.
Over time, disciplined routines translate into better borrowing options.

Stepwise Approach to Long-Term Credit Score Improvement

Improving your credit is less about sudden fixes and more about steady, intentional choices.
A clear plan helps you prioritize actions that deliver the biggest impact over time.
This article outlines practical habits and simple strategies you can adopt this month and sustain for years.
The goal is measurable progress without drastic lifestyle changes.

Understand Your Credit Report

Begin by reviewing your credit report to spot inaccuracies, unexpected accounts, or outdated information. A careful reading reveals payment history issues, high balances, or accounts in collections that most affect your score. Prioritize disputing genuine errors and gathering documentation for each dispute you submit. Knowledge of what influences your score lets you direct effort where it matters most.

Set a routine to check reports at least annually from each major bureau. Early detection prevents small problems from becoming bigger issues.

Build Practical Payment Habits

Payment history is a leading factor, so consistently paying at least the minimum on time should be your baseline habit. Automate payments where possible and set reminders for due dates to avoid missed payments. If you struggle with cash flow, negotiate alternative due dates with lenders or split payments across pay periods. Small steps that prevent late payments compound into substantial score improvements over time.

Focus first on reducing late payments and then on increasing payment amounts toward principal. These habits create reliable credit behavior lenders recognize.

Use Accounts Strategically

Manage credit utilization by keeping balances low relative to limits; aim for utilization under recommended thresholds. If you have a mix of installment and revolving accounts, maintain a healthy balance across both types to demonstrate diverse, responsible usage. Consider requesting limit increases or opening a small, well-managed account if that reduces overall utilization. Avoid closing older accounts solely for simplicity, as length of history and available credit can affect scoring.

  • Keep utilization low (preferably below 30%).
  • Avoid opening many new accounts at once.
  • Maintain older accounts when possible.

Strategic account use signals stability and restraint to scoring models. Small adjustments here often yield noticeable changes.

Monitor and Adjust Regularly

Track your progress with monthly reviews of balances, payments, and any changes to your report. Use alerts and budgeting tools to stay on top of due dates and avoid surprises that can harm your score. When you identify setbacks, create a short remediation plan: prioritize high-impact fixes like late payments or high utilization. Regular monitoring lets you adapt quickly and keep momentum.

Celebrate small wins to stay motivated and revise targets as your situation improves. Consistency is the most reliable path to lasting score gains.

Conclusion

Small, deliberate financial habits lead to steady credit improvement.
Understand your report, prioritize on-time payments, and manage credit strategically.
Monitor progress and make adjustments to sustain long-term results.

Designing a Sustainable Plan to Enhance Your Credit

Improving a credit score is best approached as a steady, disciplined process rather than a sprint. Small, measurable actions taken consistently tend to produce more reliable results than occasional large moves. This article offers a practical framework you can follow month to month to target the main factors that influence your credit profile. Use these steps to set priorities, measure progress, and adjust tactics when needed.

Assess Your Starting Point

Begin by obtaining the most recent copies of your credit reports and scores to identify where you stand. Look for high balances, missed payments, and any reporting errors that could be dragging down your score. Understand your credit utilization ratio across cards and note which accounts have older positive history. A clear snapshot of strengths and weaknesses helps you focus effort where it counts.

Make a concise list of the top three issues to address first and track them on a simple spreadsheet or app. Reviewing this list each month keeps priorities visible and prevents reactive decisions. Regular checks also make it easier to spot identity or reporting problems early.

Set Small, Measurable Goals

Translate your assessment into short-term goals that are specific and trackable. Examples include reducing overall utilization by 5 percentage points, bringing one account current, or disputing and resolving one inaccurate item on your report. Measurable goals let you celebrate incremental wins, which reinforces the habit of regular attention.

  • Reduce revolving utilization by 5% within 60 days.
  • Bring any past-due account to current within one billing cycle.
  • File disputes for up to two clear reporting errors each month.

Document timelines and check progress at monthly intervals. If a target isn’t met, revise the approach rather than abandoning the goal; small course corrections compound positively over time.

Adopt Consistent Credit Habits

Consistent behaviors create the conditions for sustained improvement in credit scoring. Prioritize on-time payments by automating due dates or setting calendar reminders and aim to keep card balances well below credit limits. Consider reallocating spending to cards with lower utilization or making multiple payments in a billing cycle to reduce reported balances.

Keep new credit applications limited while you stabilize balances and history. Over time, consistency in payments and lower utilization will generate better scoring outcomes without risky strategies.

Conclusion

Designing a sustainable credit plan means assessing your profile, setting realistic targets, and practicing consistent habits. Track progress monthly and make small adjustments rather than chasing quick fixes. Over time, these disciplined steps build a stronger, more reliable credit profile.