Credit Scores and Insurance Premiums: The Surprising Connection

Many people think credit scores only matter when applying for loans or credit cards—but they also play a significant role in determining insurance premiums. Whether it’s auto, home, or renters insurance, companies often use credit-based scoring models to predict how likely someone is to file a claim. This surprising connection can influence how much you pay each month, even if you’ve never had an accident or made a claim before. Understanding how credit impacts insurance costs helps you stay informed and take steps to manage your financial profile more effectively.

Why Insurers Use Credit Information

Insurance companies use data to estimate risk. Over the years, industry studies have shown a correlation between strong credit habits and lower claim likelihood. Because of this, insurers use credit-based insurance scores—not your full credit score—to predict customer behavior. These scores help determine how risky you may be to insure, which affects the rate you’re offered. While it may seem unrelated, insurers see credit history as a reflection of responsibility and long-term financial stability.

How Credit Influences Your Premiums

A higher credit score often leads to lower premiums. People with excellent credit tend to qualify for cheaper auto and home insurance rates. On the other hand, a lower score can increase monthly premiums even if your driving record or claim history is clean. For insurers, it’s all about statistical patterns—not personal judgment. Small improvements in your credit score can make a noticeable difference in the cost of your policy over time.

Which Types of Insurance Are Affected

Auto and homeowners insurance are the most common types where credit-based scoring is used. Renters insurance may also be affected, depending on the state and the insurer. Health insurance and life insurance typically do not use credit scores for pricing, but they may still review credit behavior during the application process. Knowing which policies rely on credit information helps you plan and budget more accurately.

Ways to Improve Your Insurance Rates

Because insurance premiums are influenced by credit, improving your score can lead to meaningful savings. Paying bills on time, lowering credit card balances, and reducing debt all contribute to a healthier financial profile. Checking your report regularly also helps you spot errors that could raise your premiums. As your credit score strengthens, you can request a rate review or compare quotes from multiple insurers to find better pricing.

Conclusion

Credit scores play a bigger role in insurance premiums than most people realize. By understanding this connection and taking steps to maintain strong credit habits, you can reduce costs and secure better long-term coverage. Improving your credit doesn’t just help with loans—it also unlocks lower insurance rates and greater financial stability.
The Future of Credit Scores in a Cashless Economy

As digital payments become the standard for everyday transactions, traditional measures of creditworthiness are starting to evolve. A cashless economy creates new patterns of financial behavior, offering more data points than ever before. This shift is prompting lenders and financial institutions to rethink how they evaluate risk and reliability. With technology reshaping spending, saving, and borrowing, the future of credit scoring is likely to look very different—and potentially more inclusive—than what we know today.

How Digital Payments Are Changing Financial Behavior

The rise of digital wallets, contactless payments, and peer-to-peer apps provides a clearer picture of how people manage day-to-day finances. These systems track spending in real time, making financial habits easier to monitor. As cash usage declines, digital footprints reveal consistent patterns—such as timely bill payments, responsible budgeting, and overall financial discipline—which may one day serve as indicators of creditworthiness.

New Data Sources May Expand Access

One of the biggest promises of a cashless economy is the potential for alternative data to support credit evaluations. Lenders may incorporate factors like rent payments, subscription history, utilities, or digital transaction records. For people with limited credit history, these signals could bridge the gap and provide opportunities previously out of reach. This shift could promote fairness by recognizing responsible behavior beyond traditional loans and credit cards.

Technology Will Play a Central Role

Artificial intelligence and advanced analytics are expected to influence future scoring models. These tools can analyze massive amounts of data quickly, identifying trends that would be difficult for humans to interpret. Smart algorithms may predict risk with greater accuracy while adapting to changes in financial behavior. This enhanced precision benefits both consumers and lenders, creating a more stable and transparent credit ecosystem.

Balancing Innovation With Privacy

While expanded data can improve credit access, it also raises concerns around privacy and security. Consumers may worry about how much personal financial information is being tracked and who controls it. As scoring models evolve, regulations and strong data protections will play a critical role in maintaining trust. The challenge will be finding the right balance between innovation and responsible use of digital financial data.

Conclusion

A cashless economy opens the door to a more dynamic, data-driven approach to credit scoring. As digital payments become universal, the future of credit may better reflect consumers’ everyday financial habits—creating a system that is more inclusive, accurate, and aligned with modern life.

How to Build Credit Without Using Credit Cards

Building credit is an essential part of financial independence, but many people prefer not to rely on credit cards to do it. Whether you’re avoiding debt or simply want alternative methods, the good news is that there are several effective ways to establish and grow a strong credit profile without ever swiping a card. By using tools, services, and smart everyday financial habits, anyone can create a reliable credit foundation that supports future goals like renting an apartment, buying a car, or securing low-interest loans.

Using Utility and Rent Payments to Strengthen Your Credit

One of the simplest ways to start building credit is by reporting payments you already make each month. Services now allow rent, electricity, water, internet, and even streaming payments to be added to your credit file. These routine bills demonstrate consistency and financial responsibility, which credit agencies value. When these payments appear on your credit report, they help paint a clearer picture of your reliability—even without traditional credit accounts.

Applying for a Credit-Builder Loan

A credit-builder loan is designed specifically for people who want to establish credit from scratch. Instead of receiving the money upfront, the loan amount is held in a secured account while you make small monthly payments. Once the loan is paid off, you receive the funds, and your successful payment history gets reported to credit bureaus. This method offers a safe way to build credit without the temptation to overspend.

Becoming an Authorized User on a Trusted Account

If a family member or close friend has a strong credit history, you can ask to be added as an authorized user on their account. You don’t need to use the card—or even have access to it—to benefit. As long as they maintain good payment habits, their positive history can reflect on your credit report. This strategy is especially helpful for young adults or those rebuilding their financial standing, though it requires trust and open communication.

Managing Installment Payments Responsibly

Loans such as student loans, auto loans, and personal loans can all support your credit profile when handled responsibly. Making on-time payments consistently sends a strong signal to lenders that you are financially dependable. Even if you’re paying off a small loan, maintaining a perfect track record can significantly improve your credit health over time.

Using Reporting Services and Financial Apps

Modern financial tools now offer ways to track your credit, automate payments, and ensure bills are always paid on time. Some apps can submit eligible payments directly to the credit bureaus, while others help monitor your score and offer guidance on improving it. These digital resources help you stay organized and avoid missed or late payments, which can negatively impact your progress.

Conclusion

Building credit without credit cards is completely achievable with the right strategies. By reporting everyday payments, exploring credit-builder loans, or leveraging responsible installment accounts, you can gradually create a solid financial reputation. With patience, consistency, and smart habits, your credit can grow stronger—without ever relying on a traditional credit card.

How Credit Scores Affect Your Ability to Start a Business

Starting a business takes more than a strong idea and passion—it also requires solid financial footing. One of the biggest factors influencing early business decisions is your personal credit score. Lenders, investors, and financial institutions rely on this number to evaluate how reliably you manage debt and whether you’re prepared to handle business expenses. A strong credit score doesn’t guarantee success, but it opens doors and provides entrepreneurs with the flexibility they need during the most critical stages of launching a business.

Access to Startup Capital

Most new business owners rely on outside funding to get started, whether through loans, lines of credit, or financing programs. Banks and lenders heavily consider personal credit scores when evaluating loan applications—especially if the business has no financial history. A higher score signals lower risk, improving your chances of approval and helping you secure better interest rates. Entrepreneurs with lower scores may face higher borrowing costs, smaller loan amounts, or outright denials.

Lower Interest Rates and Better Terms

Your credit score influences the cost of borrowing. Higher scores typically qualify for lower interest rates, meaning you pay less over time. For a new business with tight margins, even a small difference in interest rates can significantly impact long-term financial health. Better terms may also include longer repayment schedules, higher credit limits, and access to premium financial products designed for business growth.

Leasing Equipment and Commercial Space

Starting a business often involves leasing equipment, office space, or retail locations. Landlords and vendors commonly check personal credit to assess reliability before approving agreements. A strong score can make the leasing process smoother, while a weaker score may require higher deposits, personal guarantees, or stricter contract conditions. This can limit flexibility, especially for businesses that need specialized or costly equipment.

Building Early Business Credit

In the early stages of a business, lenders rely almost entirely on your personal credit. As the company grows, consistent on-time payments, responsible spending, and good financial records help build business credit. Strong personal credit makes it easier to get approved for the tools needed to begin this process—such as business credit cards, trade lines, and small vendor accounts. Over time, good business credit reduces your dependence on personal scores when seeking financing.

Improving Your Credit Before Launching

Entrepreneurs can strengthen their credit before starting a business by paying bills on time, reducing credit card balances, checking reports for errors, and avoiding unnecessary new debt. Even small improvements can raise your score and increase the likelihood of better loan terms. Entering the entrepreneurial world with strong credit provides a financial cushion and reduces stress during the challenging launch period.

Conclusion

Your personal credit score plays a major role in your ability to secure funding, lease space, and access essential resources when starting a business. A strong score gives you more options, better terms, and greater financial confidence. By understanding the impact of credit and preparing early, entrepreneurs can set the foundation for a smoother, more successful business journey.

How Social Media Behavior Could Affect Future Credit Ratings

As digital footprints grow, the world of credit assessment is beginning to explore new ways of understanding financial responsibility. While traditional credit scores are still based on payment history, credit utilization, and account age, future models may consider additional data sources—including online behavior. Social media activity has become a rich source of personal insights, raising questions about whether it could one day influence how creditworthiness is evaluated. Understanding how this trend might evolve helps consumers stay informed in an increasingly digital financial landscape.

Why Social Media Data Is Being Considered

Lenders are constantly searching for more accurate ways to predict risk. Social media platforms reveal patterns in lifestyle, stability, and spending habits that traditional models cannot capture. For example, consistent employment updates, professional networking activity, or stable location history may signal reliability. While this data is not currently part of mainstream credit scoring, some fintech firms are experimenting with alternative models that use digital behavior as an added indicator of financial stability.

Potential Indicators Lenders Might Examine

If social media becomes part of credit evaluation, lenders may analyze signals related to responsibility and financial consistency. Public posts showing frequent impulse purchases, risky behavior, or sudden lifestyle changes could raise red flags. On the other hand, profiles that reflect career growth, community involvement, or long-term stability may be seen as positive indicators. Even how individuals interact online—such as maintaining professional connections or responding respectfully—could theoretically play a role in future credit models.

Privacy and Ethical Concerns

The idea of using social media for credit decisions raises significant privacy questions. Many consumers worry about how much information lenders could access and how fairly it would be interpreted. Misreading sarcasm, humor, or personal expression could lead to biased assessments. As a result, regulators and consumer protection groups continue to emphasize the need for transparency, consent, and strict limits on how personal data is used. Any future system would require strong safeguards to prevent discrimination or misuse.

What Consumers Can Do Today

Even though social media isn’t part of credit scoring today, online behavior still affects long-term financial opportunities. Employers, landlords, and business partners often review public profiles before making decisions. Maintaining a positive digital presence—free of unnecessary conflict, risky posts, or misleading impressions—can support both personal and professional credibility. As technology evolves, being mindful of digital footprints becomes increasingly important.

Conclusion

Social media behavior may play a larger role in financial assessments as technology advances. While traditional credit scores remain the standard, digital signals could one day help lenders build a more complete picture of consumer reliability. Staying aware of your online presence—and how it reflects your lifestyle and choices—helps prepare for a future where digital identity and financial credibility may be more closely connected.

Tiny On-Time Wins: How Minor Payments Lift Scores

Improving your credit score doesn’t always require massive financial shifts or major debt repayments. Often, the secret lies in small, consistent wins—tiny payments made on time that gradually build a record of financial reliability. These micro-actions can have a surprisingly large impact over time, helping your score rise steadily and sustainably.

The Power of Punctuality

Credit scoring models heavily favor consistency. Each time you make a payment on or before the due date, it signals to lenders that you’re dependable and financially disciplined. Even if the amount is small, like a minimum balance on a credit card or a small utility bill—on-time payments demonstrate reliability and reduce the risk associated with lending to you.

Why Small Payments Matter

Credit systems don’t just measure how much you pay—they measure how consistently you pay. Paying smaller bills promptly helps establish a stable financial rhythm that lenders value. Over time, these consistent behaviors help build a strong payment history, which makes up a significant portion of your credit score.

Turning Micro Payments into Macro Impact

The key is automation. Setting up automatic payments for recurring bills—such as phone plans, subscriptions, or low-balance loans—ensures you never miss a due date. These automated habits create momentum, reinforcing positive behavior without requiring constant attention. Over months, these punctual transactions accumulate, contributing to gradual but lasting score improvement.

Building Confidence Through Consistency

Small payments also have a psychological advantage: they build financial confidence. Seeing your credit score improve through small, manageable actions reinforces motivation and creates momentum for larger goals, like clearing high-interest debt or saving for future milestones. The satisfaction of steady progress turns financial discipline into a rewarding routine.

Conclusion

Tiny, timely payments may seem insignificant, but together they form the foundation of a strong credit profile. By prioritizing punctuality over size, you send a consistent message of trustworthiness to lenders. In the long run, these small, on-time wins don’t just lift your score, they reshape your entire financial outlook, one payment at a time.

The Impact of Hard vs. Soft Inquiries on Your Score

Credit inquiries play a subtle but important role in determining your credit score. Whether you’re applying for a loan, credit card, or even a new apartment, lenders often check your credit history to assess risk. However, not all credit checks are the same. Understanding the difference between hard and soft inquiries—and how they affect your score—can help you manage your credit health more effectively.

What Is a Hard Inquiry?

A hard inquiry occurs when a financial institution checks your credit report as part of a lending decision. This usually happens when you apply for credit—such as a mortgage, car loan, or new credit card. Because it indicates that you’re actively seeking new debt, a hard inquiry can temporarily lower your credit score by a few points, typically between 5 and 10.

While one or two hard pulls aren’t a big deal, multiple inquiries in a short time can signal risk to lenders. For example, applying for several credit cards within a few weeks may make it seem like you’re taking on too much debt. Fortunately, credit scoring models like FICO and VantageScore treat multiple inquiries for the same type of loan (such as a mortgage or auto loan) made within a short period—usually 14 to 45 days—as a single inquiry.

What Is a Soft Inquiry?

A soft inquiry, by contrast, does not impact your credit score. These checks occur for informational or background purposes rather than lending decisions. Examples include checking your own credit report, prequalification offers, or employer background checks. Because they aren’t linked to a specific credit application, soft inquiries remain visible only to you and don’t affect how lenders view your creditworthiness.

When and How to Manage Inquiries Wisely

If you’re planning a major purchase, it’s smart to minimize unnecessary hard pulls. Avoid applying for multiple lines of credit at once, and space out applications when possible. You can also use prequalification tools—these use soft inquiries—to see potential loan terms without affecting your score. Regularly reviewing your credit report ensures accuracy and helps you catch any unauthorized hard inquiries, which could be signs of identity theft.

How Long Inquiries Stay on Your Report

Both hard and soft inquiries appear on your credit report for up to two years, but only hard inquiries influence your score. Even then, their effect fades over time, typically disappearing from scoring calculations after about 12 months. Maintaining consistent on-time payments and low credit utilization has a much greater impact on your score than a few inquiries.

Conclusion

Credit inquiries are a small but meaningful part of your financial picture. While hard inquiries can slightly lower your score, their impact is temporary and manageable. By understanding when and how to apply for credit strategically, you can protect your credit health and continue building a strong, reliable financial foundation.

How Student Loans Affect Your Credit Score

Student loans are often the first major financial responsibility many young adults take on. While they make education accessible, they also become a long-term commitment that impacts credit health. Understanding how these loans influence your credit score can help you make smarter borrowing and repayment decisions that support your future financial goals.

Student Loans Build Credit History

One of the biggest advantages of having student loans is that they help establish a credit history. Credit bureaus track how you manage your loans—whether you make payments on time and how consistently you do so. Because student loans are installment accounts, they show your ability to handle structured, long-term debt. Regular, on-time payments can help build a solid foundation for your credit profile, which is essential for future goals like renting an apartment, buying a car, or applying for a mortgage.

Late Payments Can Lower Your Score

On the flip side, missed or late payments can seriously hurt your credit score. Most lenders report missed payments after 30 days, and these marks can remain on your report for up to seven years. Even one late payment can lower your score and make it harder to qualify for favorable interest rates later. Setting up auto-pay or reminders through your loan servicer’s portal is an easy way to stay current and avoid penalties that damage your credit.

Loan Balances and Credit Utilization

While revolving accounts like credit cards rely heavily on utilization ratios, installment loans like student debt affect your score differently. The total loan balance compared to the original amount still plays a role, but less significantly. Over time, as your balance decreases, it shows lenders that you’re responsible and capable of managing debt, gradually improving your score. Keeping your accounts in good standing is more important than paying them off early if it strains your budget.

Diversifying Your Credit Mix

Credit scoring models also consider the variety of accounts you manage. Having a mix of installment loans (like student loans) and revolving credit (like credit cards) can slightly boost your score. Student loans demonstrate long-term repayment capability, which complements other forms of credit and builds overall financial credibility. However, it’s best to manage this mix wisely—avoid taking on new debt just for the sake of improving your score.

Conclusion

Student loans can either strengthen or weaken your credit score depending on how you manage them. Consistent, on-time payments and steady progress toward repayment build trust with lenders and set you up for financial success. Treating your student loans as both an educational and financial responsibility can help you graduate with more than just a degree—it helps you build lasting credit health.

Renting a Home? Your Credit Score Might Matter

When it comes to renting a home in the U.S., your credit score can play a bigger role than you might think. While most people associate credit scores with loans or credit cards, landlords and property managers often use them to assess a renter’s financial reliability. Whether you’re applying for your first apartment or moving into a new neighborhood, understanding how your credit impacts rental decisions can help you prepare — and improve your chances of approval.

Why Landlords Check Credit Scores

A credit score gives landlords a snapshot of your financial behavior. It reflects how consistently you pay bills, manage debt, and handle credit over time. A higher score signals financial responsibility, suggesting you’re more likely to pay rent on time. Most landlords in the U.S. check credit reports through agencies like Experian, Equifax, or TransUnion to evaluate rental applications. Some property managers also use tenant screening services that include credit history, income verification, and rental background checks.

What Credit Range Landlords Look For

While there’s no universal requirement, many landlords prefer tenants with a credit score of at least 650. In competitive rental markets — especially in large cities — higher scores (above 700) can give applicants an advantage. However, a lower score doesn’t automatically mean rejection. Many property owners consider other factors such as proof of steady income, references, or a larger security deposit. Some even allow co-signers to strengthen an application.

How to Strengthen Your Rental Application

If your credit score isn’t perfect, there are still ways to make your application stand out. Providing recent pay stubs, bank statements, and letters of recommendation from previous landlords can build trust. Offering to set up automatic payments or prepaying a few months’ rent can also reassure landlords of your reliability. Being transparent about past credit issues — and showing evidence of improvement — often works in your favor.

Improving Your Credit Before Renting

Before starting your home search, check your credit reports from all three major bureaus for errors or outdated information. You can access free annual reports at AnnualCreditReport.com. Pay down high balances, make payments on time, and avoid opening new credit lines right before applying for a rental. Even small improvements in your score can make a noticeable difference in approval odds and lease terms.

Why It Matters Beyond Approval

A strong credit score doesn’t just help you secure a rental — it can also lead to better lease terms. Tenants with higher scores may be eligible for lower security deposits or more flexible payment options. Additionally, maintaining good credit while renting sets you up for future goals, such as qualifying for a mortgage or lower insurance premiums.

Conclusion

In today’s rental market, your credit score is more than just a financial number — it’s part of your rental reputation. By understanding how landlords use it and taking steps to improve your credit health, you can make your next rental experience smoother and more affordable. Good credit opens doors — quite literally — to the home you want.


How to Use Credit Cards Without Damaging Your Score

Credit cards can be powerful tools for building financial health — if used wisely. They offer convenience, fraud protection, and even rewards. However, careless use can quickly lead to debt and a lower credit score. Knowing how to manage your cards responsibly helps you enjoy their benefits while maintaining a strong credit profile.

Understand How Credit Scores Work

Your credit score reflects how reliably you manage borrowed money. It’s based on several key factors:

  • Payment history (35%) – paying on time is the most important factor.

  • Credit utilization (30%) – how much of your available credit you’re using.

  • Length of credit history (15%) – older accounts improve your score.

  • New credit inquiries (10%) – too many applications can temporarily lower your score.

  • Credit mix (10%) – having a variety of credit types (cards, loans) helps.

By understanding these components, you can make informed decisions about spending, payments, and new credit applications.

Pay On Time, Every Time

Even one missed payment can cause significant damage to your score and result in late fees or higher interest rates. Setting up automatic payments or calendar reminders ensures you never miss a due date.

If you can, pay your full balance each month to avoid interest charges. At the very least, pay more than the minimum to reduce your debt faster and show lenders that you’re a responsible borrower.

Keep Your Utilization Low

Your credit utilization ratio is the percentage of your available credit that you’re using. For example, if you have a $5,000 credit limit and carry a $1,000 balance, your utilization is 20%.
Experts recommend keeping it below 30%, and ideally under 10%. High balances signal risk to lenders and can lower your score — even if you pay on time.

Avoid Opening Too Many Accounts at Once

Each time you apply for a new credit card, it triggers a hard inquiry on your credit report, which can temporarily lower your score. Opening multiple cards in a short period can also make you appear overextended. Instead, apply strategically and only when necessary — for example, to earn specific rewards or increase your total credit limit.

Keep Older Accounts Open

The length of your credit history contributes to your score, so think twice before closing an old account. Even if you no longer use the card often, keeping it open (and occasionally making small purchases) helps maintain your credit age and overall limit, both of which support a healthy score.

Monitor Your Credit Regularly

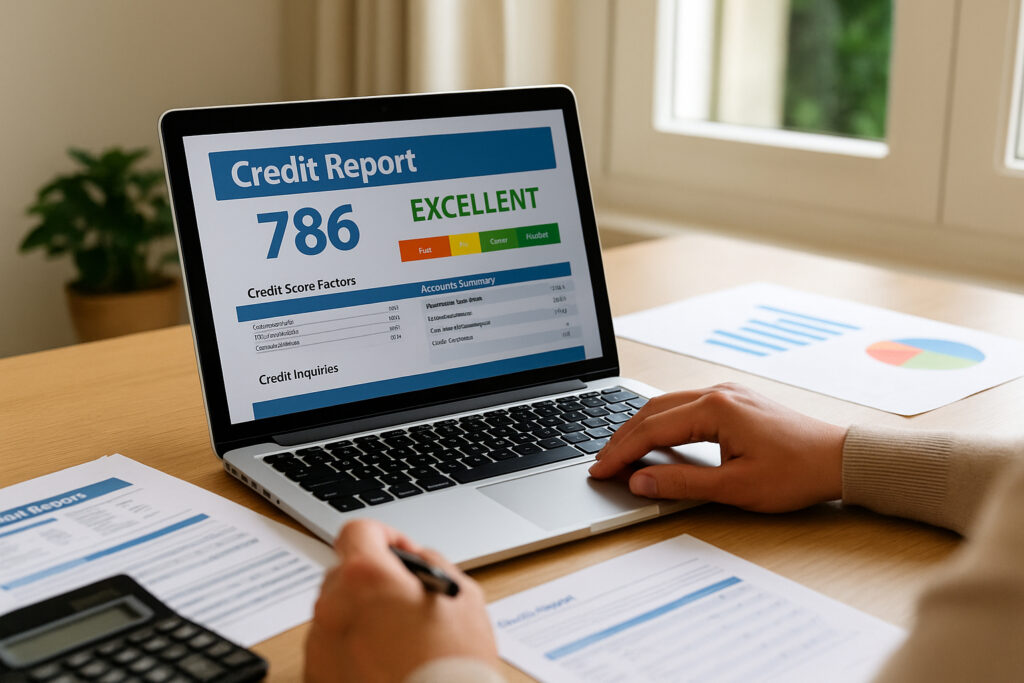
Monitoring your credit report allows you to catch errors, fraudulent charges, or unexpected changes early. You can access free reports annually from major credit bureaus or use credit monitoring tools to stay informed. Reviewing your report also helps you understand how your financial habits impact your score over time.

Use Rewards Responsibly

Cashback, points, and miles can make credit cards attractive — but they can also tempt overspending. Always prioritize financial discipline over rewards. A strong credit score will save you far more money in the long run than any short-term bonus.

Conclusion

Using a credit card responsibly is all about balance — spending within your means, paying on time, and keeping debt low. By managing your utilization, tracking your accounts, and maintaining consistent habits, you can build a credit history that opens doors to better financial opportunities. With smart use, your credit card becomes not a liability, but a lifelong asset.