Which Supplemental Benefits Save You the Most Money?

Deciding which supplemental insurance benefits are worth the cost can feel overwhelming.
Start by looking honestly at what you use most and what would be expensive without coverage.
Small monthly premiums add up, but so can one unexpected hospital bill or long prescription run.
This piece walks through practical ways to spot the benefits that likely deliver the biggest savings.

Start with your likely expenses

Look at the care you receive today and what is reasonably likely in the next few years. If you take several prescription medications, drug coverage usually saves more than routine visit benefits. For people who rarely see specialists, vision or dental riders may be lower priority. Estimating one or two high-cost scenarios helps you weigh premium cost against potential out-of-pocket exposure.

Build a realistic list of services you expect to use and their typical prices without insurance. That comparison makes it easier to see where a benefit pays for itself quickly. Keep the list and review it each enrollment period.

Compare benefits, not just premiums

Two plans with similar monthly costs can differ greatly in what they actually pay. Examine limits, copays, annual caps, and whether the plan has waiting periods for services like dental or hearing aids. Also check whether the plan requires a specific provider network or preauthorization for expensive treatments.

  • Prescription drug tiers and true out-of-pocket costs
  • Annual maximums on dental and vision benefits
  • Coverage for outpatient therapies or home health care

Look for benefits that close a real financial gap rather than adding coverage you already have. A clear side-by-side comparison prevents surprises later.

Watch for coordination and exclusions

Understand how a supplemental plan coordinates with your primary coverage. Some plans fill deductibles and copays; others pay only after the primary insurer. Exclusions and caps can make an appealing-sounding benefit nearly useless in a major claim.

Ask for concrete examples from the insurer showing how a typical claim would be paid. Those examples reveal whether the benefit actually reduces your likely expenses or just overlaps existing coverage.

When to buy, drop, or adjust a plan

Timing matters: enroll when your health needs change or during open enrollment windows to avoid gaps. If a benefit went unused for several years, consider dropping it and reallocating funds to more likely risks. Conversely, if a diagnosis increases your expected costs, adding targeted coverage can be economical even with a higher premium.

Small annual adjustments can keep your insurance aligned with reality and budget. Schedule a yearly review to confirm priorities and prices still match your needs.

Conclusion

Choose benefits that reduce predictable, high-cost exposures rather than those that sound appealing.
Compare real claim examples and coordination rules, not only monthly premiums.
A short yearly review will keep your supplemental coverage delivering value.
Thirty-Minute Monthly Tasks That Strengthen Credit

Improving your credit doesn’t demand dramatic moves or complicated spreadsheets. Small, consistent monthly tasks can nudge your score upward and reduce stress around money. Spend thirty focused minutes a month, and you can prevent common credit slip-ups while building steady momentum. The following steps are practical, specific, and designed to fit into a busy life.

Set a Simple Payment Routine

Late payments are one of the fastest ways to harm your credit, so start by creating a short routine dedicated to bills. Use calendar reminders, automatic transfers, or a single day each month to review upcoming due dates and confirm payments. If you have multiple cards, prioritize minimum payments to avoid late fees and late marks on your report.

  • Pick one day for bill review each month and block it in your calendar.
  • Set up autopay for recurring bills where possible, leaving manual payments for accounts you actively manage.

Spending just a few minutes confirming that payments processed keeps you ahead of issues and reduces the chance of an overlooked due date. Treat this as a non-negotiable monthly check-in.

Trim Your Credit Utilization

How much of your available credit you use matters more than the number of accounts. Aim to keep balances under 30% of each card’s limit, and lower if you can. If a balance creeps up, a quick transfer or an extra payment before your statement closes can bring utilization down and improve reported numbers.

Regularly moving small amounts—rather than waiting until balances feel out of control—lets your utilization reflect responsible behavior. These adjustments take little time and can show up on credit reports in a single billing cycle.

Check Reports and Dispute Errors

Monthly monitoring catches identity issues, incorrect balances, or accounts that should be closed but remain active. Pulling a free report or using a trusted monitoring tool takes minutes and helps you spot mistakes before they cost points. If you find an error, file a dispute promptly and document communications.

Even minor inaccuracies can hold your score back, so treat this as preventive maintenance. Resolving mistakes early keeps your history accurate and your options open for better rates and approvals.

Conclusion

Thirty focused minutes each month can prevent costly mistakes and steadily improve your credit profile. Build a short routine of payment checks, utilization control, and report reviews to create forward momentum. Small, repeatable actions add up to meaningful results over time.

Simple, Practical Rules for Everyday Card Management

Credit cards can feel like tools for convenience or sources of stress, depending on how you use them. A handful of clear, repeatable rules keeps rewards coming without surprise bills. This piece lays out practical habits you can start this month to reduce friction and preserve your cashflow. No jargon, just straightforward steps that fit into a busy life.

Set a clear card hierarchy

Decide which card is primary, which is for niche spending, and which you keep for emergencies. Your primary card should cover most daily purchases and be the one you pay automatically. Keep one or two secondary cards for specific categories like groceries or travel where they earn more. Closing or sidelining extra cards avoids decision fatigue at checkout and helps you track statements more easily.

Label cards in your phone wallet app and on a one-page cheat sheet if you need to. That small habit reduces last-minute swaps and forgotten balances.

Match cards to recurring spending

Look at regular payments—subscriptions, utilities, grocery runs—and pick the best card for each. Assigning cards to predictable charges makes rewards predictable and simplifies which balances you carry. Use calendar reminders for annual fees and reprioritize cards when reward rates change. A brief quarterly check prevents tiny mismatches from becoming costly habits.

  • Everyday purchases: use your highest flat-rate or rotating category card.
  • Big recurring bills: put them on a card with strong protection and clear payoff plans.
  • Travel or dining: reserve a bonus card for months when you spend more in those categories.

Keeping assignments simple means you can set it and mostly forget it, while still claiming most available rewards.

Lock in a payment and review rhythm

Automate minimums and schedule one weekly or biweekly check to catch unexpected charges. Paying on the statement due date avoids interest and helps you forecast cashflow. Once a month, review high balances and transfers that could trigger fees or higher interest. If something slips, act quickly to dispute errors or adjust your payment plan.

Small, regular scans are far more effective than occasional deep dives. That steady attention keeps surprises off your balance and preserves credit health.

Conclusion

Adopt a simple hierarchy, match cards to predictable spending, and set a steady payment rhythm. These modest habits cut stress and help you keep rewards without extra work. Start with one change this week and build from there.

When Supplemental Coverage Becomes Worth the Cost

Deciding whether to add a supplemental policy is less about fear and more about arithmetic and habits. Look past headlines and focus on the specific services your primary plan limits or leaves out. Think about the care you already use, how often you travel, and which bills would hurt your monthly budget. A few deliberate comparisons usually reveal whether extra coverage will pay off or just add another premium.

Know the gaps in your base plan

Primary health plans often cover core services but leave predictable gaps that matter to individuals. Common shortfalls include dental work, routine vision care, hearing aids, outpatient prescription costs, and long-term care support. Understanding these gaps in dollar terms — estimated annual out-of-pocket costs — makes it easier to judge the value of a supplemental policy. Don’t guess: request a benefits summary and recent claims history when possible.

  • List routine expenses you currently pay out of pocket.
  • Estimate one-off or uncommon costs you could realistically face.
  • Check whether the base plan limits brand-name drugs or specific therapies.

Once you’ve mapped likely expenses, compare them to the supplemental premiums and any waiting periods. If premiums add up to more than the protection they provide, consider carving out only the benefits you really need.

Match benefits to your health and habits

Age alone shouldn’t dictate coverage choices; your medical history and daily life should. If you visit specialists often or use several prescriptions, prioritize plans that lower copays and prescription gaps. Frequent travelers might value emergency overseas benefits more than expanded local dental coverage. Likewise, if family history points to long-term care needs, look for plans that include or attach riders for assisted living or home health support.

Tailoring benefits avoids paying for coverage you’ll rarely use and reduces the chance of surprise bills when you do need care. Small adjustments can change a supplemental plan from unnecessary to genuinely useful.

Compare price, networks and claims performance

Price matters, but so does how a plan pays claims and which providers are in-network. A cheaper premium means little if reimbursements are slow or a preferred doctor is out of network. Read policy language on caps, exclusions, and preexisting condition rules. Ask insurers about average claim turnaround times and whether they offer direct billing with major providers.

Balance monthly cost with realistic benefits and service quality rather than chasing the lowest premium. A modestly higher premium that reliably covers a big expense can be the better financial choice.

Conclusion

Supplemental insurance is worth considering when it fills predictable, meaningful gaps in your primary coverage. Compare expected out-of-pocket costs with premiums and prioritize benefits that match your health needs and lifestyle. Make choices based on clear numbers and practical trade-offs rather than sales pitches.

Slow, Smart Steps to Better Credit Scores

Credit scores rarely shift suddenly, but steady habits compound into meaningful gains. You don’t need perfect history or big payments to make progress; small, intentional moves often matter more. This piece focuses on practical actions—timing your payments, trimming balances, and watching your reports—that you can maintain month after month. Pick a couple of tactics that fit your routine and build from there, because consistency beats bursts of effort every time.

These suggestions are designed to reduce stress while nudging scores upward. Expect gradual change rather than overnight fixes.

What moves the needle

Payment history is the single largest influence on most credit models: on-time payments pay dividends. Credit utilization, the share of your available revolving credit that you’re using, is the fastest lever you can pull; keeping it low signals responsible borrowing. Other factors include the length of credit history, the mix of account types, and recent inquiries or new accounts. All of these combine differently depending on which scoring model a lender uses, so minor trade-offs are normal.

Focusing on on-time payments and utilization will usually yield the clearest early improvements. Treat other factors as background work that grows in importance over longer stretches.

Small habits that genuinely help

Automating payments stops accidental late marks, which can linger and drag scores down. Pay down cards before the statement closing date to lower the reported balance, which often lowers utilization more effectively than waiting until the due date. Keep new account openings sparing and staggered, because each hard inquiry and new line can temporarily suppress your score. Gentle, repeatable moves are easier to maintain than drastic changes.

  • Set autopay for at least the minimum amount.
  • Make a mid-cycle payment to reduce reported balances.
  • Review your credit report once a quarter for errors.

Start with one habit from the list and add another once it becomes routine. Over months, these low-effort steps tend to add up into measurable progress.

Fixes after missteps

If you miss a payment, act fast: contact the lender to request a goodwill adjustment or set up a catch-up plan to avoid further damage. Dispute clear errors on your reports promptly; removing inaccuracies can produce quick score gains. Consider tools like secured cards or becoming an authorized user to rebuild positive history when accounts are thin or damaged. Keep expectations realistic—major recovery often takes time, but there are practical paths forward.

Monitor progress and document communications with creditors. Patience and steady corrective steps are the most reliable route back to stronger scores.

Conclusion

Improving credit is a marathon of small, repeatable choices rather than a sprint. Prioritize timely payments and lower utilization, add one habit at a time, and check reports regularly. Over months, those steady moves typically produce durable improvement.

Simplify Your Wallet: A Practical Card Prioritization Plan

Most of us carry more plastic than we need, and the clutter makes decision-making slower and bills harder to track. A short, repeatable method for prioritizing cards keeps benefits where they matter and reduces monthly stress. This piece outlines a straightforward plan you can set up in one sitting and maintain with a few minutes each month. No extreme cuts, just clearer choices.

Start by accepting that fewer well-chosen cards often beat a handful kept for every possible perk. The goal is simplicity and predictable habits that protect your cash flow and credit score.

Why prioritize cards, not maximize perks

Chasing every category bonus leads to fragmented spending and missed payments, which erodes value quickly. When you pick a primary card for regular purchases and a secondary for rotating or travel perks, you reduce mental overhead. Prioritization helps you align cards with real monthly patterns instead of theoretical rewards. That alignment makes it easier to pay balances in full and avoid interest.

Keeping fewer active cards also reduces the chance of overlooked statements and unexpected fees. It creates a clear path for improving or protecting your credit over time.

A three-step prioritization method you can use tonight

First, list every card and note where you currently spend: groceries, gas, subscriptions, travel, or bills. Second, match each major spending category to the card that offers the best, consistent return or protection. Third, assign one card as your everyday card, a backup for categories the primary doesn’t cover, and an emergency-only card kept for fraud protection or unexpected situations.

  • Step 1: Inventory cards and recent statements.
  • Step 2: Match cards to recurring spending categories.
  • Step 3: Set roles—everyday, category backup, emergency.

With roles assigned, make small changes: move recurring charges to the chosen cards and automate payments to avoid late fees. The setup takes little time but pays off in clarity.

Practical habits to keep the system working

Once roles are set, check the setup every three months and after any major life change. Use calendar reminders for payment due dates and one monthly review to confirm categories still match. If a card loses value or adds a fee, consider replacing it only when the new card clearly fits a role.

Small habits matter: set autopay for the statement balance, keep card details updated where needed, and remove cards from your wallet that aren’t in rotation. Those steps stop accidental overspending and keep the system lean.

Conclusion

Prioritizing cards reduces friction, helps you capture dependable rewards, and lowers the risk of missed payments. Spend a single evening pairing cards with real monthly habits and maintain the plan with brief, regular check-ins. The result is a simpler wallet that supports your budget without constant juggling.

Five Things to Check Before Buying Supplemental Insurance

Supplemental insurance can fill the gaps left by a primary plan, but not every add-on is worth the premium. Start by identifying routine costs and exposures you already pay out of pocket. A clear, focused checklist makes it easier to compare what different policies actually cover. This piece walks through five practical checks to help you avoid surprises and choose coverage that fits everyday life.

Start with the gaps your main plan leaves

Before shopping for extras, list the services your primary coverage either limits or excludes. Look at copays, deductibles, and whether common needs—like urgent care, mental health visits, or durable medical equipment—have high out-of-pocket costs. Understanding these gaps prevents buying redundant coverage that only overlaps existing benefits. That clarity narrows your choices and keeps premiums targeted to real needs.

Once you document those gaps, prioritize them by frequency and cost. Frequent low-cost needs and rare high-cost events should be weighed differently. This helps you decide whether to insure for predictable expenses or rare catastrophes.

Match benefits to likely services

Not all supplemental policies are created equal: some focus on dental and vision, others on hospital indemnity or prescription drug gaps. Choose benefits that reflect your health patterns, current prescriptions, and anticipated checkups. Think seasonally too—if hearing or mobility supports are likely, look for specific riders rather than generic coverage. A narrowly targeted plan can offer more useful protection for less money.

  • Dental or vision for regular, predictable care.
  • Hospital or critical-illness riders for high-cost events.
  • Prescription gap plans if you regularly hit coverage limits.

Compare plans by the same benefit type rather than across types. That makes apples-to-apples comparisons simpler and highlights real differences in payouts and caps.

Compare costs, limits, and exclusions

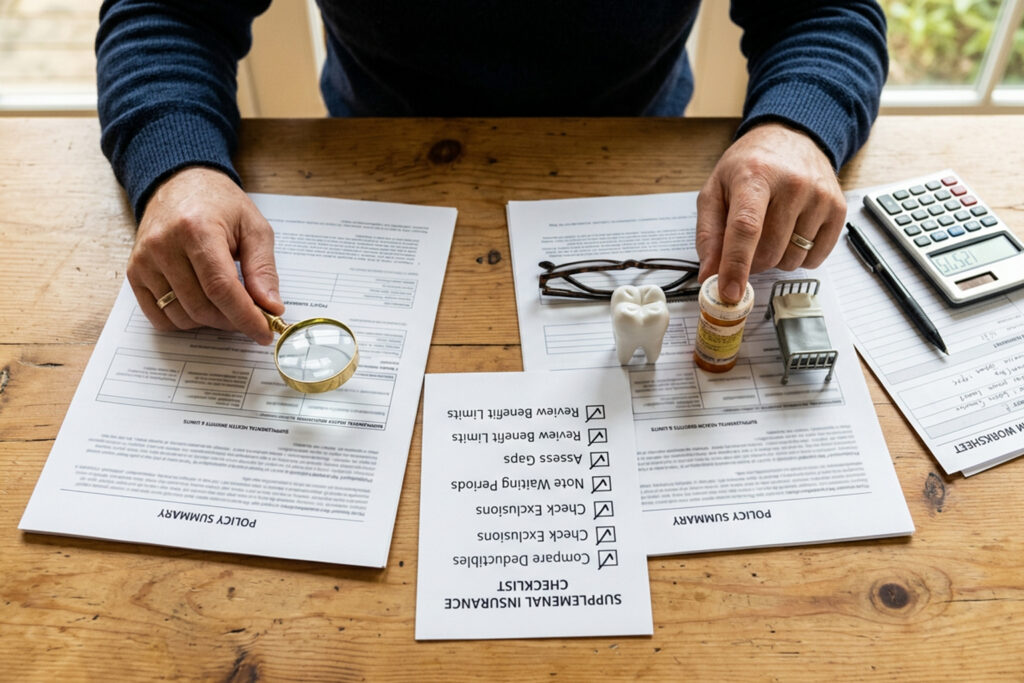
Premiums are only part of the price; inspect limits, waiting periods, and exclusions closely. A low monthly cost can come with long waiting periods or benefit caps that render the plan ineffective when you need it most. Also watch for exclusions tied to preexisting conditions or specific treatments. Small print matters: look for lifetime or annual maximums and how benefits are calculated.

Ask for sample claim scenarios from providers to see how the math works. That practical example often reveals where value is and where gaps remain.

Policy details and practical steps

Before you commit, confirm provider networks, claims filing timelines, and customer service options. Check whether you can bundle plans for a discount and whether there are guaranteed renewability clauses. Keep a one-page summary of key facts—premium, deductible, maximums, and contact info—for easy reference during open enrollment or renewals.

Policies change, so review annually and after any health or financial change. Staying proactive helps you avoid paying for unused benefits or being underinsured at a critical time.

Conclusion

Focus on the real gaps in your primary coverage and match benefits to likely needs. Compare costs against limits, waiting periods, and exclusions before buying. A simple checklist and yearly review will keep your supplemental coverage useful and affordable.

Practical Daily Credit Habits That Actually Work

Improving your credit doesn’t require dramatic moves or expensive services.
Small, regular choices add up over months.
This article lays out practical daily habits you can adopt without stress.
Follow a few steady routines to see more consistent score gains.

Check Your Credit Reports Regularly

Spend a few minutes each week scanning one credit report or a consolidated view from a free tool. Look specifically for unfamiliar accounts, incorrect balances, or misreported payment dates rather than trying to read every line. When you find an error, document it immediately: note the account, the date, and what looks wrong so you can file a clear dispute. Consistent, small checks make large surprises far less likely when you need credit.

  • Set a weekly calendar reminder to review part of a report.
  • Keep a short dispute log with dates and responses.
  • Save screenshots of items you plan to contest.

Doing this regularly reduces the time and stress involved in corrections. It also helps you spot identity theft early, which preserves your score and peace of mind.

Prioritize On-Time Payments

Payment history carries heavy weight in scoring and even a single late mark can linger. Automate at least the minimum payment, and schedule additional payments when cash flow allows so balances move down faster. If bill dates and pay dates don’t align, move payment due dates or split payments into smaller, more frequent transfers. Treat on-time payment as a daily habit: check balances and upcoming due dates during a quick morning or evening routine.

  • Set phone alerts a few days before due dates.
  • Consider two payments per month to lower reported balances.

Consistent punctual payments are the clearest, most reliable path toward steady score improvement. Small scheduling tweaks can prevent costly mistakes.

Manage Balances and New Credit Carefully

Keep card balances noticeably below limits; aim for well under half of each credit line whenever possible. Scoring looks at both overall utilization and individual account usage, so spreading small balances strategically helps. Avoid opening new accounts purely to raise available credit; new inquiries and account age changes can temporarily lower scores. When you need more room, ask for a credit limit increase instead of applying for another card.

  • Make off-cycle payments after big purchases to lower reported utilization.
  • Use balance alerts to avoid surprises.
  • Pay down the highest-rate balances first to reduce interest drag.

Small, frequent payments and a mindful approach to new accounts protect progress. Managing utilization daily keeps scores from fluctuating wildly.

Conclusion

Small, repeatable actions—checking reports, paying on time, and managing balances—add up into measurable credit progress.
You don’t need perfect finances to improve; you need steady, sensible habits and occasional adjustments.
Start with one daily routine and build from there to maintain upward momentum.

When to Pay More Than the Minimum: A Cardholder’s Guide

Credit card minimum payments are convenient, but they’re rarely the smartest move for your long-term finances. This guide explains when paying extra makes sense, how to choose an amount, and simple habits that reduce interest without stressing your cash flow. Read on for clear signals that it’s time to increase your monthly payment and practical steps to make that change sustainable. No jargon — just straightforward rules you can use on your next billing cycle.

How minimum payments really work

Minimums are typically a small percentage of your balance or a base dollar amount, and they keep your account in good standing while mostly covering interest. Because interest compounds, a low minimum can stretch repayment over years and dramatically increase the total cost. Carrying only minimums also keeps your credit utilization higher for longer, which can suppress your score. Treat the minimum as a safety net, not a repayment plan.

When you pay only the minimum, you’re trading short-term relief for long-term expense. That trade-off is fine occasionally, but it shouldn’t be your default behavior. Recognizing that difference is step one.

Clear situations when you should pay extra

There are a few practical scenarios that justify pushing past the minimum: when a balance has a high interest rate, after a one-off large purchase, if you want to improve credit utilization before applying for new credit, or when you have extra cash in a tight month and want to reduce future interest. Prioritize cards with the highest APR or those with no promotional rate that will start charging interest. Paying above the minimum in these moments saves money and simplifies future months.

  • High APR balances: attack these first.
  • Large recent purchases: pay down the spike.
  • Upcoming loan or refinance: lower utilization.

Use these triggers as practical signals rather than rigid rules; they help you focus extra payments where they do the most good.

Choosing how much extra to pay

Start with a simple formula: add a fixed extra amount you can sustain each month, or commit a percentage of your paycheck to credit repayment. If you have multiple cards, pay the minimum on all, then direct extra toward the highest-rate account until it’s down to a manageable level. Small increases—an extra $25 or $50—reduce interest and are easier to keep up with than dramatic spikes. Reassess every few months and adjust as balances fall and goals change.

Don’t overcommit. The best extra payment is one you can maintain without dipping into emergency savings or creating new debt. Consistency beats intensity.

Practical steps to make extra payments painless

Automate whenever possible: schedule a recurring payment larger than the minimum on each due date so you avoid forgetting and late fees. Use spare-change or round-up features in your bank app for occasional boosts, and consider applying windfalls—tax refunds, bonuses—directly to high-interest cards. Track progress with a simple spreadsheet or app so you see how interest and balances shrink; visible wins make it easier to keep going. Communication with partners about payment plans and priorities also reduces friction.

Small systems reduce stress and make extra payments a habit instead of a chore. Over time those habits translate to lower interest and stronger credit.

Conclusion

Paying more than the minimum is usually worth the short-term effort when it targets high interest or reduces utilization before a major financial move. Choose an extra amount you can sustain, automate payments, and direct windfalls to debt reduction. Those modest changes cut interest, shorten payoff time, and give you more financial flexibility.

A Simple Plan to Identify Gaps in Health Coverage

Insurance stacks can feel dense and uncertain; small gaps lead to big bills.
Before renewal or during life changes, a quick check can prevent surprises.
This short plan shows practical steps you can run through in an hour or two.
No jargon, no pressure—just clear actions to reveal where coverage falls short.

Inventory what you already have

Gather every ID card, policy document and recent explanation of benefits (EOB). Read the summary pages: look for coverage limits, waiting periods, and excluded services. Note any riders, such as foreign travel or home health benefits, and the effective and renewal dates. A clear snapshot of what you already pay for makes gaps easier to spot.

Put this information in one place—a folder, spreadsheet or photo album on your phone. Having it ready saves time when you call a provider or compare plans during open enrollment.

Compare common gaps to likely needs

Think about the care you use most and what could happen next year: routine prescriptions, specialist visits, or a planned procedure. Check whether your plan covers dental, vision, hearing aids, durable medical equipment, and long-term care services—these are frequent blind spots. Also confirm prescription tiers and whether preferred pharmacies or mail-order options apply. Don’t forget coverage limits for durable equipment and home health visits.

  • Dental and vision services
  • Prescription drug tiers and prior authorization rules
  • Skilled nursing, home health, and long-term care options
  • Out-of-network emergency and specialist access

Match the list to your likely needs and mark anything that could leave you exposed financially. Identifying just two or three real gaps gives you leverage when shopping for add-ons or riders.

Run a short cost test

Estimate a realistic year: count your normal visits, meds, and one or two higher-cost events such as a hospital stay. Calculate what you would pay with current deductibles, copays, and maximum out-of-pocket limits. Compare that to the price of a supplemental policy or a different plan to see whether extra coverage reduces risk or just adds cost.

Be practical: focus on likely scenarios rather than worst-case fantasies, and use the numbers to prioritize which gaps to close. If a small rider removes most of your exposure, it may be worth the premium.

Conclusion

Do this quick review annually and after any major life change.
A short, focused check will reveal the most important coverage gaps.
Addressing one or two gaps often provides the most protection for the least cost.