Build Credit Momentum With Small Reliable Routines

Improving a credit score rarely comes from one dramatic move. Small, reliable routines create steady momentum that lenders notice over time. Focused actions — not perfection — reduce mistakes and make progress obvious. This article lays out practical steps you can start this week and keep doing.

Set Up Payment Rhythms

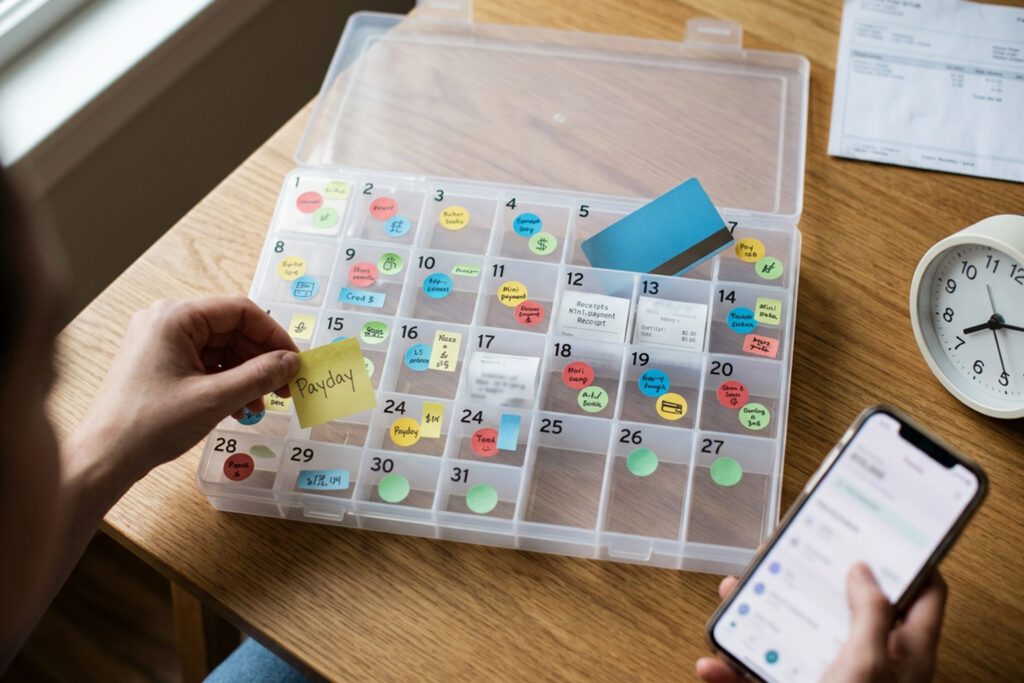
Making payments on time is the single most consistent influence on credit records. Choose a rhythm that fits your cash flow: align due dates with payday, automate recurring amounts, or set calendar reminders for manual payments. When automation isn’t an option, a short weekly check-in prevents missed bills and late fees that can set progress back. Over time those on-time marks build a pattern lenders and scoring models reward.

Small adjustments are enough to change outcomes. Even moving one bill date or splitting payments into two smaller ones can reduce the risk of missing a due date.

Trim and Manage Your Utilization

Credit utilization—the ratio of balances to limits—affects scores more than many people expect. Aim to keep balances low relative to each card’s limit, ideally below a third and lower if possible. If a bill is large one month, make multiple payments within the cycle rather than waiting for the statement closing date. That cuts reported balances and shows consistent management of available credit.

Requesting a modest credit-line increase, without adding new cards, can also improve utilization immediately. Do so cautiously and only when timing makes sense for your overall credit picture.

Add Positive Credit Pieces

Diversifying the types of credit you use can help, but it doesn’t mean you should open accounts unnecessarily. Consider small, manageable accounts that report activity: a secured card, a credit-builder loan, or an authorized-user arrangement on a trusted relative’s account. The goal is a steady stream of positive history rather than multiple new hard inquiries.

Reportable, on-time activity is what matters. Choose tools that fit your budget so the accounts enhance your profile rather than strain it.

Monitor and Adjust Regularly

Checking your credit reports and score at planned intervals keeps surprises from derailing progress. Look for reporting errors, unexpected hard inquiries, or a sudden balance spike so you can act quickly. A short monthly review and an annual full report check give you visibility without obsession.

Adjust routines when life changes—income shifts, new expenses, or a major purchase. Keeping plans flexible helps sustain momentum through different seasons.

Conclusion

Small, repeatable steps drive steady credit improvement more reliably than occasional grand gestures. Stick with rhythms that match your cash flow and correct course when needed. Over months, those routines add up into measurable progress.
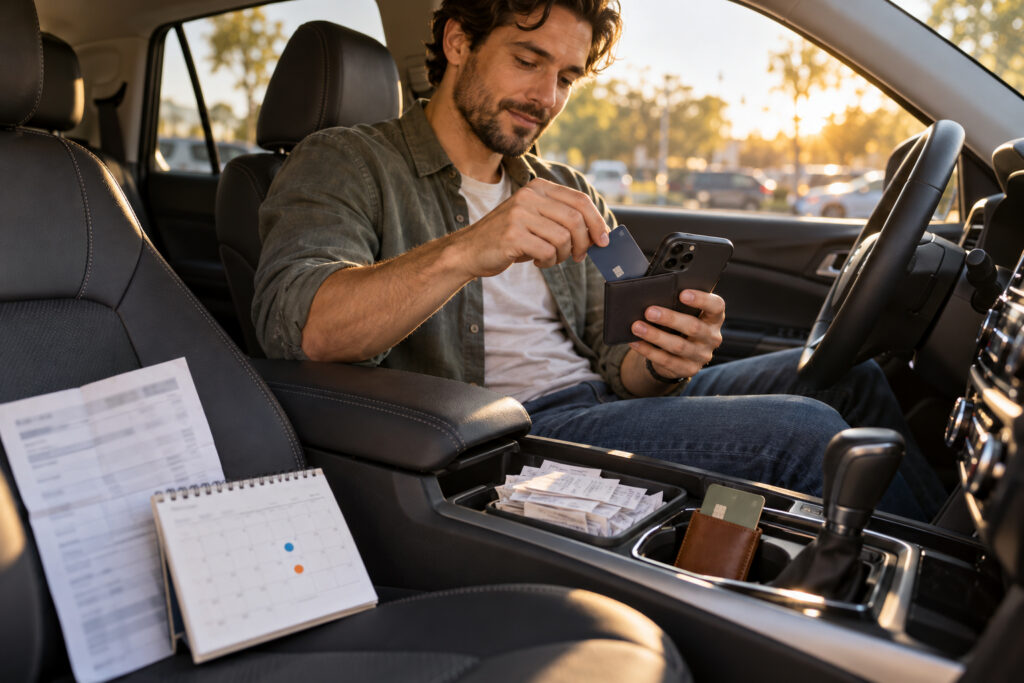
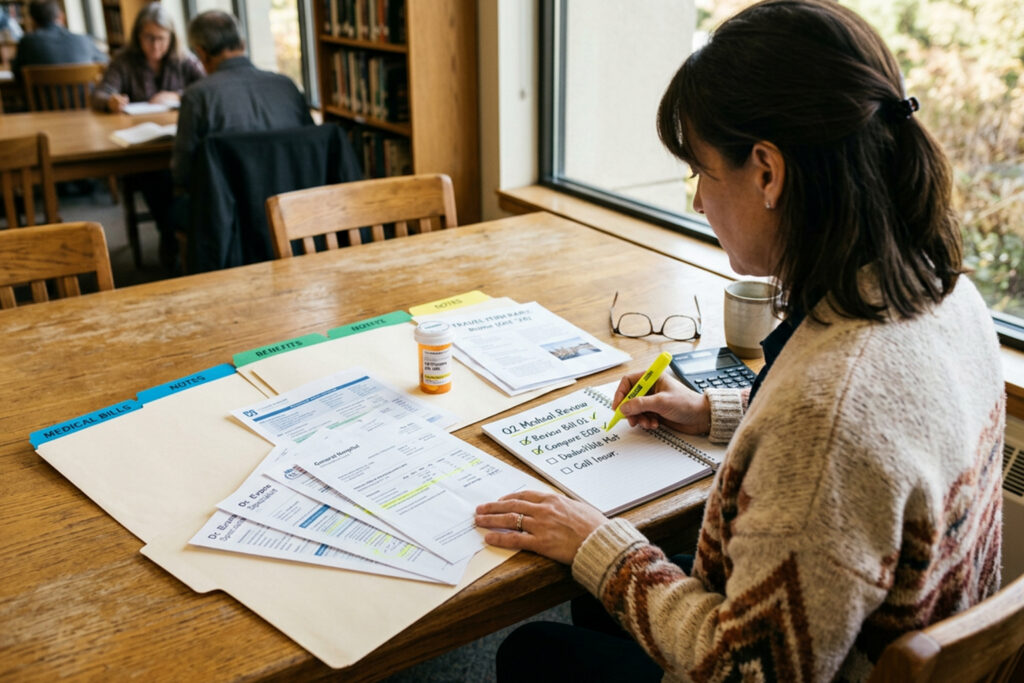
Match Your Cards to Paydays and Spending Habits

Picking the right card for each purchase can cut costs and increase rewards without adding complexity. Small, consistent rules make juggling two or three cards manageable for most households. This piece lays out practical choices tied to pay schedules and typical monthly spending. Follow a few simple adjustments and your cards will feel like tools, not headaches.

Choose One Primary Everyday Card

Pick a single card for routine purchases: groceries, gas, subscriptions and dining out. Use its rewards structure as the default and set it on your phone for contactless taps and recurring charges. Keeping one card dominant reduces missed opportunities and the risk of accidental credit inquiries from trying too many signups. If you have a specialized card for groceries or gas, treat that as a secondary, not the default.

Limit the number of active cards in daily rotation to two or three. That balance keeps rewards meaningful while simplifying statements and payment tracking.

Use Billing Cycles to Time Big Purchases

Align large expenses with billing cycles and paydays to improve cash flow without carrying a balance. If a purchase falls right after your statement closes, you effectively gain more interest-free days. That timing can reduce the need for short-term borrowing and lets you take advantage of promotional financing when it makes sense. Be mindful of how payment due dates interact with payroll deposits.

  • Check each card’s statement close date and due date in your account settings.
  • Plan big buys shortly after the statement date to extend your interest-free period.
  • Avoid overlapping too many large purchases across different cards in the same month.

Using billing cycles strategically doesn’t replace paying off balances—it’s a scheduling tool to improve cash flow and avoid interest.

Keep Payments Simple and Stay on Schedule

Automate at least the minimum payment for every card to prevent late fees and score hits. For best results, schedule full-pay automation for cards you can clear each month and set reminders for any cards you plan to rotate. Use a single calendar or budgeting app to mark due dates so one glance tells you what’s coming. Avoid carrying balances except when using promotional terms you can repay on schedule.

Consolidating due dates can help, but only if it doesn’t tempt overspending. Simplicity wins: fewer due dates, fewer surprises.

Review Annually and Protect Your Score

Once a year, audit which cards you actually use and why: rewards value, interest rate, annual fee and benefits. Close cards only when it makes strategic sense, since account age and limits influence credit history. Check statements monthly for errors and set alerts for suspicious activity. Keeping tabs on utilization rates—aiming below about 30% overall—helps maintain a healthier credit profile.

Regular reviews keep your set of cards aligned with changing spending patterns and financial goals. A light yearly tune-up prevents clutter from becoming costly.

Conclusion

Match card choices to when you get paid and how you spend each month.
Stick to one primary card, time big purchases around billing cycles, and automate payments.
A small annual review keeps the system efficient and your credit in good shape.

Adjusting Supplemental Insurance When Needs and Budgets Change

Facing a change in income or health needs doesn’t mean you have to accept surprise medical bills. Small, deliberate adjustments to your supplemental insurance can protect savings without leaving you exposed. This piece explains practical steps to review your existing policies, cut unnecessary costs, and keep the coverage that truly matters. You can approach the process one decision at a time and still come out ahead.

Start with an honest coverage audit

Begin by listing every policy you carry and the benefits each provides. Look beyond the premium: note deductibles, coinsurance, caps on benefits, and whether items like prescription drugs or dental care are included. Compare those details to the health services you actually use in a typical year. An audit makes it easier to spot duplicate coverage or benefits you pay for but rarely use.

  • Record annual premiums and out-of-pocket maximums.
  • Mark services you used in the past 12 months.
  • Highlight gaps like vision, dental, or chronic-condition support.

With clear numbers in hand, decide which policies reduce financial risk and which are discretionary. That clarity prevents knee-jerk cancellations that can create bigger bills later.

Prioritize benefits that matter now

Not all benefits are equally valuable. If you take several regular prescriptions, a drug rider or gap coverage may be essential even if it raises monthly cost. If you rarely see specialists, consider scaling back on high-premium riders for specialist visits. Factor in likely near-term events — planned surgeries or travel — when weighing options.

Budget decisions should reflect real needs, not worst-case hypotheticals. Keep core protections for hospitalization and chronic treatment, and trim extras that offer limited real-world value.

Shop smart: timing and comparison tactics

Open enrollment windows and life events are the best times to make changes without medical underwriting hassles. Gather quotes from multiple carriers and focus on total annual cost, not just the monthly premium. Read benefit summaries to confirm network restrictions, prior-authorization rules, and excluded conditions.

  • Request sample bills or benefit scenarios from insurers.
  • Ask about riders you can add temporarily for one-off events.

Small differences in wording can change how claims are paid, so use a checklist when comparing plans. A well-timed switch or a short-term rider can save money and preserve protection.

Conclusion

Adjusting supplemental insurance is a practical mix of math and judgment.
Focus on the benefits you use and the risks you can’t afford.
Make changes during enrollment or after life events to avoid surprises.

Little Moves That Gradually Raise Your Credit Score

Improving your credit score rarely happens overnight, but steady, sensible choices add up faster than you might think. Small changes — not dramatic overhauls — are easier to maintain and less likely to cause financial stress. This piece highlights practical adjustments you can make each month to nudge your score upward. Read on for realistic steps you can use without disrupting daily life.

Where to focus first

Begin with payment timing and outstanding balances because they influence the score most directly. Making payments on or before the due date prevents late marks, while lowering revolving balances reduces utilization, which scorers penalize. Look at accounts with the highest interest or balances and prioritize those when you have extra cash. Consistent progress here creates the clearest, quickest upward movement.

Set simple triggers that make these moves automatic and reliable. Calendar reminders, automatic transfers, or aligning due dates with payday cut down on missed payments. Small systems beat occasional motivation every time.

Practical habits to adopt

Adopt a few repeatable habits that build credit quietly over months. Keep old accounts open unless they carry steep fees, because longer histories help. Limit new credit applications to avoid multiple hard inquiries in a short span, and use credit cards for predictable expenses you can pay off. Regularly checking your report catches errors that could be dragging your score down.

  • Pay bills a few days early to avoid processing delays.
  • Keep monthly credit card balances below roughly 30% of limits.
  • Monitor one main report quarterly for surprises.

These habits are low-effort and compound over time, creating momentum without dramatic lifestyle changes. The checklist above can be completed in a few minutes each month.

Avoid these common missteps

High-risk moves often come from well-meaning attempts to accelerate improvement. Closing unused accounts without considering age and limits can unintentionally raise utilization. Chasing multiple new cards to increase total limits may lead to hard inquiries that temporarily lower your score. Also, ignoring small delinquencies is expensive because they escalate quickly.

Stick to modest, consistent corrections rather than trying to fix everything at once. A steady approach minimizes setbacks and keeps progress measurable.

Conclusion

Slow, steady adjustments to payment timing, balances, and habits typically outperform aggressive strategies. Build a short, repeatable routine and monitor results every month to stay on track. Over time those little moves add up into meaningful credit improvement.

Simple Card Rules to Smooth Monthly Cash Flow

Credit cards shouldn’t be a last-minute surprise on payday.
A few consistent rules can make them predictable tools instead of unpredictable bills.
This article lays out a compact routine to match cards to paydays, bills and rewards so you spend less time worrying and more time saving.
Follow the steps for a couple of billing cycles and you’ll notice fewer late fees and clearer cash flow.

Set a Simple Card Hierarchy

Choose two or three cards and give each a clear purpose: one for monthly bills, one for everyday purchases, and one as an emergency or specialty card. Assigning roles reduces accidental charges on the wrong card and makes it easier to track which balances to pay first. Keep the card used for recurring subscriptions separate so you can monitor and cancel unwanted charges quickly. Treat the emergency card as off-limits unless an unexpected expense genuinely requires it.

  • Primary card: rent, utilities, subscriptions.
  • Everyday card: groceries, gas, dining categories that match rewards.
  • Backup card: travel protections or true emergencies.

With roles defined, automation becomes simpler: set autopay for bills on the primary card and manual payments for the others when useful. The hierarchy also makes it easier to decide which balance to focus on if cash is tight.

Time Purchases Around Billing Cycles

Understanding each card’s statement close date and payment due date gives you two levers: when charges appear on a statement and when you actually need to pay. Charge non-urgent purchases just after the statement close to maximize float, and plan larger buys around paydays so you can clear the balance before interest kicks in. If a card has a promotional 0% period, map larger purchases to that timeline but track the end date carefully. Small timing shifts can free up one or two weeks of cash flow without incurring cost.

Use a calendar or app to display close and due dates side-by-side with your paydays. Those few minutes of planning prevent many common cash-flow scrambles.

Protect Your Cash Flow and Avoid Interest

Pay at least the statement balance each month whenever possible to avoid finance charges and keep utilization low. If you can’t, prioritize high-interest balances and move what you can to a card with a lower rate or a short promotional APR if you qualify. Keep an eye on fees—annual fees can be worth it if the rewards and protections offset them, but they should justify the cost. Regularly check for unauthorized charges and set alerts so small problems don’t become large ones.

Small habits—autopay where safe, alerts for due dates, and a short monthly review—go a long way toward protecting your cash flow. These safeguards keep credit working for you, not against you.

Conclusion

Simple rules and a little calendar planning turn credit cards into predictable financial tools.
Assign roles, time purchases, and protect cash flow with autopay and alerts.
Stick to the routine and your monthly budget will feel steadier and less stressful.

Practical Choices for Smarter Supplemental Health Coverage

Choosing supplemental health coverage can feel like sorting through a maze of options, premiums, and fine print. Start by clarifying what your base plan already pays for and where it leaves you exposed. Think about the services you use regularly and the expenses that would hurt your budget if they weren’t covered. A clear list of those risks makes the rest of the process far more purposeful.

Begin with realistic expectations about what insurance will do and what it will not. Keep the focus on practical protection rather than trying to eliminate every possible cost.

Start with a clear inventory

Begin by listing the benefits your primary insurance covers and marking the gaps: deductibles, co-payments, long hospital stays, or outpatient services. Include likely near-term needs such as prescription medication, routine dental work, or planned procedures. Knowing the dollar amounts attached to those gaps helps you compare plans like-for-like. This step prevents buying redundant coverage that adds cost without meaningful extra protection.

Documenting recent medical bills and expected expenses makes choices concrete rather than abstract. Keep those notes handy when reviewing quotes or talking to an agent.

Match coverage to likely needs

Not every extra benefit is worth the same to every person; align options with your personal health picture. For example, if prescriptions are your main expense, a plan that offers lower drug co-pays may be more valuable than broader hospitalization benefits. If mobility or dental work looms ahead, prioritize those riders instead. Aim to cover the highest-probability, highest-cost items first.

  • Prescription cost-sharing for chronic meds
  • Hospital indemnity for occasional long stays
  • Dental and vision for planned maintenance

Focus on a small set of priorities to keep premiums reasonable and benefits targeted. That balance is the heart of smart supplemental planning.

Weigh cost against real benefits

Compare annual premiums against the out-of-pocket exposure each plan reduces. A lower premium can be tempting but might leave you facing large bills for a single event. Look at maximum out-of-pocket limits and what triggers full benefits, not just the headline premium. Also consider how a plan coordinates with other insurance rather than overlaps unnecessarily.

Run simple scenarios: what happens if you need a week-long hospital stay or several months of specialty medication. Those quick calculations reveal which plans truly protect your finances.

Watch for exclusions and timing

Read exclusions carefully and note waiting periods, pre-existing condition clauses, and enrollment windows. Some benefits only start after a waiting period or exclude certain services forever, which can make a policy less useful when you need it. Timing matters: missing an enrollment window can mean limited options or higher costs later. Ask clear questions and get answers in writing when a policy detail is important to you.

Keep renewal dates and annual review reminders on your calendar so coverage still fits your needs next year. A small review each season can save surprises down the road.

Conclusion

Practical supplemental coverage begins with a clear list of gaps and likely expenses. Match benefits to those needs, compare real costs against potential savings, and check exclusions and timing carefully. With focused choices and an annual review, you can secure useful protection without paying for what you don’t need.

Pay Smarter, Not Harder: Building Better Credit Habits

Small, consistent choices about when and how you use credit shape the scores lenders see. This article focuses on practical moves you can adopt without overhauling your entire budget. Pick a couple of tactics and stick with them for a few months to see steady improvements. The goal is momentum: gradual progress that becomes routine.

Prioritize Payment Timing

Paying on time is the single most influential habit for most credit scores, and timing matters more than many people realize. Set payments a few days before the due date and align them with your pay schedule so you never miss a cycle. If you struggle with one account, move its due date or set an automated partial payment immediately after payday. Consistent punctual payments build a reliable history that lenders favor.

Automate where it helps and review statements monthly to catch stray charges. Even small late fees or a missed payment can slow progress, so make timing a simple protective routine.

Lower Utilization, Raise Scores

Credit utilization—the percent of available revolving credit you use—is a fast-moving factor you can influence. Try to keep utilization under roughly 30% on each card and overall, and aim lower if you want quicker gains. If a statement balance is high one month, make an extra payment before the statement closing date to reduce the reported balance. Increasing your credit limit can also help, but only if it doesn’t encourage more spending.

Watch each account’s reported balance rather than just your current balance. Small, repeated reductions will help the score reflect safer borrowing behavior.

Keep Accounts Active Strategically

The age and diversity of accounts contribute to credit profiles, so closing old cards can sometimes do more harm than good. Use older accounts occasionally for small purchases you pay off quickly to keep them active. For new accounts, resist opening several at once because multiple inquiries and a shortened average age can weigh on your score. Think of each account as a long-term piece of your credit history.

Maintain a balance between keeping older accounts open and avoiding unnecessary new ones. Strategic activity protects your credit age and mix over time.

Monitor and Correct Your Report

Regularly checking your credit report reveals mistakes and unexpected activity that could drag your score down. Dispute clear errors promptly and follow up until they’re corrected; even one erroneous late payment can have a large effect. Monitoring alerts also helps you spot identity issues early, letting you act before larger problems develop.

Use free annual reports and low-cost monitoring tools as suits your comfort level. Knowing what’s on your report gives you control to make informed, corrective decisions.

Conclusion

Small, repeatable payment and usage habits reliably change credit trends over months rather than overnight. Focus on timing, utilization, account management, and regular checking to build credit with confidence. Consistency matters more than perfection, and steady choices add up.

A Few Habits That Keep Credit Cards Simple

Credit cards don’t have to be a source of stress. With a handful of steady habits you can keep rewards, payment timing, and fees under control. This article focuses on small routines that prevent surprises and preserve your cashflow. Adopt one change at a time and you’ll see how little adjustments add up.

Start with clear purposes for each card, then move to practical payment habits that fit your calendar. Small, repeatable actions are easier to maintain than grand financial overhauls. The goal is predictability, not perfection.

Choose Two Primary Cards

Most people only need two main cards: one for everyday spending and one for larger purchases or rotating rewards. Keeping to two limits decision fatigue and makes monitoring balances simpler. Pick cards with complementary benefits so you’re not duplicating categories or annual fees. Avoid chasing every bonus; consistency wins.

Having a backup card for emergencies is fine, but keep it inactive for routine charges. That reduces fraud exposure and keeps your credit utilization clear.

Match Cards to Regular Spending

Identify three regular categories where you spend most: groceries, gas and utilities, for example. Assign each category to the card that offers the best return and habitually use that card for those purchases. If a card has rotating categories, note activation and start dates so you don’t miss higher rewards. A simple labeled wallet or app note can prevent slip-ups.

When rewards change, review and reassign categories quarterly. This keeps your setup aligned with real spending without constant overthinking.

Pay on a Rhythm That Fits Your Cashflow

Pick a payment rhythm tied to paydays: one principal payment right after you get paid, and a final statement payoff before the due date. That approach reduces interest risk and keeps balances predictable. If you can, set autopay for the minimum and manually clear the rest on payday to avoid overdrafts. Treat the card like a short-term loan, not free money.

Regular reviews of statements catch errors and subscription creep. A quick monthly check takes minutes and saves headaches later.

Protect Simple Rules With Automation

Use calendar alerts and bank rules to enforce your habits without relying on memory. Set alerts for statement closing dates, card activations, and reward category switches. If you carry a balance strategically for a large purchase, automate a plan to eliminate it within a set number of months. Automation reduces friction and keeps your plan honest.

Combine automation with one monthly habit: a five-minute review of charges and benefits. That small ritual preserves control and keeps complexity from creeping back in.

Conclusion

Keep your credit card routine small and consistent. Choose clear roles for each card, pay on a rhythm tied to your cashflow, and use automation to enforce rules. These tiny changes make credit cards predictable and useful without drama.

What Every Shopper Overlooks in Supplemental Insurance Policies

Supplemental insurance can feel like a tangle of fine print and benefit names that sound similar but behave differently.
Many buyers pick a plan because premiums look low or a familiar word appears in the title.
Those simple choices can leave gaps when a claim arrives or a preferred provider isn’t covered.
This piece points out the small items that change how a policy performs when you need it most.

Before you make any switch or add-on, take a moment to look past surface features and understand the mechanics behind them.

Why the fine print matters

Two policies with the same monthly cost can pay out very differently depending on limits, waiting periods, and exclusions. Read the clauses about preexisting conditions, lifetime caps, and what counts as a covered event; they often determine real value more than the headline benefit. Pay attention to how benefits are triggered — some plans require a hospital stay, others pay for outpatient procedures, and that affects whether you’ll see reimbursement. Also note whether inflation or annual adjustments are built in, since fixed-dollar benefits lose buying power over time.

  • Look for definitions of key terms like “disability” or “qualified provider.”
  • Check how long the insurer has to respond to claims and appeals.

Those items won’t be highlighted in marketing, but they control the speed and amount of any payout. A quick scan now saves frustration later.

Commonly overlooked policy items

People often skip details about network rules, coordination with other insurance, and rider exclusions. Network restrictions can force you to use providers who accept the plan, or leave you paying much more out of pocket for out-of-network care. Coordination clauses explain whether the supplemental plan pays before or after your primary coverage, which affects your immediate bills. Riders and add-ons may seem inexpensive until you realize they duplicate benefits you already have elsewhere.

  • Out-of-network penalties and referral requirements.
  • How the policy interacts with employer or government benefits.
  • Whether certain treatments require prior authorization.

Spotting these items ensures the policy fills genuine gaps instead of offering redundant or unusable coverage. It also helps you compare apples to apples.

Checklist to review before you commit

Put a short checklist together: definitions, limits, waiting periods, network rules, coordination, and appeals procedures. Ask for sample claim scenarios from the insurer so you can see how benefits would apply in practice. Confirm any verbal assurances in writing and note the effective date for coverage changes. Finally, compare the total expected annual cost — premiums plus likely out-of-pocket expenses — not just the monthly price.

  • Request a copy of the policy and read highlighted clauses.
  • Call customer service with specific hypothetical claims to test responses.
  • Check review periods and cancellation terms.
  • Make sure any agent promises are included in the contract.

These steps help you choose a plan that behaves as you expect when you claim. They also reduce surprises and make comparisons clearer.

Conclusion

Small policy details often determine whether supplemental coverage actually helps when you need it.
Spend time on definitions, limits, and how the plan works with other coverage before you buy.
A focused review now will protect your finances and give you clearer peace of mind later.

Timing, Limits, and Checks: A Quiet Plan for Better Credit

Small, consistent choices have more impact on credit than dramatic one-off moves.
If you focus on when you pay, how much credit you use, and whether your reports are accurate, scores tend to improve steadily.
This piece lays out a few practical adjustments you can make without adding stress to your day.
Read on for specific, repeatable steps that fit into ordinary routines.

Set clear payment priorities

Start by identifying the bills that matter most to scoring: on-time payments for loans and revolving accounts. Use calendar alerts or automatic payments to avoid missed due dates, but keep enough control to adjust amounts when cash is tight. If you must choose what to pay first, prioritize accounts that have recently fallen behind and those with the largest balances relative to their limits. These focused moves protect score factors that weigh most heavily in most scoring models.

Make a weekly review part of your routine so payments stay on track. A short check-in helps catch anomalies before they become delinquencies.

Manage balances and credit limits

Credit utilization—the ratio of your balances to available limits—affects scores quickly. Aim to keep utilization well below the apparent maximum by paying down cards during the billing cycle, not just at statement due date. If you can, request higher limits on stable accounts; that reduces utilization without increasing debt. Avoid opening multiple new accounts at once, as new inquiries and new limits can temporarily lower a score.

Small reductions in utilization often produce visible score improvement. Treat limits like a tool rather than extra spending room.

Use tools that reduce friction

Technology makes staying on top of credit simpler than ever. Set up autopay for fixed amounts, enable text or app alerts for high balances, and schedule monthly time to reconcile statements. For unpredictable months, lower an autopay temporarily and plan a catch-up when cash is steadier. These modest systems stop reactive scrambling and reduce the chance of errors or missed payments.

  • Autopay for minimums, manual top-ups for extra reductions.
  • Alerts for balances above chosen thresholds.

Build these protections gradually so they become habits, not chores. Consistency matters more than perfection.

Monitor reports and fix mistakes

Errors on credit reports are common and removable, but they won’t correct themselves. Check reports at least once a year and dispute any inaccuracies promptly. If identity theft or a billing mistake shows up, act quickly with the creditor and the reporting agency to file disputes and document responses. Even small, corrected errors can lift a score faster than months of careful payments.

Keep a simple folder or digital record of disputes and outcomes. That documentation speeds follow-ups if issues reappear.

Conclusion

Small timing adjustments, disciplined balance management, and routine checks add up over months.
They reduce risk of setbacks while nudging scores upward in measurable ways.
Stick to practical systems and review results periodically to stay on course.